LIFE INSURANCE · POLICY COMPARISON
Term Life vs. Whole Life Insurance: What Families Should Know
Understand how term and whole life insurance differ in coverage, cost, cash value, and long-term protection—so you can make a more informed decision for your family.
Two Types of Life Insurance, Two Different Approaches to Protection
Imagine two families who are considering life insurance.
The first family has two young children, a mortgage, and 20 years remaining before retirement. Their primary concern is making sure the children can continue their education and the surviving parent can manage household expenses if one income disappears.
The second family has accumulated substantial savings and wants to maintain a death benefit for a longer-term financial objective, potentially beyond their working years.
Both families may benefit from life insurance, but they may not need the same type of policy.
One might prioritize affordable protection for a specific period. The other might value permanent coverage and additional policy features.
This is where understanding the difference between term life insurance and whole life insurance becomes important.
Both can provide a death benefit to beneficiaries when a covered death occurs and the policy remains in force. But they differ in duration, premium structure, cash value, flexibility, and long-term cost.
The right starting point is not which policy sounds more attractive. It is what financial responsibility you are trying to protect.
1. What Is Term Life Insurance?
Term life insurance provides coverage for a specified period, commonly 10, 15, 20, or 30 years, although available terms vary by insurer.
If the insured person dies during the coverage period while the policy is in force, the insurer generally pays the death benefit to the designated beneficiaries, subject to the policy's terms.
If the term expires and the insured person is still living, the coverage typically ends unless a renewal, extension, or conversion option is available and exercised.
Most term life policies do not accumulate cash value.
How term life insurance works
Consider a hypothetical 35-year-old parent who purchases a 20-year term life insurance policy with a $500,000 death benefit.
The policy is intended to provide protection while the family's children are growing up and the household is paying down its mortgage.
If the insured person dies during the 20-year term and the claim is covered, the beneficiaries would generally receive the $500,000 death benefit.
If the insured person survives the term, the policy may expire without a payment.
That does not mean the policy failed.
Life insurance is designed to protect against a financial risk. Like other forms of insurance, a policy can provide valuable protection even when no claim occurs.
Why families consider term life insurance
Term life insurance is often considered for financial responsibilities that are expected to decrease or end over time, including:
- Replacing income during working years.
- Supporting children until they become financially independent.
- Helping a surviving spouse manage mortgage payments.
- Covering major family obligations during a defined period.
- Supplementing employer-provided life insurance.
For many households, the ability to purchase a substantial death benefit at a relatively lower initial premium is an important advantage.
2. What Is Whole Life Insurance?
Whole life insurance is a form of permanent life insurance.
It is generally designed to remain in force for the insured person's lifetime, provided required premiums are paid and the policy's conditions are met.
Unlike most term policies, traditional whole life insurance also includes a cash-value component.
A portion of the policy's financial structure supports the accumulation of cash value over time.
Traditional whole life policies generally offer scheduled premiums and guaranteed policy values, subject to the insurer's contractual obligations and the policy's terms.
However, specific features can vary.
How whole life insurance works
Imagine a 35-year-old purchasing a $250,000 whole life policy.
The policy is designed to provide a death benefit beyond a limited 20- or 30-year period.
Over time, the policy may accumulate cash value according to its contractual terms.
The policyholder may be able to access some of that value through withdrawals, surrender, or policy loans, depending on the policy.
But accessing cash value is not the same as withdrawing money from a regular savings account.
Policy loans generally accrue interest. Loans and withdrawals can reduce the death benefit and cash value, and excessive borrowing may cause the policy to lapse.
A lapse or surrender can also have tax consequences in some circumstances.
Whole life insurance therefore requires an understanding of both the death benefit and the financial obligations involved in maintaining the policy.
3. Term Life vs. Whole Life: Side-by-Side Comparison
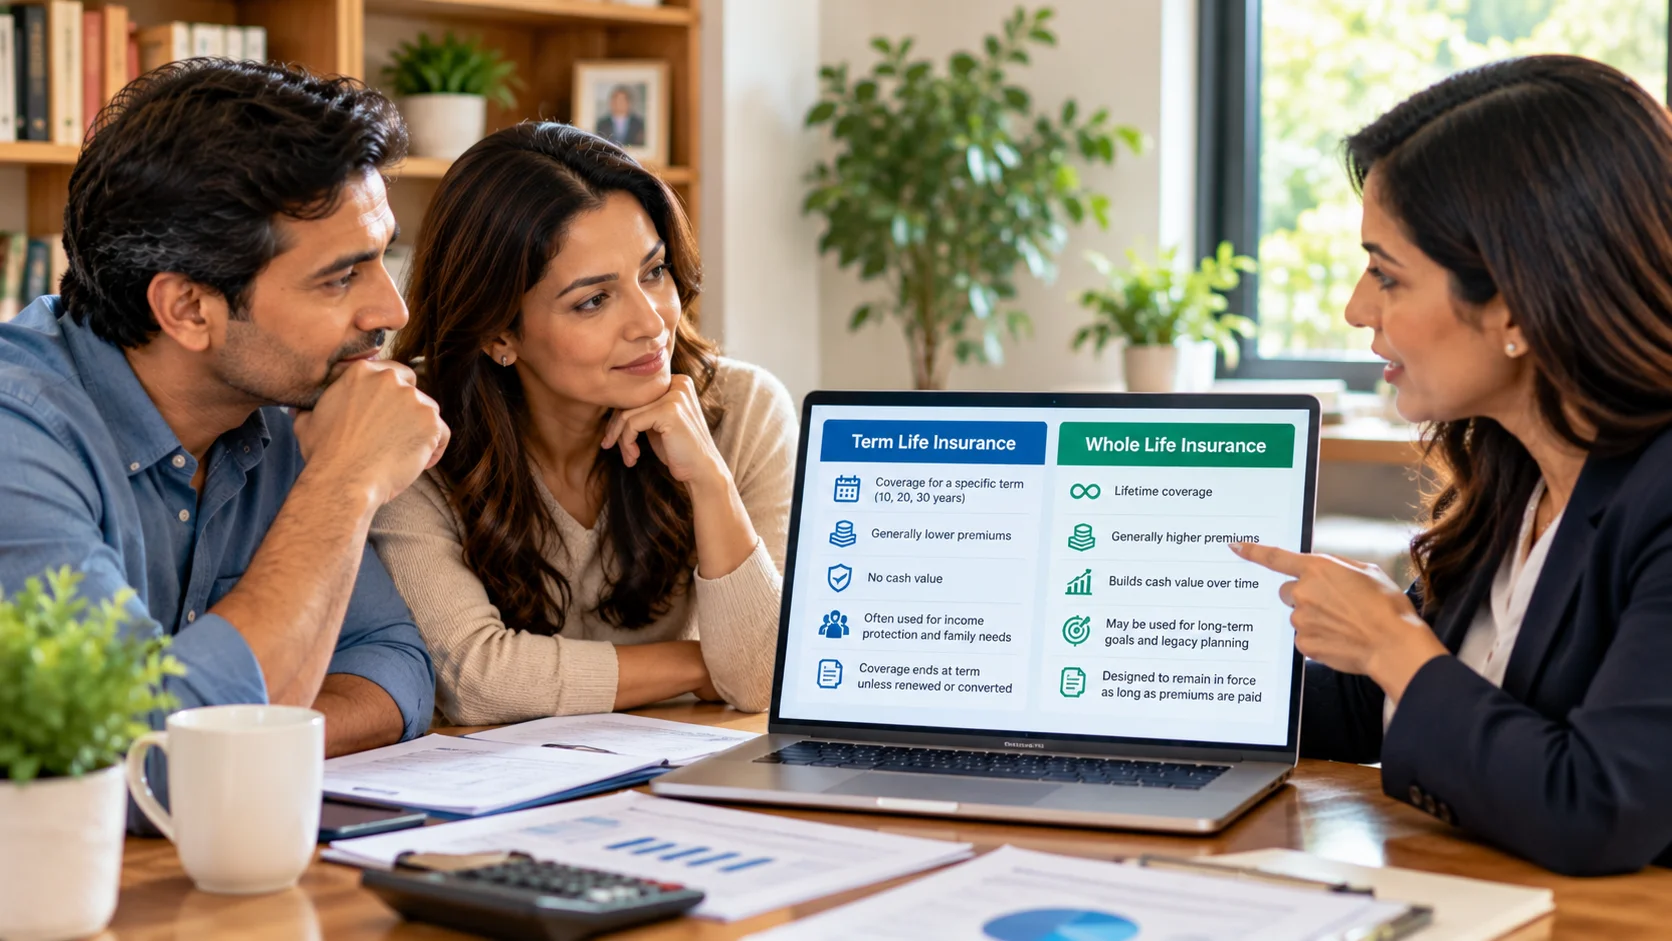
The following table summarizes common characteristics of traditional term life and whole life insurance.
| Feature | Term life insurance | Whole life insurance |
|---|---|---|
| Coverage duration | Defined term | Designed for lifetime coverage |
| Initial premiums | Generally lower for comparable coverage | Generally higher |
| Cash value | Usually none | Included |
| Death benefit | Payable for a covered death while coverage is in force | Payable for a covered death while coverage is in force |
| Premium structure | Often level for an initial guaranteed period | Often scheduled and level under traditional policies |
| Policy expiration | Usually expires at the end of the term unless continued | No fixed term expiration under a traditional lifetime policy |
| Primary planning use | Temporary financial obligations | Long-term or permanent financial objectives |
| Complexity | Usually simpler | More features and considerations |
These are general characteristics, not a description of every policy available in the market.
Insurers may offer different term structures, riders, premium schedules, and permanent life insurance products.
For that reason, it is important to review actual policy illustrations and contractual provisions before making a decision.
4. Why Is Whole Life Insurance Usually More Expensive?
One of the most noticeable differences between term and whole life insurance is the premium.
For a similar death benefit and insured person, whole life insurance generally has a higher initial premium than term life insurance.
There are several reasons.
Term insurance is designed to provide protection for a limited period. Most policies do not accumulate cash value.
Whole life insurance is designed to provide longer-duration protection and includes contractual cash-value features.
Those additional obligations and features affect the premium.
An illustrative comparison
Suppose a family is evaluating two hypothetical policies:
Option A: Term life insurance
- $500,000 death benefit.
- 20-year coverage period.
- No cash-value accumulation.
- Lower initial premium relative to a comparable whole life policy.
Option B: Whole life insurance
- $500,000 death benefit.
- Designed for lifetime coverage.
- Cash-value component.
- Higher initial premium relative to a comparable term policy.
The whole life policy may provide features the term policy does not.
But those features come with a financial commitment.
For a household managing mortgage payments, childcare expenses, and retirement savings, affordability can be an important part of the decision.
A policy that looks attractive on paper may not be suitable if its premiums are difficult to maintain over time.
Premiums vary significantly with age, health, tobacco use, coverage amount, policy design, and underwriting classification. Actual quotes are needed for a meaningful cost comparison.
5. What Happens When a Term Life Policy Expires?
Term life insurance is designed around a defined coverage period.
Suppose you purchase a 20-year term policy at age 35.
At age 55, the original term ends.
If you are still living, the policy may expire, or it may offer an option to continue coverage under different terms.
Some term policies allow renewal without a new medical examination, but renewal premiums can be substantially higher because they reflect older attained ages and the contract's pricing structure.
Other policies offer a conversion feature.
What is term conversion?
A term conversion provision may allow the policyholder to convert eligible term coverage to an available permanent life insurance policy without undergoing new medical underwriting.
This can be valuable if health circumstances change after the original policy was purchased.
However, conversion rights are not unlimited.
They may be subject to age restrictions, deadlines, available permanent products, and other conditions.
The new premium is generally based on the permanent policy and applicable conversion rules.
Before purchasing term insurance, review whether conversion is available and when that option expires.
6. Does Whole Life Insurance Build Savings?
Whole life insurance can accumulate cash value, but it should not be treated as identical to a bank savings account or a conventional investment.
Cash value is part of the insurance contract.
Its accumulation depends on the policy's design and contractual terms.
Some participating whole life policies may also pay dividends.
Dividends are generally not guaranteed and depend on the insurer's experience and dividend practices.
Can you withdraw the cash value?
Depending on the policy, you may be able to access value through:
- Policy loans.
- Withdrawals, if permitted.
- Partial or full surrender.
- Certain contractual options.
Each method has potential consequences.
A policy loan typically reduces the net amount payable to beneficiaries if it remains outstanding at death.
Loans also accrue interest and can affect the policy's ability to remain in force.
Surrendering the policy generally ends its life insurance protection.
Tax treatment can vary, particularly when a policy is classified as a modified endowment contract or when withdrawals or surrender proceeds exceed the policyholder's investment in the contract.
It is important to understand these details before viewing cash value as money available for everyday spending.
Do beneficiaries receive both the death benefit and cash value?
Under a typical whole life policy, beneficiaries generally receive the policy's death benefit, adjusted for any outstanding loans and other applicable provisions.
They do not ordinarily receive the stated death benefit plus the full accumulated cash value as two separate payments.
Specific policy designs can differ, so review the contract and illustration.
This distinction is important when comparing policy values.
7. Which Type of Insurance Is Better for Young Families?
Consider a couple in their early 30s with two children.
They have a mortgage, childcare expenses, and retirement savings goals.
Their main concern is protecting the household financially during the next 20 to 25 years.
In this situation, term life insurance may be a practical option to evaluate because it can provide substantial coverage during the years when the household has significant financial obligations.
For example, a 25-year term policy might be aligned with the period when the children are growing up and the mortgage is being paid down.
That does not automatically make term life insurance the best choice for every young family.
Some families may also have permanent protection needs, such as providing long-term support for a dependent with lifelong care requirements.
The important distinction is between temporary financial responsibilities and needs that may continue indefinitely.
Coverage duration should reflect those responsibilities.
8. When Might Whole Life Insurance Make Sense?
Whole life insurance may be worth considering when a person has a clearly identified need for permanent coverage and can comfortably maintain the premiums.
Potential circumstances include:
Long-term dependent support
A family caring for a dependent who may require lifelong financial assistance might consider permanent life insurance as one component of a broader financial and estate plan.
Estate or legacy planning
Some households use permanent life insurance to help provide liquidity for estate-related obligations or to leave a financial legacy.
The appropriateness of this approach depends on estate size, tax rules, ownership arrangements, and other planning considerations.
Long-term coverage preferences
A person may prefer a policy designed to remain in force for life rather than one that expires after a defined term.
Interest in contractual cash-value features
Some individuals value the cash-value and premium structure of traditional whole life insurance.
However, these features should be evaluated alongside policy costs, alternatives, liquidity needs, and the financial strength of the insurer.
Permanent insurance should serve a clear financial purpose. It should not be purchased solely because the word "permanent" sounds safer or more valuable.
9. Can You Combine Term Life and Whole Life Insurance?
Yes. Some people use more than one type of life insurance to address different financial objectives.
For example, consider a household that wants:
- A substantial death benefit while children are financially dependent.
- A smaller amount of protection intended to remain in force later in life.
The household might evaluate a combination of term and permanent insurance.
This is sometimes called a layered approach to coverage.
However, combining policies increases the number of premiums and contractual terms that must be managed.
It is not automatically more efficient or appropriate than purchasing a single policy.
The combined cost, coverage amounts, policy durations, and financial objectives should be reviewed carefully.
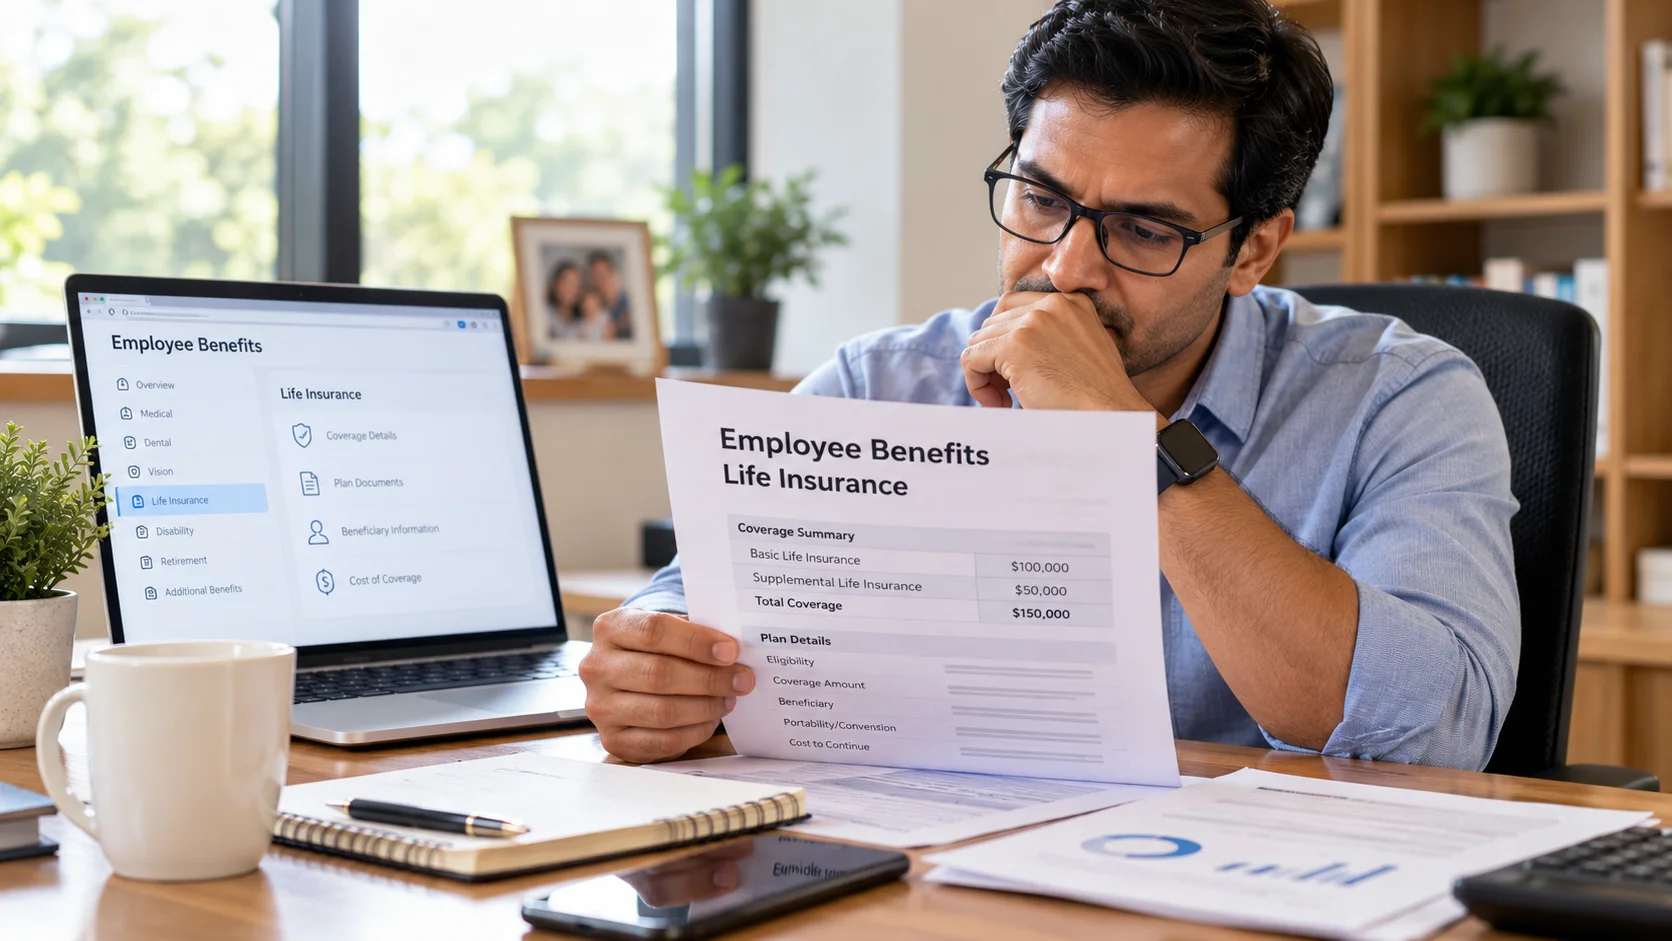
10. What If You Already Have Life Insurance Through Work?
Many employees receive basic group life insurance through their employers.
Some also purchase supplemental workplace coverage.
That coverage should be considered when evaluating additional term or whole life insurance.
For example, someone may have:
- $100,000 of employer-provided group life insurance.
- $200,000 of supplemental workplace coverage.
- No individual life insurance.
The combined workplace death benefit may be meaningful.
However, the employee should understand what happens if employment ends or eligibility changes.
Some plans offer portability or conversion options, but these are subject to the plan's rules.
An individually owned term or whole life policy generally is not dependent on remaining with a particular employer, provided the policy stays in force.
Before purchasing additional coverage, compare your current benefits with your household's estimated financial needs.
11. Common Mistakes When Comparing Term and Whole Life
Choosing only by monthly premium
Lower premiums can be attractive, but coverage duration and policy features also matter.
A lower-cost policy may not address a genuinely permanent financial need.
Conversely, paying more for permanent coverage may be unnecessary if the need is temporary.
Treating whole life as a guaranteed high-return investment
Traditional whole life insurance may provide guaranteed contractual values, but that does not mean it guarantees high investment returns.
Costs, policy design, and the timing of cash-value accumulation are important.
Assuming term insurance is wasted money if no claim occurs
The purpose of term insurance is financial protection during a specified period.
A policy can fulfill that purpose without paying a death benefit.
Ignoring affordability
Life insurance protection depends on keeping the policy in force.
Premiums that strain the household budget may create a risk of future lapse.
Forgetting to review coverage
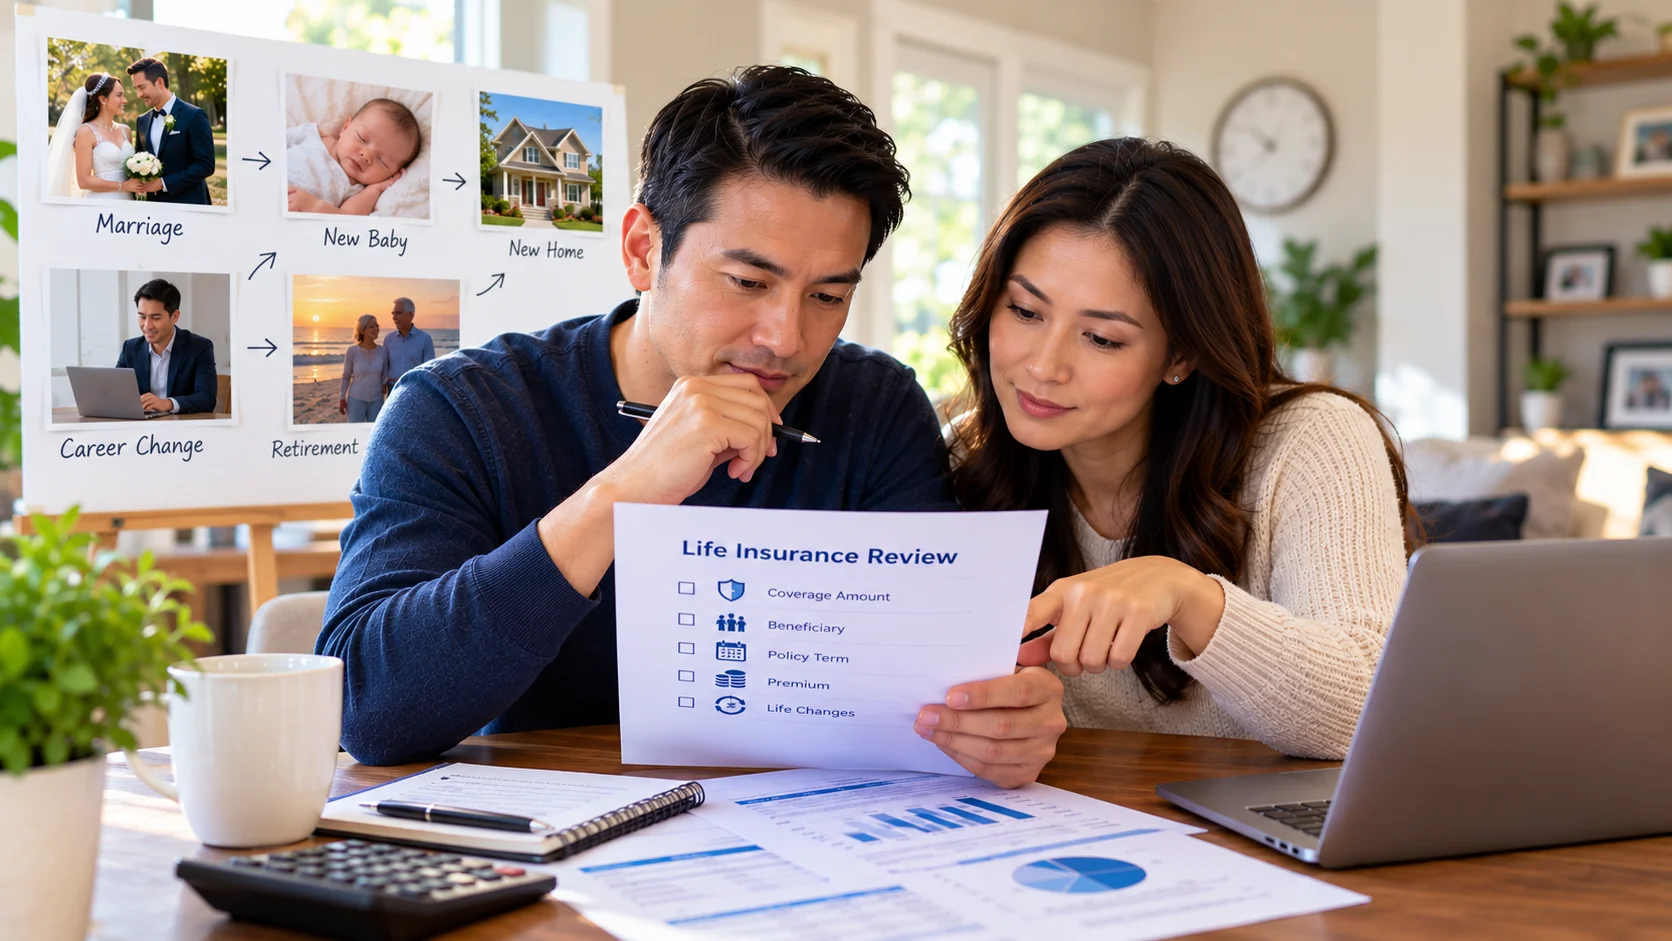
A policy selected before marriage, children, or homeownership may no longer align with current needs.
Reviewing coverage after major life changes can help identify whether adjustments are appropriate.
12. How to Decide Which Policy Fits Your Family
Instead of starting with a product name, begin with five questions.
Question 1: Who depends on you financially?
Consider your spouse, children, aging parents, or anyone else who relies on your income or caregiving.
Question 2: How long would they need financial support?
A family with young children may have a defined period of substantial financial responsibility.
Someone supporting a dependent with lifelong needs may have a different planning horizon.
Question 3: How much coverage do you need?
Estimate income replacement, housing costs, education expenses, other obligations, and available resources.
Avoid relying entirely on an income multiplier.
Question 4: What premium can you comfortably maintain?
Evaluate affordability alongside your emergency savings, retirement contributions, and other financial commitments.
Question 5: Do you have a genuine need for permanent coverage or cash value?
If your primary objective is income protection during working years, term insurance may be worth evaluating first.
If your objectives require lifelong protection, permanent insurance may deserve consideration.
For complex estate, tax, or special-needs planning, qualified professional guidance can be particularly important.
13. How Turtelle Helps Families Understand Their Protection
Choosing between term and whole life insurance is easier when you first understand your family's financial protection needs.
Turtelle Insurance's Family Protection Check provides an educational starting point for reviewing your financial responsibilities and existing coverage.
The assessment helps families explore how their protection may relate to household needs, including employer-provided insurance and individually owned policies.
Turtelle's proprietary Family Protection Score is designed to help communicate the assessment results in an understandable way.
The Protection Check is not an insurance underwriting decision, a guarantee of policy eligibility, or a substitute for individualized professional advice.
The objective is to help families better understand their circumstances before evaluating coverage options.
Final Thoughts
Term life and whole life insurance are both designed to provide financial protection, but they serve different purposes.
Term life insurance generally offers lower initial premiums and coverage for a defined period.
Whole life insurance is designed for longer-term protection and includes contractual cash-value features, usually at a higher premium.
Neither product is universally better.
A young family protecting income during child-raising years may have different priorities from someone planning for a lifelong dependent or a permanent financial obligation.
Before choosing a policy, identify the people you want to protect, the responsibilities you want to cover, and the amount you can reasonably afford.
The best life insurance decision is not about choosing the most complicated policy or the lowest advertised premium. It is about matching the protection to the need.
Check My Family Protection Score
The free Family Protection Check™ shows how your workplace coverage, personal policies and family needs fit together, and whether there may be a gap.
Check My Family Protection ScoreFrequently asked questions
Is term life insurance better than whole life insurance?
Neither is automatically better. Term life insurance is often considered for financial needs lasting a defined number of years. Whole life insurance may suit people with a need for permanent coverage and an interest in contractual cash-value features.
What happens if I outlive my term life insurance policy?
Coverage generally ends when the term expires unless you use an available renewal, continuation, or conversion option. Most term policies do not pay a benefit simply because the insured person survives the term.
Does whole life insurance build cash value?
Yes. Traditional whole life policies include cash value that accumulates according to the policy's contractual terms. Loans, withdrawals, and surrender can affect coverage and may have tax consequences.
Can I own both term life and whole life insurance?
Yes. Some people combine policies to address temporary and permanent protection needs. The combined cost and coverage should be evaluated against the household's financial goals.
Why is whole life insurance more expensive than term life?
Whole life insurance is designed for longer-duration protection and includes cash-value features. These additional contractual benefits generally result in higher initial premiums than comparable term life coverage.