LIFE INSURANCE · POLICY REVIEW
When Should You Review or Update Your Life Insurance Policy?
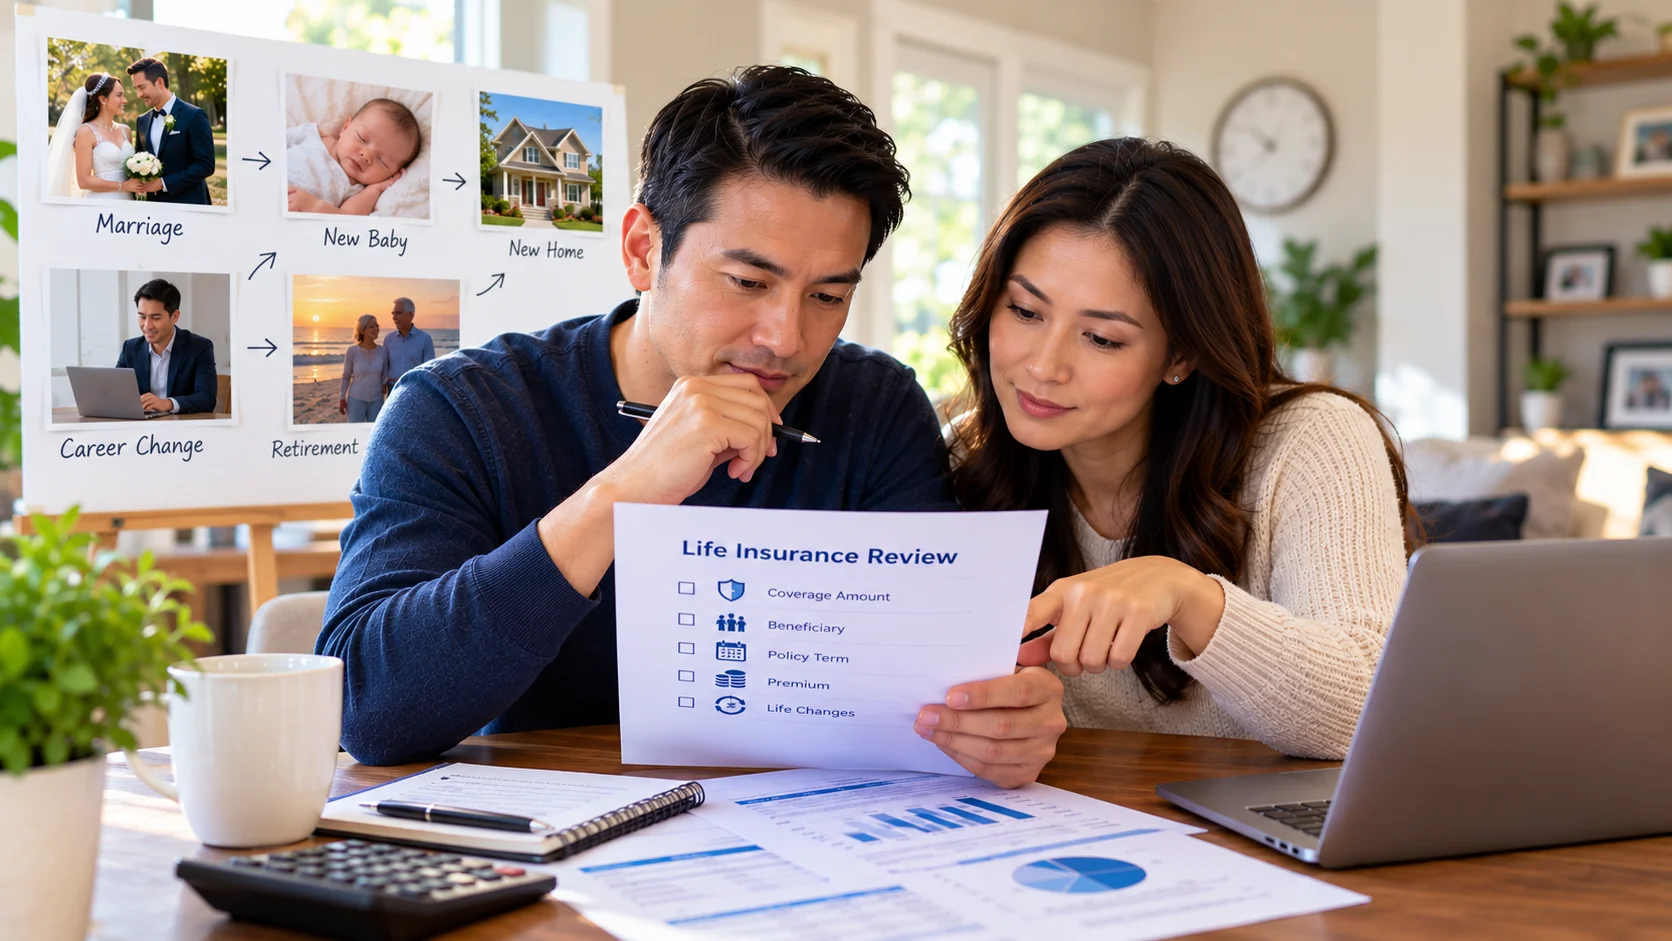
Marriage, children, a new home, career changes, and retirement can all affect your family's life insurance needs. Learn when to review your policy, what to check, and how to keep your protection aligned with your life.
Your Life Changes. Should Your Life Insurance Change Too?
Imagine purchasing a 20-year term life insurance policy when you are 28 years old.
At the time, you are single, renting an apartment, and beginning your career.
You choose a $250,000 policy because it seems sufficient for your circumstances.
Ten years later, your life looks very different.
You are married, have two children, own a home, and have a larger household income.
Your financial responsibilities have changed significantly.
But your life insurance policy still provides the same $250,000 death benefit.
Is that enough?
Possibly. But the only way to understand whether the coverage remains appropriate is to review it against your current financial situation.
Life insurance is not something you should necessarily purchase once and forget about for decades.
As your family, income, debts, and future goals change, your financial protection needs may change too.
A periodic life insurance review can help you understand what you already have, identify potential gaps, and avoid paying for coverage that no longer serves its intended purpose.
1. What Is a Life Insurance Policy Review?
A life insurance policy review is an evaluation of your existing coverage and how it fits your current circumstances.
It involves examining both the policy itself and the financial responsibilities you want it to address.
A typical review may include:
- Your current death benefit.
- The type of life insurance policy.
- The remaining coverage period.
- Premium amounts and payment requirements.
- Beneficiary designations.
- Employer-provided coverage.
- Outstanding financial obligations.
- Household income and dependents.
- Changes in health or financial circumstances.
- Policy riders and other contractual features.
The purpose is not necessarily to purchase additional insurance.
You may discover that your current coverage remains suitable.
You may also find that your family needs more coverage, less coverage, or a different policy structure.
The important goal is to make an informed decision based on your current needs.
2. How Often Should You Review Life Insurance?
An annual review is a useful starting point.
Even when no major life event occurs, reviewing your coverage once a year can help you identify overlooked changes.
For example, you may have:
- Paid down part of your mortgage.
- Received a salary increase.
- Increased your savings.
- Changed employers.
- Added or removed a dependent.
- Approached the end of a term policy.
You do not necessarily need to change your coverage every year.
The review simply provides an opportunity to confirm that your existing protection still makes sense.
In addition to annual reviews, certain life events deserve immediate attention.
3. Getting Married: Combining Financial Responsibilities
Marriage often changes how two people manage their finances.
You and your spouse may begin sharing:
- Housing expenses.
- Mortgage payments.
- Loans.
- Household bills.
- Savings goals.
- Future family plans.
If one spouse dies unexpectedly, the other may face financial obligations that were previously supported by two incomes.
Questions to ask after marriage
- How much does each spouse contribute to household income?
- Would either spouse struggle financially without the other's income?
- Are there shared debts?
- Have you updated your beneficiaries?
- Does each spouse need individual life insurance?
Marriage does not automatically mean both spouses need the same amount of coverage.
The appropriate amounts depend on their respective financial contributions and responsibilities.
It is also important to review any policies purchased before marriage.
Your beneficiary designation may still name a parent, sibling, or another person.
Updating it may be appropriate, depending on your intentions and applicable legal requirements.
4. Having Children: Planning for Long-Term Financial Needs
The arrival of a child is one of the most common reasons families reconsider life insurance.
Children can create financial responsibilities that extend for many years.
These may include:
- Everyday living expenses.
- Childcare.
- Healthcare.
- School-related costs.
- College or vocational education.
- Transportation.
- Housing.
- Other long-term support.
Consider a couple who purchased life insurance before having children.
At that time, their primary concern may have been paying off debts.
After becoming parents, their priorities may include replacing income for 15 or 20 years and supporting future education expenses.
What about a parent who does not earn an income?
A stay-at-home parent may provide substantial unpaid childcare and household services.
If that parent dies, the surviving family may need to pay for childcare, transportation, or other assistance.
The financial value of these responsibilities should not be overlooked.
Life insurance needs are not determined solely by salary.
A policy review should consider the financial impact of losing either parent's contributions.
5. Buying a Home: Reviewing Mortgage Protection
Purchasing a home often introduces a significant long-term financial obligation.
A mortgage may last 15, 20, or 30 years.
If a household relies on two incomes to make mortgage payments, losing one income could create financial pressure.
A life insurance review can help determine whether existing coverage could support the surviving household's housing needs.
Example
Suppose a couple purchases a home with a $350,000 mortgage.
One spouse has $200,000 in life insurance.
The other has $100,000 in employer-provided coverage.
These amounts do not automatically indicate whether the family is underinsured.
The couple must also consider:
- The surviving spouse's income.
- Monthly mortgage payments.
- Savings and other assets.
- Other household expenses.
- Children's needs.
- The remaining mortgage term.
Some families may want enough coverage to pay off the mortgage.
Others may prefer coverage that helps the surviving spouse continue making payments.
Both approaches can be considered.
Avoid counting the mortgage twice
If your income replacement estimate already includes future mortgage payments, adding the entire outstanding mortgage balance separately may overstate your needs.
Use a consistent calculation when evaluating your protection.
6. Changing Jobs: What Happens to Employer Life Insurance?
Many employees receive life insurance through their employer.
Some plans provide basic coverage equal to a fixed amount or a multiple of salary.
Employees may also have supplemental coverage purchased through payroll deductions.
However, employer-sponsored life insurance is often tied to employment eligibility.
When you change jobs, retire, or leave your employer, coverage may change or end.
What to review before leaving a job
Ask your benefits administrator:
- When does my current coverage end?
- Can I continue any of the coverage?
- Is portability available?
- Is conversion to an individual policy available?
- What deadlines apply?
- How much would continued coverage cost?
- Will my new employer provide life insurance?
Portability and conversion options depend on the plan and insurer.
They may involve different premiums and coverage conditions.
The risk of relying entirely on workplace coverage
Suppose an employee has $500,000 in employer-provided life insurance but no individually owned policy.
If the employee leaves the company, that coverage may no longer be available under the same terms.
The family could experience a significant reduction in protection.
This is one reason individually owned life insurance may be worth evaluating alongside workplace benefits.
7. Getting a Promotion or Salary Increase
A promotion or salary increase can improve a family's financial position.
It may also change household spending and long-term commitments.
For example, a family may:
- Purchase a larger home.
- Increase education savings.
- Take on additional financial responsibilities.
- Depend on a higher level of income.
If household expenses increase alongside earnings, existing life insurance may no longer provide the same relative level of support.
However, a salary increase does not automatically mean you need more insurance.
Higher income may also allow you to accumulate additional savings and reduce debt.
A review should consider both the new income and the family's changing financial obligations.
8. Divorce or Separation: Reviewing Beneficiaries and Coverage
Divorce can significantly affect life insurance planning.
A policy purchased during marriage may name a former spouse as beneficiary.
Financial responsibilities may also change because of:
- Child support.
- Spousal support.
- Property settlements.
- Shared debts.
- Court orders.
- New household expenses.
Life insurance provisions may be included in divorce agreements or court orders.
These requirements can affect policy ownership, beneficiary designations, and the amount of coverage that must be maintained.
Important consideration
Do not assume that divorce automatically removes a former spouse as beneficiary.
The result can depend on state law, the policy, the type of benefit plan, and applicable legal documents.
Employer-sponsored plans may be subject to federal rules that affect beneficiary rights.
Review your policies and obtain appropriate legal guidance before making changes that could conflict with an agreement or court order.
9. Starting a Business or Becoming Self-Employed
Leaving traditional employment to start a business can change your insurance situation.
You may lose employer-provided life insurance.
Your household income may become less predictable.
You may also take on business loans or other financial commitments.
Business owners sometimes consider life insurance for personal family protection as well as specific business needs.
However, personal and business insurance arrangements can have different purposes and ownership structures.
A review should distinguish between:
- Insurance intended to support your family.
- Insurance intended to address business obligations.
- Coverage associated with business ownership or succession arrangements.
Complex business insurance needs may require professional financial, insurance, and legal guidance.
10. Changes in Health: Should You Replace Your Policy?
Health changes can affect life insurance eligibility and pricing.
For example, an applicant who develops a medical condition after purchasing an individual term policy may face different underwriting outcomes when applying for new coverage.
But an existing level-term policy generally continues according to its contract as long as required premiums are paid.
A change in health does not ordinarily cause the insurer to reprice an already-issued guaranteed level-premium term policy during its level-premium period.
Why keeping an existing policy may matter
Suppose someone purchased a term policy while healthy.
Years later, the person develops a medical condition.
Replacing the original policy could mean applying for coverage at an older age and with a different health profile.
The new policy might cost more, offer less favorable terms, or be unavailable.
Do not cancel an existing life insurance policy simply because a new option appears attractive.
Understand the consequences and ensure any replacement coverage is approved and in force before considering cancellation.
Some replacements can also restart certain policy periods or create other disadvantages.
11. Approaching the End of Your Term Life Insurance Policy
Term life insurance generally provides coverage for a specified period.
For example, a 20-year level-term policy may have scheduled level premiums for its initial 20-year period.
As the end of that period approaches, you should review your options.
Depending on the policy, you may be able to:
- Allow the coverage to expire.
- Continue coverage at a higher renewal premium.
- Exercise a conversion option before its deadline.
- Apply for a new life insurance policy.
Not every policy offers the same options.
Why review before expiration?
Waiting until a policy is about to expire can limit your choices.
Your age and health may have changed since the original policy was issued.
Some conversion rights also expire before the end of the full coverage period.
Review the policy's renewal and conversion provisions well in advance.
Example
A parent purchases a 20-year term policy at age 35.
At age 53, the parent has two years remaining in the initial term.
The family should consider whether significant financial responsibilities will continue after age 55.
If the mortgage is nearly paid off and the children are financially independent, the need for coverage may be lower.
If the family still relies heavily on that person's income, additional protection may deserve consideration.
12. Approaching Retirement: Do You Still Need Life Insurance?
Retirement can change the purpose of life insurance.
During working years, many families use life insurance primarily to replace lost earnings.
After retirement, the household may rely more on savings, pensions, Social Security, and other retirement income.
Some financial obligations may also have declined.
For example:
- The mortgage may be paid off.
- Children may be financially independent.
- Retirement savings may have grown.
- Household expenses may have changed.
These changes can reduce the need for income replacement coverage.
However, some retirees still have reasons to maintain life insurance.
These may include support for a dependent, estate-planning objectives, or other long-term financial commitments.
Review affordability carefully
Continuing insurance premiums into retirement can affect household cash flow.
A review should consider whether the benefits of maintaining coverage justify the ongoing cost.
Do not cancel permanent insurance without understanding its cash value, surrender charges, tax implications, and other policy provisions.
13. What Should You Check During a Life Insurance Review?
A useful review goes beyond checking the death benefit.
Consider the following areas.
Coverage amount
Does the current death benefit align with your estimated financial responsibilities?
Policy type
Do you have term life, whole life, universal life, or another type of coverage?
Policy expiration
If you own term insurance, when does the initial level-term period end?
Premiums
How much are you paying, and are future premiums scheduled to change?
Beneficiaries
Are your primary and contingent beneficiaries current?
Employer coverage
How much coverage do you receive through work, and what happens when employment ends?
Riders and additional features
Does the policy include features such as waiver of premium, accelerated death benefits, or other riders?
What conditions apply?
Policy status
Is the policy active and in good standing?
Insurance company
Do you have current contact information for the issuing insurer?
Policy documents
Can your beneficiaries locate the necessary information if they need to make a claim?
Reviewing these details can reveal issues that might otherwise go unnoticed.
14. Example: How a Family's Life Insurance Needs Change Over Time
Consider a hypothetical family at three different life stages.
| Life stage | Financial responsibilities | Possible review focus |
|---|---|---|
| Age 30 | Newly married, renting, building savings | Income replacement and shared debts |
| Age 40 | Two children, mortgage, higher household expenses | Childcare, education, mortgage, income protection |
| Age 60 | Children independent, mortgage reduced, approaching retirement | Remaining dependents, retirement resources, ongoing premiums |
This is an illustration, not a universal life insurance recommendation.
Different families can have very different needs at the same age.
For example, a 60-year-old supporting a dependent family member may need more protection than a 40-year-old with substantial financial assets and limited obligations.
Life insurance needs depend on circumstances, not age alone.
15. Can You Have Too Much Life Insurance?
A family's existing coverage can exceed its estimated financial needs.
That does not automatically mean the coverage should be reduced.
Some families intentionally maintain additional protection to account for uncertainty or specific long-term goals.
However, premiums should remain affordable.
Money used for insurance premiums is money that cannot be used simultaneously for other goals such as:
- Emergency savings.
- Retirement contributions.
- Debt repayment.
- Education savings.
- Everyday household expenses.
A review can help determine whether the coverage still serves a meaningful purpose.
The goal is balanced financial protection rather than maximizing insurance coverage at any cost.
16. Should You Cancel an Old Policy and Buy a New One?
Not necessarily.
Replacing life insurance can have consequences.
A new policy may require underwriting based on your current age and health.
Premiums may be higher.
Some policy features may be lost.
For certain permanent policies, replacement may involve surrender charges, tax considerations, or loss of accumulated benefits.
Before replacing coverage:
- Understand why you want to make the change.
- Compare the existing and proposed policies.
- Review premiums and guarantees.
- Check surrender charges and other costs.
- Review conversion and renewal options.
- Confirm the new policy has been approved and is in force before canceling the old policy.
- Consider obtaining guidance from a qualified, licensed insurance professional.
A lower advertised premium does not necessarily mean a new policy is better.
17. How Turtelle Helps You Review Your Life Insurance
Life insurance information can become scattered over time.
You may have one policy purchased years ago, another through your employer, and supplemental coverage added during an enrollment period.
Turtelle Insurance helps families bring these considerations into a clearer protection assessment.
Family Protection Check
Turtelle's Family Protection Check helps users estimate financial protection needs based on the information they provide.
It considers existing coverage and relevant financial responsibilities to help identify potential gaps.
Family Protection Score
The proprietary, rule-based Family Protection Score communicates the assessment results in an understandable format.
The score is not AI-generated.
It is an educational estimate, not a guarantee of financial security or a recommendation to purchase a particular policy.
Policy X-Ray
Turtelle's Policy X-Ray is designed to help users review information about an existing life insurance policy and consider how that coverage relates to estimated family protection needs.
It does not replace the official insurance contract or independently verify whether a claim would be paid.
Where available, eligible users may explore additional insurance options through Turtelle.
Actual eligibility, premiums, and coverage decisions depend on the issuing insurer and applicable requirements.
18. Your Annual Life Insurance Review Checklist
Use this checklist when reviewing your coverage.
- [ ] Confirm all existing life insurance policies.
- [ ] Verify current death benefit amounts.
- [ ] Check employer-provided life insurance.
- [ ] Review policy expiration and renewal dates.
- [ ] Confirm primary and contingent beneficiaries.
- [ ] Review mortgage and other major debts.
- [ ] Consider changes in household income.
- [ ] Update childcare and education estimates.
- [ ] Review savings and other available resources.
- [ ] Check whether premiums remain affordable.
- [ ] Understand conversion or continuation options.
- [ ] Store policy information securely.
- [ ] Make sure the appropriate person knows where policy documents can be found.
Completing this review does not mean you must purchase new insurance.
It simply helps you understand whether your existing coverage still supports your family's financial needs.
Final Thoughts
Life insurance needs can change as your life changes.
Marriage, children, homeownership, job transitions, health changes, and retirement can all affect the financial responsibilities your coverage is intended to address.
An annual review, along with additional reviews after major life events, can help you identify potential protection gaps and keep beneficiary and policy information current.
It can also help you avoid unnecessary policy changes.
The purpose of a life insurance review is not to buy more insurance every year. It is to understand whether the protection you already have still fits the life you are living today.
Taking time to review your coverage can help you make more informed decisions for your family's financial future.
Check My Family Protection Score
The free Family Protection Check™ shows how your workplace coverage, personal policies and family needs fit together, and whether there may be a gap.
Check My Family Protection ScoreFrequently asked questions
How often should I review my life insurance policy?
Reviewing your life insurance annually is a useful practice. You should also consider reviewing it after major life events, including marriage, divorce, having children, buying a home, changing jobs, or approaching retirement.
Should I increase my life insurance after having a child?
Possibly. A child can create additional financial responsibilities, including childcare, education, and long-term household support. Review your existing coverage and available resources before deciding whether additional insurance is needed.
Does my life insurance premium increase as I get older?
For many level-term policies, the scheduled premium remains unchanged during the initial level-premium period. However, premiums may increase substantially after that period ends. New policies are generally priced using your age and underwriting information when you apply.
Should I cancel my life insurance when I retire?
Not automatically. Retirement may reduce income replacement needs, but other responsibilities may remain. Review your savings, dependents, ongoing premiums, policy features, and financial goals before canceling coverage.
Can I change the beneficiary on my life insurance policy?
Many policies allow the owner to change a revocable beneficiary. However, irrevocable beneficiary arrangements, court orders, certain employer-plan rules, or other legal restrictions may limit changes. Confirm the requirements with your insurer or plan administrator.