EMPLOYEE BENEFITS · LIFE INSURANCE
Is Your Employer-Provided Life Insurance Enough?
Your workplace may offer life insurance, but understanding its limits could make a meaningful difference for your family's financial future.
You Have Life Insurance at Work. But Is It Enough?
Imagine starting a new job and receiving a benefits package that includes medical insurance, dental coverage, retirement contributions, and life insurance.
You review the options, make your selections, and notice something reassuring:
Your employer provides life insurance at no additional cost to you.
It feels like one less financial responsibility to worry about.
But several years later, your circumstances may look very different. You might have purchased a home, welcomed children, or become the primary income earner for your household.
The life insurance benefit you received when you joined the company may not have changed at all.
That raises an important question: If your family had to rely on that benefit tomorrow, how much financial protection would it actually provide?
Employer-provided life insurance is a meaningful benefit. But having life insurance and having enough life insurance are not necessarily the same thing.
Understanding the difference can help you make more informed decisions about your family's financial future.
1. What Is Employer-Provided Life Insurance?
Employer-provided life insurance is coverage offered through a workplace benefits program.
It is commonly arranged as group life insurance, meaning the employer sponsors or facilitates coverage for eligible employees under a group policy or plan.
The employer may pay the entire cost of basic coverage, share the cost with employees, or offer additional coverage that employees can purchase.
Two common forms are basic group life insurance and supplemental or voluntary life insurance.
Basic group life insurance
Basic group life insurance is often included in an employee benefits package.
Depending on the plan, coverage might be:
- A fixed amount, such as $25,000 or $50,000.
- An amount equal to one year's base salary.
- A multiple of salary, such as two times annual earnings.
- Another amount defined by the employer's benefit plan.
Not every employer offers life insurance, and there is no universal benefit amount.
Eligibility, coverage levels, premium arrangements, and exclusions depend on the plan.
Supplemental or voluntary life insurance
Some employers allow employees to purchase additional life insurance through payroll deductions.
This may provide a way to increase coverage beyond the employer-paid amount.
However, larger coverage amounts may require evidence of insurability or medical underwriting, depending on the plan and enrollment circumstances.
Supplemental coverage can also have its own age-based reductions, premium changes, portability rules, and termination conditions.
The first step is to identify exactly which workplace life insurance benefits you have—not simply whether your benefits portal says "Life Insurance."
2. Why Employer Life Insurance May Not Be Enough
Workplace life insurance is often designed as a baseline benefit rather than a complete financial protection plan tailored to every employee.
Consider two employees at the same company.
One is single, has limited debt, and has no financial dependents.
The other is married, has two young children, a mortgage, and a spouse who works part-time.
Both employees might receive the same $100,000 life insurance benefit.
Yet their financial responsibilities are substantially different.
For the second employee, the benefit may need to help support the family through years of mortgage payments, childcare, household expenses, and education costs.
A single benefit amount cannot automatically account for all those differences.
That does not make workplace life insurance inadequate for everyone. It means the benefit should be evaluated against the needs of the particular household.
3. How Much Coverage Does Your Employer Actually Provide?
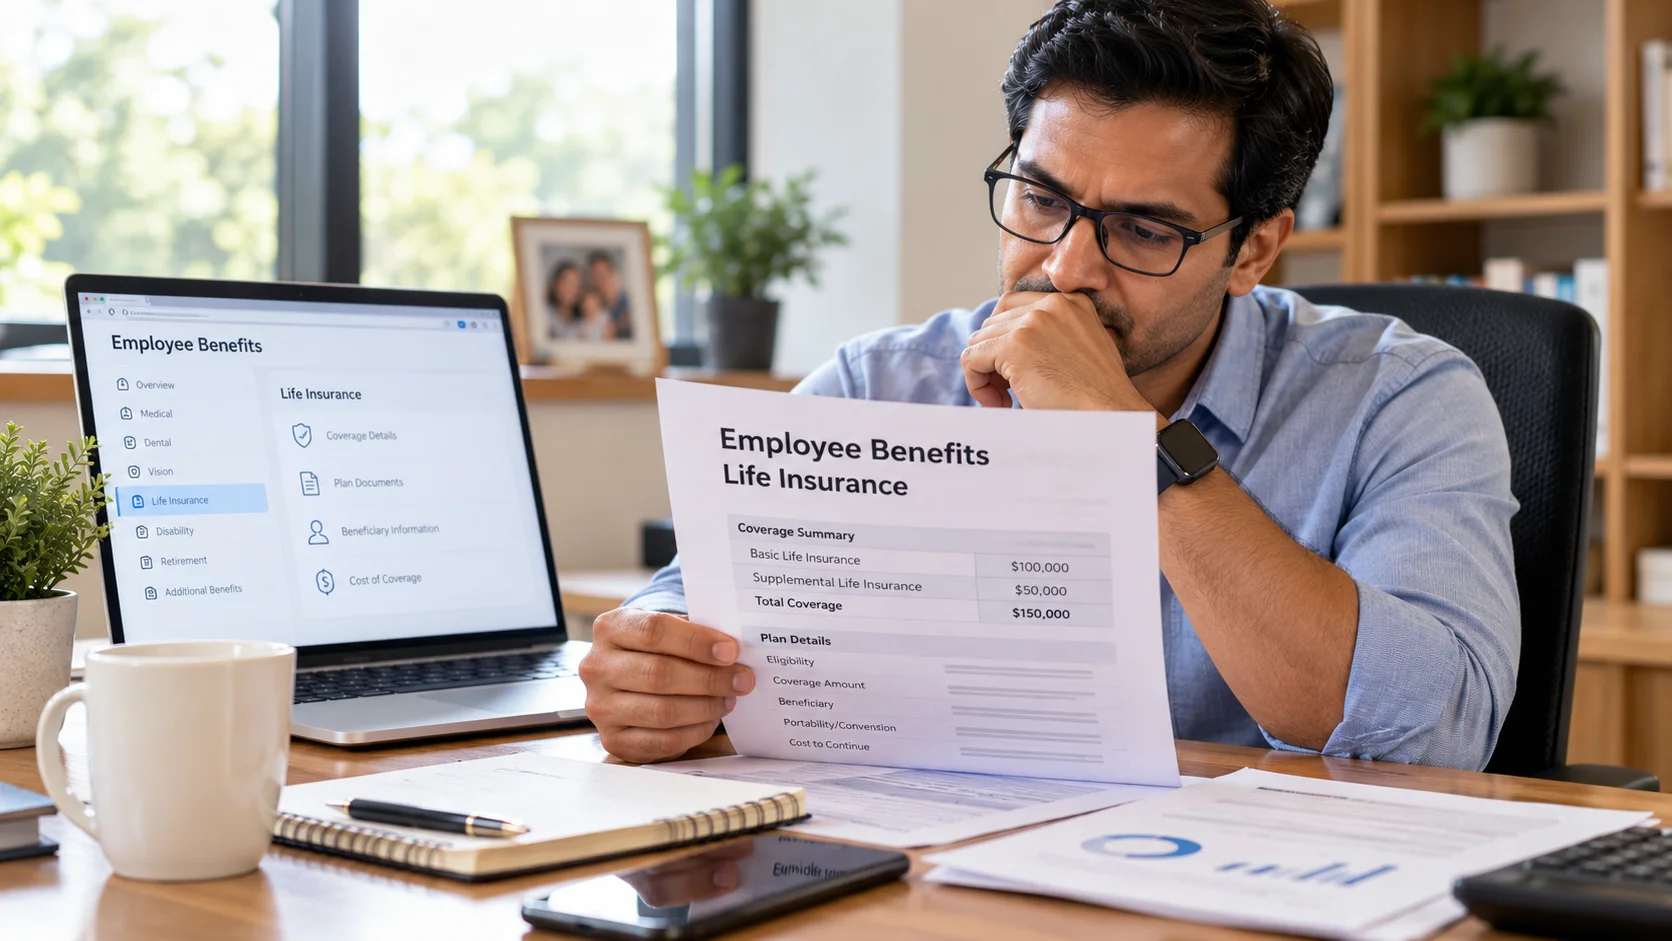
Before deciding whether you need additional protection, determine your existing benefit amount.
Start by checking your employer's benefits portal, enrollment confirmation, or summary plan description.
Look for the section labeled Basic Life, Group Term Life, Supplemental Life, or Voluntary Life.
For example, suppose your annual salary is $90,000.
Your employer's plan provides basic life insurance equal to one year's salary.
Your basic death benefit would generally be $90,000, subject to the plan's calculation rules, coverage limits, and eligibility conditions.
If you also purchased $150,000 of supplemental coverage, your combined workplace coverage might be $240,000.
But you should confirm both amounts are active and understand whether any reductions, exclusions, or other limitations apply.
Five questions to ask your HR or benefits team
- What is my current basic life insurance benefit?
- Do I have supplemental or voluntary coverage?
- Does coverage decrease at certain ages or under other plan conditions?
- What happens to coverage if I leave the company or become ineligible?
- Who are my designated beneficiaries?
These questions can reveal important details that are easy to overlook during annual benefits enrollment.
4. A Family Example: When $100,000 May Not Be Enough
Consider a hypothetical household in which one parent earns $100,000 per year.
The family has two children, a mortgage, and ongoing living expenses.
The employer provides basic group life insurance equal to one year's salary.
The employee has no additional individual life insurance.
Here is a simplified illustration of the family's potential financial needs:
| Financial need | Illustrative amount |
|---|---|
| Income support: $55,000 per year for 12 years | $660,000 |
| Children's future education | $100,000 |
| Immediate and final expenses | $25,000 |
| Estimated financial needs | $785,000 |
| Employer-provided life insurance | −$100,000 |
| Available savings designated for family support | −$35,000 |
| Illustrative remaining gap | $650,000 |
In this example, ongoing mortgage payments and ordinary household expenses are already included in the annual income-support estimate. The mortgage balance is therefore not added separately.
The calculation is intentionally simplified. It does not adjust future expenses for inflation, discount future cash needs to present value, or model investment returns.
The actual amount of coverage needed could be higher or lower.
Nevertheless, the example illustrates an important point:
A workplace life insurance benefit can be valuable while still covering only a portion of a family's estimated financial responsibilities.
The goal is not to assume that everyone needs $650,000 of additional coverage. It is to identify whether the resources available to your own family align with its needs.
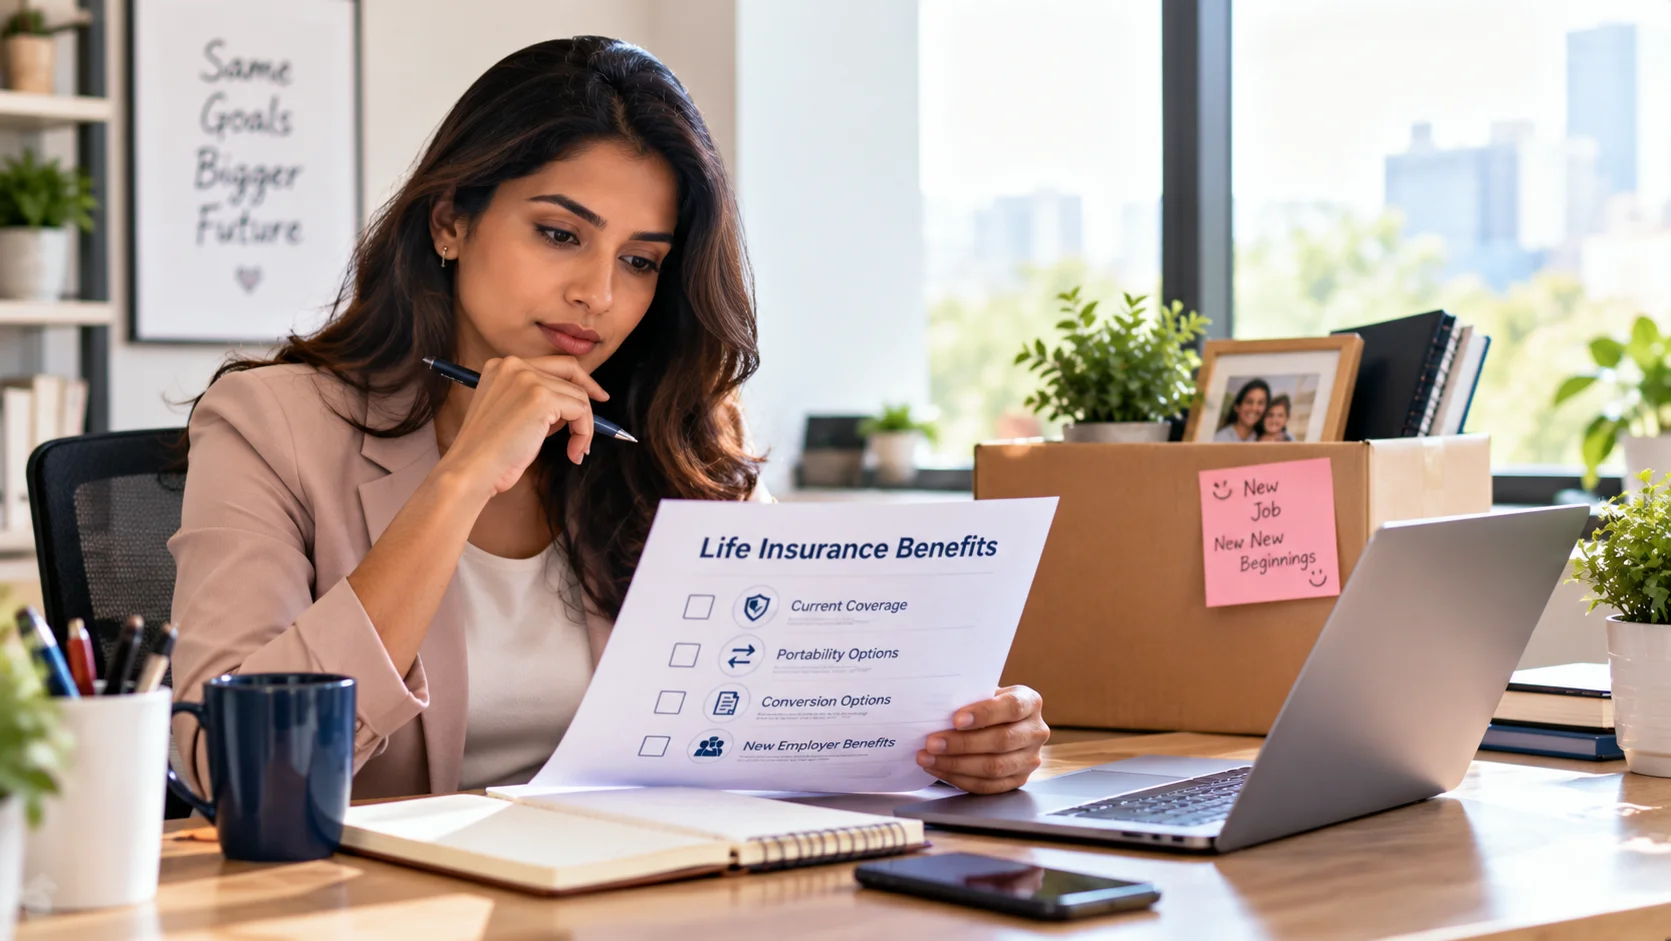
5. What Happens to Your Life Insurance When You Change Jobs?
This is one of the most important differences between many employer-sponsored policies and individually owned life insurance.
Workplace coverage is generally connected to your eligibility under the employer's benefit plan.
When you leave your job, retire, reduce your working hours, or otherwise lose eligibility, the coverage may end or change.
The exact result depends on the plan and the circumstances.
Can you keep your workplace life insurance?
Some group life insurance plans offer portability or conversion options.
These terms are related but not identical.
Portability may allow an eligible employee to continue certain group coverage after leaving the employer, subject to the plan's rules, available benefit amounts, and premium requirements.
Conversion may allow an eligible employee to replace group coverage with an individual policy, often without new evidence of insurability, subject to the insurer's rules and deadlines.
The converted policy may have different premiums and features from the original group coverage.
Neither option is universally available, and the cost may be significantly different from the amount previously paid through payroll.
Deadlines can be short, so it is important to review the relevant notices promptly when employment changes.
What if you start a new job?
A new employer may offer life insurance, but you should not assume it will provide the same amount or begin on the same date.
Eligibility waiting periods, coverage limits, and enrollment requirements may differ.
There could also be a period between jobs when you have no employer-provided coverage.
If your family relies entirely on workplace insurance, these transitions deserve special attention.
6. Employer Life Insurance vs. Individual Term Life Insurance
Employer-sponsored life insurance and individual term life insurance can serve complementary purposes.
They are not necessarily competing choices.
| Feature | Employer-provided group life | Individual term life |
|---|---|---|
| Who arranges coverage? | Employer or benefits plan | Individual policyholder |
| Coverage amount | Based on plan options and limits | Based on application, underwriting, and insurer limits |
| Premiums | Employer-paid, employee-paid, or shared | Generally paid by the policyholder |
| Medical underwriting | May be simplified or waived for certain amounts | Usually subject to underwriting |
| Connection to employment | Often depends on employment or plan eligibility | Generally independent of employer |
| Coverage duration | Depends on plan and eligibility | Specified policy term, if kept in force |
| Portability | May be available under plan rules | Not generally affected by changing jobs |
Why some families use both
A family may choose to retain its employer-provided basic life insurance while purchasing an individual term policy for additional protection.
For example, an employee might have $100,000 in employer-paid coverage and a separate $500,000 individual term policy.
If both policies are in force and a covered death occurs, their benefits may collectively provide more financial support than either policy alone.
However, all policy conditions must be satisfied, and individual coverage is subject to insurer approval.
This approach may also reduce reliance on a single employer's benefits program.
7. Is Supplemental Life Insurance Through Work a Good Option?
Supplemental workplace life insurance can be worth evaluating, especially when your employer offers convenient enrollment or access to coverage with simplified underwriting.
However, convenience should not be the only consideration.
Before selecting supplemental coverage, compare:
Premiums: How much does the coverage cost now, and can premiums increase with age or changes in the plan?
Coverage limits: Is the maximum benefit enough to address your family's estimated needs?
Underwriting requirements: Can you enroll without medical evidence, or does your requested amount require approval?
Portability and conversion: What happens if you leave the company?
Policy features: Are there exclusions, age-related reductions, or other conditions you should understand?
Individual alternatives: Would a separately owned policy provide a more suitable combination of coverage duration, cost, and flexibility?
There is no universal winner.
For some employees, supplemental group coverage may be attractive. For others, individual term coverage may better align with their long-term goals.
8. Does Your Spouse or Partner Need Separate Coverage?
When reviewing workplace benefits, it is easy to focus only on the employee whose salary supports the household.
But a spouse or partner may also make important financial contributions.
If both partners earn income, the household may depend on both salaries to maintain its standard of living.
If one partner primarily provides childcare or household support, replacing those responsibilities could create significant expenses.
Some employers offer dependent or spouse life insurance, but benefit amounts and eligibility requirements vary.
A thoughtful household review should consider both partners' contributions, not just the primary employee's salary.
The appropriate coverage for each person may be different.
9. What Happens if You Become Disabled or Cannot Work?
Life insurance and disability insurance address different financial risks.
Life insurance generally provides a death benefit when the insured person dies and the policy conditions are met.
Disability insurance may replace a portion of income when an insured person cannot work because of a covered illness or injury, subject to the policy's definition of disability and other terms.
Some life insurance policies include optional riders, but those features should not be assumed.
When reviewing employer benefits, it can be helpful to understand both life insurance and disability coverage.
A household may have substantial life insurance while remaining financially vulnerable to a prolonged period of lost income during the insured person's lifetime.
A complete benefits review considers the different events that could affect the household—not only the amount of the death benefit.
10. When Should You Review Your Workplace Life Insurance?
Many employees review their benefits only during annual open enrollment.
That is a useful opportunity, but certain life events may justify a review sooner.
Consider reassessing coverage when you:
- Start a new job or leave an employer.
- Get married or enter a long-term partnership.
- Have or adopt a child.
- Buy a home.
- Receive a major salary increase.
- Change from full-time to part-time employment.
- Take on significant financial responsibilities.
- Approach retirement.
- Experience changes in your spouse's employment or benefits.
Also review your beneficiary designations.
A beneficiary is the person or entity designated to receive the policy's death benefit, subject to applicable law and policy terms.
Outdated beneficiary information can create complications, particularly after major family changes.
Some life events may create special enrollment opportunities, but you should verify the deadlines and rules under your specific plan.
11. How to Identify a Potential Life Insurance Coverage Gap
You do not need to begin with an insurance application.
Start by gathering information about your household.
Step 1: Understand your current protection
Record the death benefit amounts from all active life insurance policies, including basic employer coverage, supplemental coverage, and individually owned policies.
Step 2: Estimate your family's financial needs
Consider income replacement, housing expenses, dependents, education goals, immediate expenses, and other obligations.
Avoid counting the same expense twice.
Step 3: Identify available resources
Review savings and other resources that could realistically help support your household.
Consider which assets should remain reserved for retirement or other essential purposes.
Step 4: Compare the two
If estimated needs exceed available resources, the difference may indicate a potential coverage gap.
This is an educational estimate, not a guarantee of an appropriate insurance amount or underwriting approval.
Step 5: Review your options
Depending on your circumstances, options might include increasing workplace coverage, purchasing an individual policy, maintaining existing coverage, or adjusting your financial plan.
Premium affordability, health, policy features, and coverage duration should all be considered before making a decision.
12. How Turtelle Helps Families Understand Their Protection
Employee benefits can be difficult to evaluate because information is often spread across different documents and insurance policies.
You may have basic life insurance through work, supplemental coverage selected during enrollment, and a separate individual policy purchased years earlier.
Understanding how those pieces fit together can be challenging.
Turtelle Insurance's Family Protection Check helps families review their financial protection circumstances and explore potential coverage gaps.
The assessment can provide a starting point for understanding how workplace coverage, personal policies, and family responsibilities relate to one another.
Turtelle's proprietary Family Protection Score is designed to help make the results easier to understand.
The Protection Check is an educational tool. It does not replace individualized professional advice, guarantee eligibility for insurance, or determine the terms of a policy.
The purpose is to help families make more informed decisions about their protection.
Final Thoughts
Employer-provided life insurance is a benefit worth understanding and appreciating.
It may offer meaningful financial support, often with convenient enrollment and favorable arrangements for basic coverage.
But the amount your employer provides may not reflect your family's actual needs.
A benefit equal to one year's salary might be sufficient for one employee and leave a substantial gap for another.
The most important questions are straightforward:
How much coverage do you have? How long can you rely on it? And how does it compare with the financial responsibilities your family would face without you?
Review your workplace benefits, consider your individual circumstances, and revisit the numbers as your life changes.
Your employer may provide a foundation for life insurance protection. Understanding whether that foundation is enough is your next step.
Check My Family Protection Score
The free Family Protection Check™ shows how your workplace coverage, personal policies and family needs fit together, and whether there may be a gap.
Check My Family Protection ScoreFrequently asked questions
Is life insurance provided by my employer enough?
It depends on your household's financial responsibilities and existing resources. Workplace coverage may provide a useful foundation, but the benefit amount might not cover long-term income replacement, housing, childcare, and other needs.
What happens to my employer life insurance if I quit my job?
Coverage often ends or changes when employment or plan eligibility ends. Some plans offer portability or conversion options, subject to deadlines, costs, and eligibility requirements.
Can I have employer life insurance and individual life insurance?
Yes. You can generally maintain both types of coverage, subject to the terms of each policy. An individual policy may provide protection that is independent of your employer.
Is supplemental life insurance through work worth buying?
It may be, depending on premiums, coverage limits, underwriting requirements, and what happens when you leave your employer. Compare the options against your needs and available individual coverage.
How do I find out how much life insurance my employer provides?
Review your benefits portal, enrollment confirmation, certificate of insurance, or summary plan description. Your HR or benefits team can also explain the benefit amount and applicable conditions.