EMPLOYEE BENEFITS · LIFE INSURANCE
What Happens to Your Life Insurance When You Change Jobs?
Changing jobs can affect more than your paycheck. Learn what happens to workplace life insurance, how portability and conversion work, and how to avoid unexpected protection gaps.
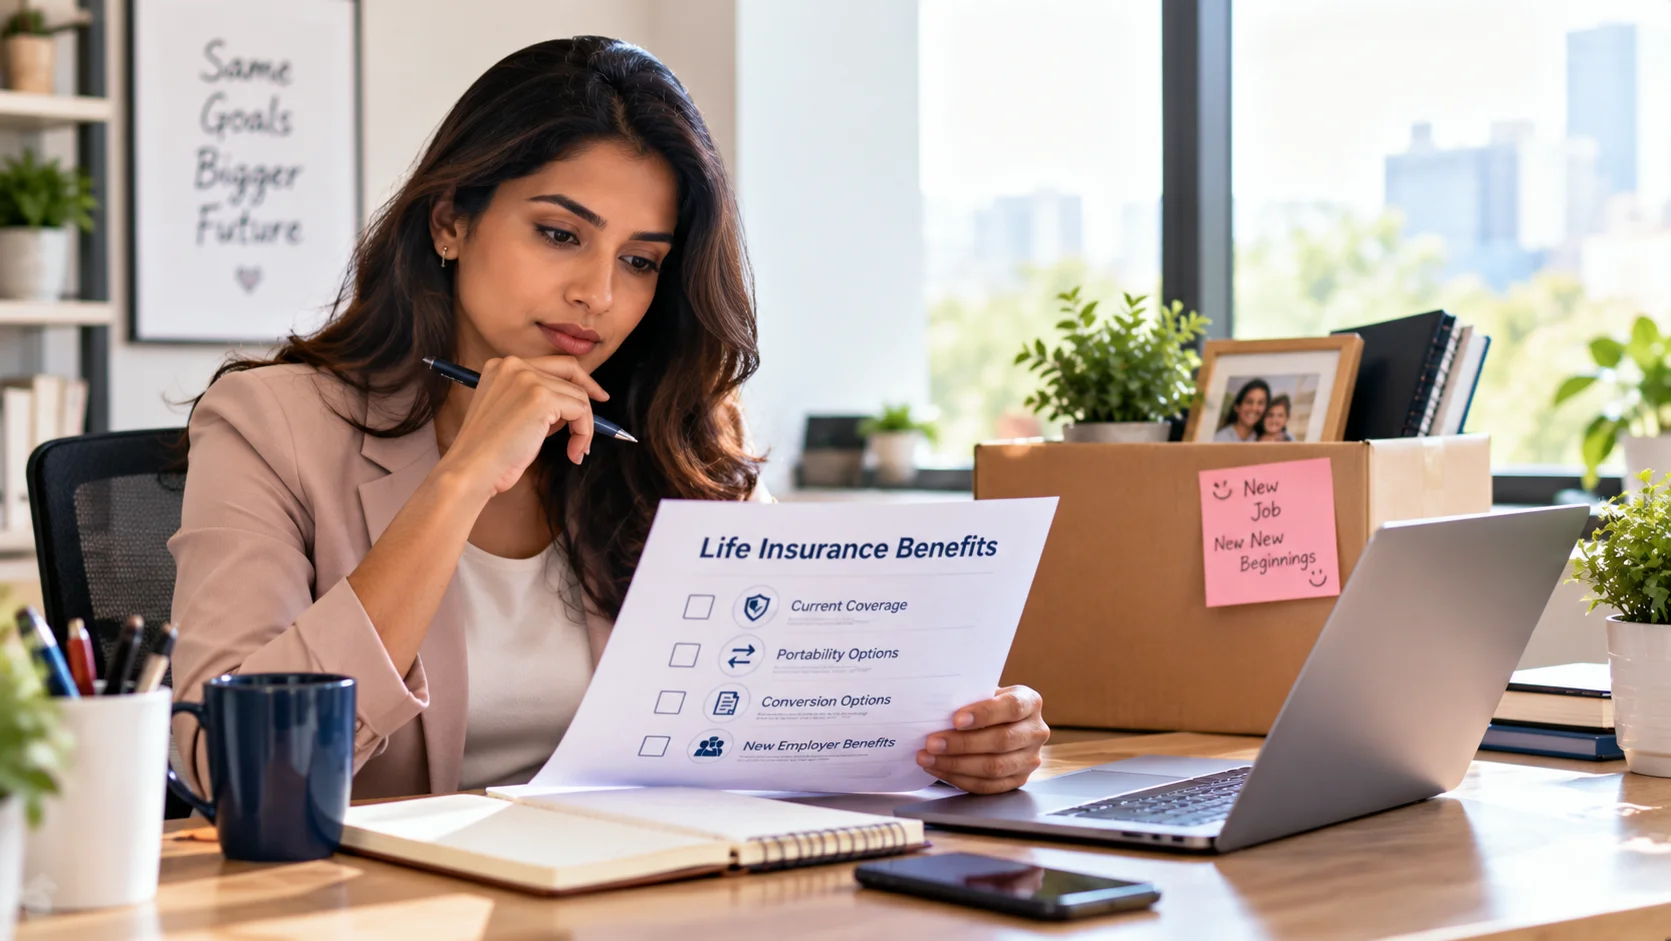
A New Job Can Change More Than Your Paycheck
Imagine receiving an exciting job offer.
The new position comes with a better salary, new responsibilities, and opportunities for career growth.
You compare health insurance options, retirement contributions, vacation benefits, and the expected start date.
Everything looks promising.
But there is one benefit you may not think about until after you resign:
What happens to the life insurance your current employer provides?
For many employees, workplace life insurance is included in their benefits package. Some employers pay for basic coverage, while employees may purchase additional protection through payroll deductions.
Over time, it is easy to assume that this coverage will always be there.
However, employer-sponsored life insurance is often connected to employment or eligibility under a specific benefits plan.
When you leave your job, your coverage may end, change, or become available for continuation under different terms.
If you have a spouse, children, mortgage, or other financial dependents, understanding those changes is important.
A job transition should not automatically become a gap in your family's financial protection.
1. Does Employer-Provided Life Insurance End When You Leave Your Job?
In many cases, yes.
Employer-provided group life insurance generally depends on your eligibility under the employer's plan.
When employment ends, the employer-paid coverage often ends as well.
However, there is no universal rule that applies to every employer or insurer.
The actual termination date may depend on the plan's provisions, your employment status, and the reason coverage is ending.
For example, a plan might end coverage on your last day of active employment, at the end of the month, or according to another eligibility rule.
Some plans also provide a limited continuation period or other rights.
Do not assume that life insurance remains active through the end of the month or until your next job begins.
Review your certificate of insurance, summary plan description, or other governing plan documents to determine the actual termination date.
Your HR or benefits team can help identify the applicable provisions.
2. What Happens to Basic and Supplemental Life Insurance?
Many employees have more than one type of workplace life insurance.
Understanding each benefit separately can help prevent surprises.
Basic employer-paid life insurance
Basic group life insurance is often provided as part of an employee benefits package.
The employer may pay the full premium, and coverage may be based on a fixed amount or a multiple of salary.
For example, an employee earning $90,000 annually might have a basic life insurance benefit equal to one year's salary.
That represents a $90,000 death benefit, subject to the plan's terms.
When employment ends, this basic coverage may terminate unless a continuation option applies.
Supplemental or voluntary life insurance
Supplemental life insurance allows eligible employees to purchase additional coverage, often through payroll deductions.
An employee might have $90,000 in basic coverage and another $200,000 in supplemental coverage.
Together, those benefits could represent $290,000 of workplace protection.
But supplemental coverage does not necessarily continue automatically after employment ends.
Even though the employee paid the premiums, the policy may still be part of the employer's group plan.
Paying for supplemental coverage through payroll does not automatically mean you own a policy that remains active after leaving your employer.
The plan may provide portability or conversion options, but the employee generally must follow the applicable procedures.
3. What Is Life Insurance Portability?
Portability is a feature offered by some group life insurance plans that allows eligible employees to continue certain coverage after leaving the employer.
Instead of purchasing a completely new policy through traditional individual underwriting, the employee may be able to continue coverage under an arrangement made available by the insurer.
Portability can be useful when someone wants to maintain existing protection during a job transition.
However, the specific terms vary.
A portability option may have:
- Eligibility requirements.
- Minimum or maximum coverage amounts.
- Age restrictions.
- Premium changes.
- Application deadlines.
- Restrictions based on the reason coverage ended.
- Different continuation provisions.
Portability may not be available for every type of coverage or every employee.
Does portable life insurance cost the same?
Not necessarily.
Your employer may have been paying all or part of the premium.
After leaving the company, you may become responsible for the entire cost.
The insurer may also apply different rates under the portability arrangement.
Before choosing portability, request the actual premium and continuation terms.
The convenience of continuing coverage should be weighed against affordability and the duration of protection needed.
4. What Is Life Insurance Conversion?
Conversion is another option that may be available when group life insurance ends.
A conversion provision generally allows an eligible employee to obtain an individual life insurance policy from the insurer under specified conditions.
Depending on the plan and insurer, conversion may be available without new evidence of insurability.
This can be especially important if a person's health has changed since their original workplace enrollment.
However, conversion is not the same as keeping the original group policy unchanged.
The individual policy may have different premiums, benefits, and features.
In many arrangements, the available conversion product is a form of permanent life insurance rather than a new level-term policy.
That may make the premiums considerably higher than the employee previously paid.
Why conversion deadlines matter
Conversion rights generally must be exercised within a specified period.
Some plans use a 31-day application window, but this is not a universal deadline.
Other rules may apply depending on the policy, state law, and reason for termination.
Employees should request their conversion notice and review the actual deadline rather than relying on a general rule.
Missing a conversion deadline can mean losing the opportunity to obtain coverage under that particular conversion provision.
If you are leaving a job, ask about conversion before your coverage terminates.
5. Portability vs. Conversion: What's the Difference?
Although both options may allow life insurance protection to continue after employment ends, they work differently.
| Feature | Portability | Conversion |
|---|---|---|
| Main purpose | Continue eligible group coverage | Obtain an individual policy |
| Availability | Only when offered by the plan | Only when provided by the plan or applicable law |
| Coverage structure | Generally a continuation arrangement under group coverage | Individual insurance contract |
| Underwriting | Depends on plan provisions | Often available without new evidence of insurability for eligible amounts |
| Premiums | May change after leaving employment | Based on the converted policy and applicable rates |
| Deadlines | Plan-specific | Plan- and law-specific |
| Coverage options | Subject to portability rules | Subject to available conversion products |
Neither option is automatically better.
The appropriate choice depends on the coverage available, cost, eligibility, and how long protection is needed.
Some employees may have access to both options.
Others may have only one or neither.
Your plan documents and insurer determine what is actually available.
6. Can You Keep Your Life Insurance When You Retire?
Retirement is another situation in which workplace life insurance may change.
Some employers offer retiree life insurance benefits, but many do not.
Even when retiree coverage is available, the death benefit may be lower than the amount provided during active employment.
For example, an employee could have a benefit equal to two times salary while working but a smaller fixed amount after retirement.
The reduction may be significant.
Some plans also reduce coverage at specified ages.
Employees approaching retirement should ask whether coverage continues, what benefit amount applies, whether premiums change, and whether portability or conversion options are available.
Retirement planning should account for the possibility that employer-sponsored life insurance will decrease or end.
7. What Happens During the Gap Between Two Jobs?
Suppose an employee leaves Company A on June 30 and starts working at Company B on July 15.
The employee might assume that the new company's benefits will begin immediately.
But the new employer could have an eligibility waiting period or a different coverage effective date.
The employee could therefore experience a period without employer-provided life insurance.
Consider this hypothetical timeline:
| Event | Illustrative date |
|---|---|
| Last working day at Company A | June 30 |
| Company A life insurance ends | June 30 |
| First day at Company B | July 15 |
| Company B life insurance becomes effective | August 1 |
| Potential period without workplace coverage | July 1–July 31 |
These dates are examples only.
The actual coverage dates depend on both employers' plans.
A transition gap may be particularly concerning when a family relies entirely on workplace life insurance.
If the new employer requires an active-work condition or evidence of insurability for certain coverage amounts, additional considerations may apply.
Before resigning, confirm the termination date of the old coverage and the effective date of the new coverage.
8. What If Your New Employer Offers Less Life Insurance?
A higher-paying job does not always come with a larger life insurance benefit.
Employers design their benefit packages differently.
Company A might provide life insurance equal to two times annual salary.
Company B might provide a fixed $50,000 benefit.
For example:
| Benefit | Company A | Company B |
|---|---|---|
| Annual salary | $85,000 | $105,000 |
| Basic life insurance formula | 2 × salary | Fixed benefit |
| Basic life insurance amount | $170,000 | $50,000 |
In this hypothetical example, the employee receives a $20,000 salary increase but loses $120,000 in basic workplace life insurance protection.
That does not necessarily make Company B's benefits inadequate.
It does mean the employee should consider the difference when reviewing the total compensation package and family protection needs.
A job offer should be evaluated beyond salary alone.
9. What Happens to an Individual Life Insurance Policy When You Change Jobs?
An individually owned life insurance policy generally does not depend on your employment with a particular company.
If you purchased an individual term or whole life policy, changing jobs usually does not affect the policy's continued existence.
The policy generally remains in force as long as required premiums are paid and other contractual conditions are satisfied.
This can be an important distinction between workplace coverage and individual coverage.
For example, a parent might have:
- $100,000 in employer-provided group life insurance.
- $500,000 in individually owned term life insurance.
If the parent changes jobs and loses the employer-provided coverage, the individual policy would generally remain active.
The family could still have $500,000 of individual coverage, assuming the policy remains in force.
However, the loss of the employer benefit could still create a coverage gap.
The presence of an individual policy does not eliminate the need to review total protection.
10. Should You Buy Individual Life Insurance Before Changing Jobs?
There is no universal answer.
For employees whose families depend heavily on workplace coverage, evaluating individual life insurance before leaving a job may be worth considering.
An individual policy can provide protection that is generally independent of a specific employer.
However, individual coverage typically requires an application and underwriting.
Approval, premium rates, and the effective date are not guaranteed.
Depending on the insurer, underwriting may involve health questions, medical records, examinations, or other information.
Avoid assuming a new application provides immediate coverage
Submitting an application is not the same as having an active life insurance policy.
Coverage generally begins according to the insurer's rules and policy terms.
Temporary or conditional coverage may be available in certain circumstances, but it should not be assumed.
If maintaining continuous protection is important, confirm that any replacement policy is actually in force before allowing existing coverage to end.
Do not cancel an existing policy solely because a new application has been submitted.
11. What If You Are Laid Off or Lose Your Job Unexpectedly?
An unexpected job loss can create several financial challenges at once.
Income may stop, health benefits may change, and employer-sponsored life insurance may end.
In this situation, employees should promptly request information about the termination of coverage and any available continuation rights.
Useful questions include:
- When does my life insurance coverage end?
- Am I eligible for portability?
- Do I have a conversion option?
- What is the deadline to apply?
- How much would continued coverage cost?
- Does the plan provide any special continuation provision?
Depending on the plan and circumstances, different rules may apply when employment ends because of a layoff, retirement, disability, or another reason.
It is important to review the actual plan provisions.
Employees should also distinguish life insurance continuation from health insurance continuation.
COBRA primarily addresses continuation of certain group health coverage. It generally does not provide a right to continue group life insurance.
Do not assume that electing COBRA health coverage preserves your life insurance benefit.
12. What About Life Insurance During a Leave of Absence?
Not every interruption in work involves leaving an employer permanently.
An employee may take unpaid leave, medical leave, parental leave, or another approved absence.
Life insurance eligibility during a leave depends on the plan and any applicable legal protections.
Some plans allow coverage to continue for a specified period, subject to premium payment requirements.
Others may have different eligibility or continuation rules.
If you expect to take an extended leave, confirm whether your life insurance remains active and how premiums must be paid.
If payroll deductions stop, you may need another payment arrangement to maintain eligible coverage.
Do not assume that employment status alone guarantees uninterrupted insurance.
13. Five Steps to Protect Your Family Before Changing Jobs
A job transition can be a good opportunity to review your family's overall financial protection.
Step 1: Confirm your current coverage
Find the benefit amounts for basic life insurance, supplemental life insurance, and any spouse or dependent coverage.
Check which benefits are active.
Step 2: Ask when coverage ends
Obtain the actual termination date from the employer or insurer.
Also ask whether any continuation period or other provision applies.
Step 3: Review portability and conversion
Request the applicable forms, deadlines, eligibility rules, premium quotes, and available coverage amounts.
Compare these options with any individual insurance alternatives.
Step 4: Understand the new employer's benefits
Review the new plan's life insurance amount, eligibility date, supplemental options, and underwriting requirements.
Do not assume coverage starts on your first working day.
Step 5: Evaluate your family's overall protection
Consider your dependents, mortgage, income replacement needs, existing policies, savings, and other financial responsibilities.
A job change may increase income while reducing workplace insurance benefits.
The goal is to understand the combined effect on your household.
14. How Turtelle Helps Families Review Their Protection
Life insurance information can become scattered across multiple employers, benefit documents, and individual policies.
An employee may have purchased supplemental coverage several years ago, changed jobs twice, and forgotten how much protection is currently active.
Turtelle Insurance's Family Protection Check offers an educational starting point for reviewing household financial responsibilities and existing insurance protection.
It can help families consider how workplace coverage and individually owned policies fit into their overall financial circumstances.
Turtelle's proprietary Family Protection Score helps communicate the assessment results in an understandable way.
The Protection Check does not verify an employer's coverage, replace official plan documents, guarantee policy eligibility, or provide individualized legal or financial advice.
Employees should confirm their actual benefits and continuation rights with their employer or insurer.
Final Thoughts
Changing jobs can be an exciting step forward.
A better position may bring higher earnings, improved career opportunities, and new employee benefits.
But employer-provided life insurance is not always portable, and a new company's coverage may differ significantly from your previous benefits.
Understanding the termination date, portability and conversion options, and the effective date of new coverage can help you avoid unexpected gaps.
Before you leave a job, know what life insurance you have, when it ends, and what protection your family will have afterward.
A few questions during a job transition can make an important difference in your family's financial preparedness.
Check My Family Protection Score
The free Family Protection Check™ shows how your workplace coverage, personal policies and family needs fit together, and whether there may be a gap.
Check My Family Protection ScoreFrequently asked questions
Does life insurance automatically transfer to a new employer?
No. Employer-provided life insurance generally does not transfer automatically. Your new employer's plan has its own eligibility requirements, benefit amounts, and coverage effective dates.
Can I keep my life insurance after quitting my job?
Possibly. Some group life plans offer portability or conversion options. Availability, costs, deadlines, and eligibility depend on the plan and applicable law.
What is the difference between portability and conversion?
Portability generally allows eligible employees to continue certain group life coverage. Conversion allows eligible employees to obtain an individual policy under specified conditions. The premiums and available benefits may differ.
Is there a deadline to convert employer life insurance?
Yes. Conversion rights generally have application deadlines. Some plans provide 31 days, but the actual deadline depends on the plan and applicable rules. Check your conversion notice immediately.
Does COBRA continue my life insurance after leaving a job?
Generally, no. COBRA primarily provides continuation rights for certain group health benefits, not group life insurance. Life insurance continuation options must be reviewed separately.