LIFE INSURANCE · POLICY PLANNING
Can You Have More Than One Life Insurance Policy?
Can you own two or more life insurance policies? Learn how multiple policies work, why families combine employer and individual coverage, and what to consider before adding another policy.
Can One Person Have Two or More Life Insurance Policies?
Imagine a working parent who has $100,000 of life insurance through an employer.
Several years ago, the parent also purchased a $250,000 individual term life insurance policy.
Now the family has two children, a larger mortgage, and additional financial responsibilities.
The parent begins wondering:
Can I purchase another life insurance policy without canceling the ones I already have?
The answer is generally yes.
In the United States, individuals can typically have more than one life insurance policy at the same time.
Some people combine employer-sponsored life insurance with individual coverage.
Others purchase multiple term policies with different expiration dates.
Some families maintain both term life and permanent life insurance for different purposes.
However, owning multiple policies does not automatically mean the coverage is appropriate.
The important questions are why the additional protection is needed, how the policies work together, and whether the total premiums fit the household budget.
1. Is It Legal to Have More Than One Life Insurance Policy?
Yes.
There is generally no rule limiting a person to only one life insurance policy.
You may be insured under multiple policies issued by the same company or by different insurers.
For example, an individual might have:
- Employer-provided basic life insurance.
- Supplemental life insurance purchased through work.
- An individually owned 20-year term policy.
- A separate permanent life insurance policy.
These policies can coexist, subject to their terms and the insurers' underwriting requirements.
However, insurers generally review how much total life insurance is already in force and how much additional coverage is being requested.
They may consider income, financial obligations, age, and the purpose of the coverage.
Having multiple policies is generally permitted, but approval for additional coverage is not guaranteed.
2. Why Would Someone Need Multiple Life Insurance Policies?
Families often have more than one financial responsibility.
Some obligations may last for decades.
Others may end much sooner.
For example, a parent may want financial protection for:
- Replacing lost household income.
- Paying a mortgage.
- Supporting children until adulthood.
- Funding education.
- Covering final expenses.
- Providing longer-term financial support to a dependent.
A single policy may address several of these needs.
But multiple policies can sometimes provide flexibility.
For instance, one policy might provide income protection for 30 years, while another provides additional coverage during the years when a mortgage is largest.
The decision should depend on the family's financial situation rather than simply the number of policies available.
3. Can You Have Employer Life Insurance and Personal Life Insurance Together?
Yes.
This is one of the most common reasons someone may have multiple life insurance policies.
Many employers offer basic group life insurance as part of their employee benefits package.
Some also allow employees to purchase supplemental coverage.
An employee can generally maintain an individually owned life insurance policy at the same time.
Example: Combining workplace and individual coverage
Suppose an employee has:
| Policy | Death benefit |
|---|---|
| Employer basic life insurance | $100,000 |
| Employer supplemental life insurance | $150,000 |
| Individual term life insurance | $500,000 |
| Total stated coverage | $750,000 |
In this hypothetical example, the employee has $750,000 in combined stated death benefits.
That assumes all three policies cover the same insured person, are active, and would pay their full stated benefits under their respective terms.
The employee's family could potentially receive benefits from all three policies after a covered death.
Why individual coverage can matter
Employer-sponsored coverage often depends on continued eligibility under the employer's plan.
It may end or change when employment ends.
Individually owned life insurance generally remains separate from the employer relationship, provided the policy remains in force.
This can make individual coverage an important component of long-term protection planning.
4. Will All Life Insurance Policies Pay When Someone Dies?
Generally, each valid, in-force life insurance policy can pay its applicable death benefit when the insured person dies and the claim satisfies the policy's terms.
Life insurance is different from some types of insurance that reimburse a specific financial loss.
For example, a beneficiary may receive benefits from more than one life insurance policy covering the same person.
Hypothetical example
A parent has three policies:
| Policy | Death benefit |
|---|---|
| Policy A | $250,000 |
| Policy B | $500,000 |
| Policy C | $100,000 |
| Combined stated benefits | $850,000 |
If all policies are active and the claims are valid, the applicable beneficiaries could collectively receive $850,000.
However, payment depends on each policy's terms, beneficiary designations, and applicable law.
Potential issues may include policy lapse, material application misrepresentation, exclusions, contestability provisions, or other contractual limitations.
Not every policy necessarily pays the same person.
For example, one policy might name a spouse as beneficiary, while another names a trust.
Owning multiple policies does not guarantee that every claim will be paid. Each policy must independently satisfy its terms.
5. Can You Buy Two Term Life Insurance Policies?
Yes.
A person may own two or more term life insurance policies at the same time.
Term life insurance generally provides a death benefit during a specified coverage period.
Some people use multiple term policies to address financial needs that decline over time.
This approach is sometimes called term life insurance layering or laddering.
What is term life insurance laddering?
Laddering involves using multiple policies with different term lengths.
The idea is that certain financial obligations may end earlier than others.
For example, a family may need more protection while children are young and the mortgage balance is high.
Later, the mortgage may be smaller, the children may become financially independent, and the surviving household may need less coverage.
Rather than keeping the same total death benefit for 30 years, a family might use several policies that expire at different times.
6. Example: Layering Three Term Life Insurance Policies
Consider a 35-year-old parent who wants protection for different financial responsibilities.
The parent purchases three hypothetical policies:
| Policy | Coverage | Initial level-term period |
|---|---|---|
| Policy A | $250,000 | 10 years |
| Policy B | $250,000 | 20 years |
| Policy C | $500,000 | 30 years |
The initial combined death benefit is $1 million.
Assuming each policy remains in force during its initial term and ends when that period expires, the protection changes over time.
| Period | Combined coverage |
|---|---|
| Years 1–10 | $1,000,000 |
| Years 11–20 | $750,000 |
| Years 21–30 | $500,000 |
| After year 30 | No coverage from these policies |
This example assumes the shorter policies are not renewed or converted and no other coverage exists.
The approach could align with a family's declining financial obligations.
However, the actual premium savings and suitability depend on the applicant, insurer, policy features, and coverage needs.
Is laddering always better?
No.
Multiple policies create additional administration and may have separate policy fees.
They also introduce different expiration dates and renewal considerations.
A single larger policy may be simpler to manage.
A family should compare the overall cost, duration, and flexibility of the available options.
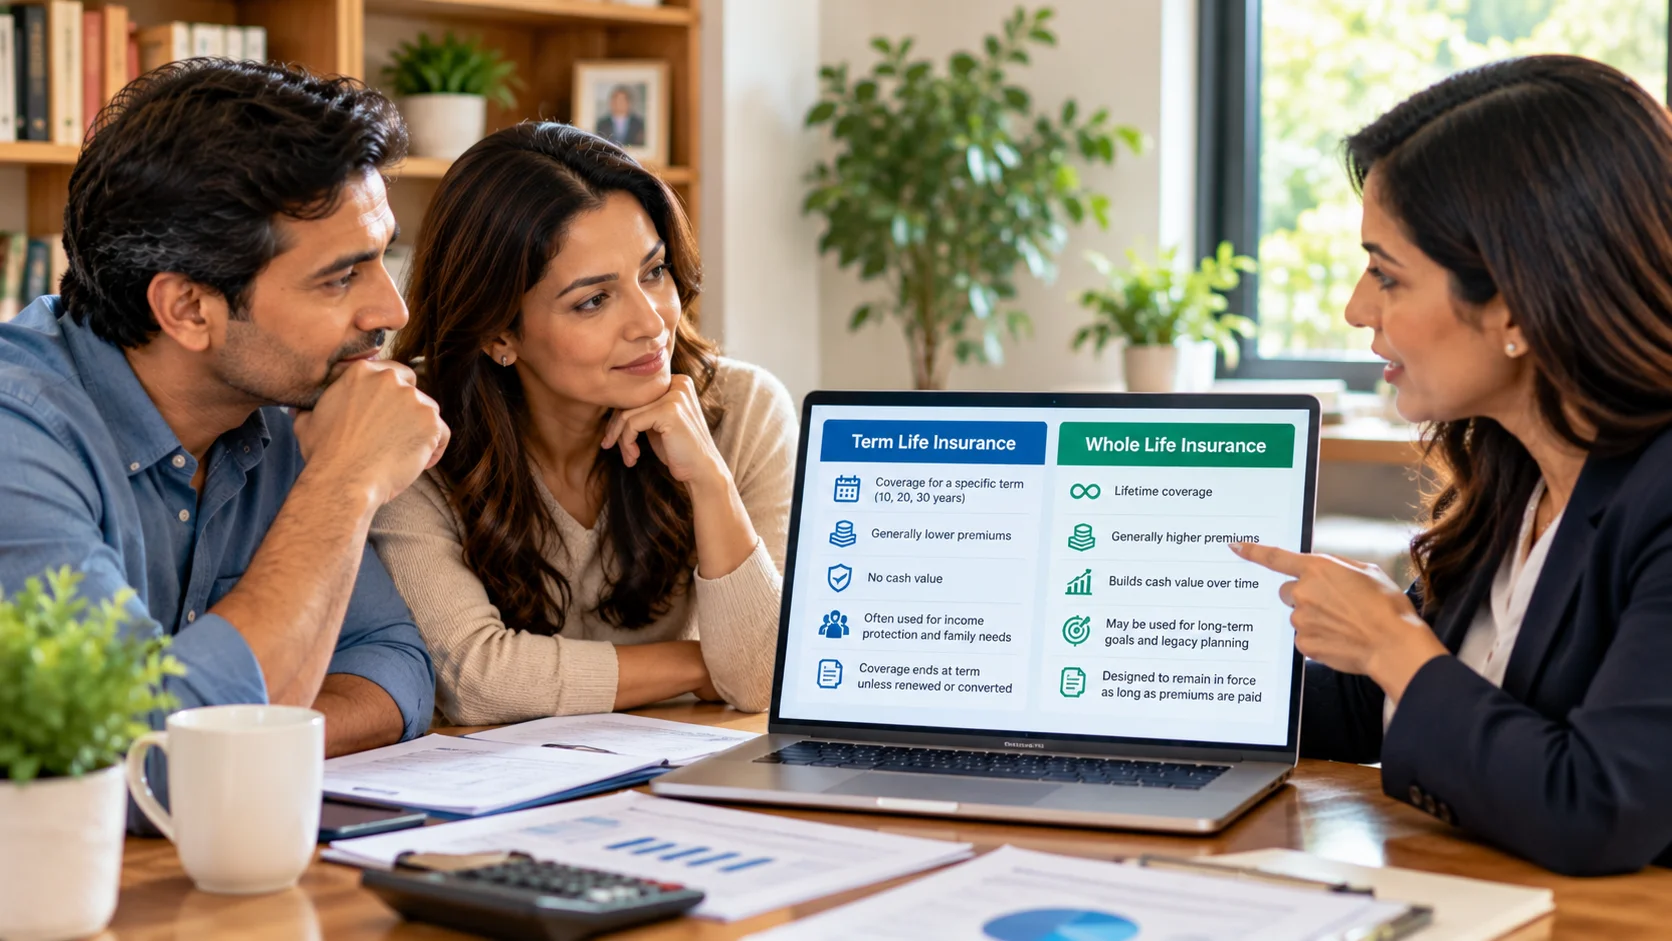
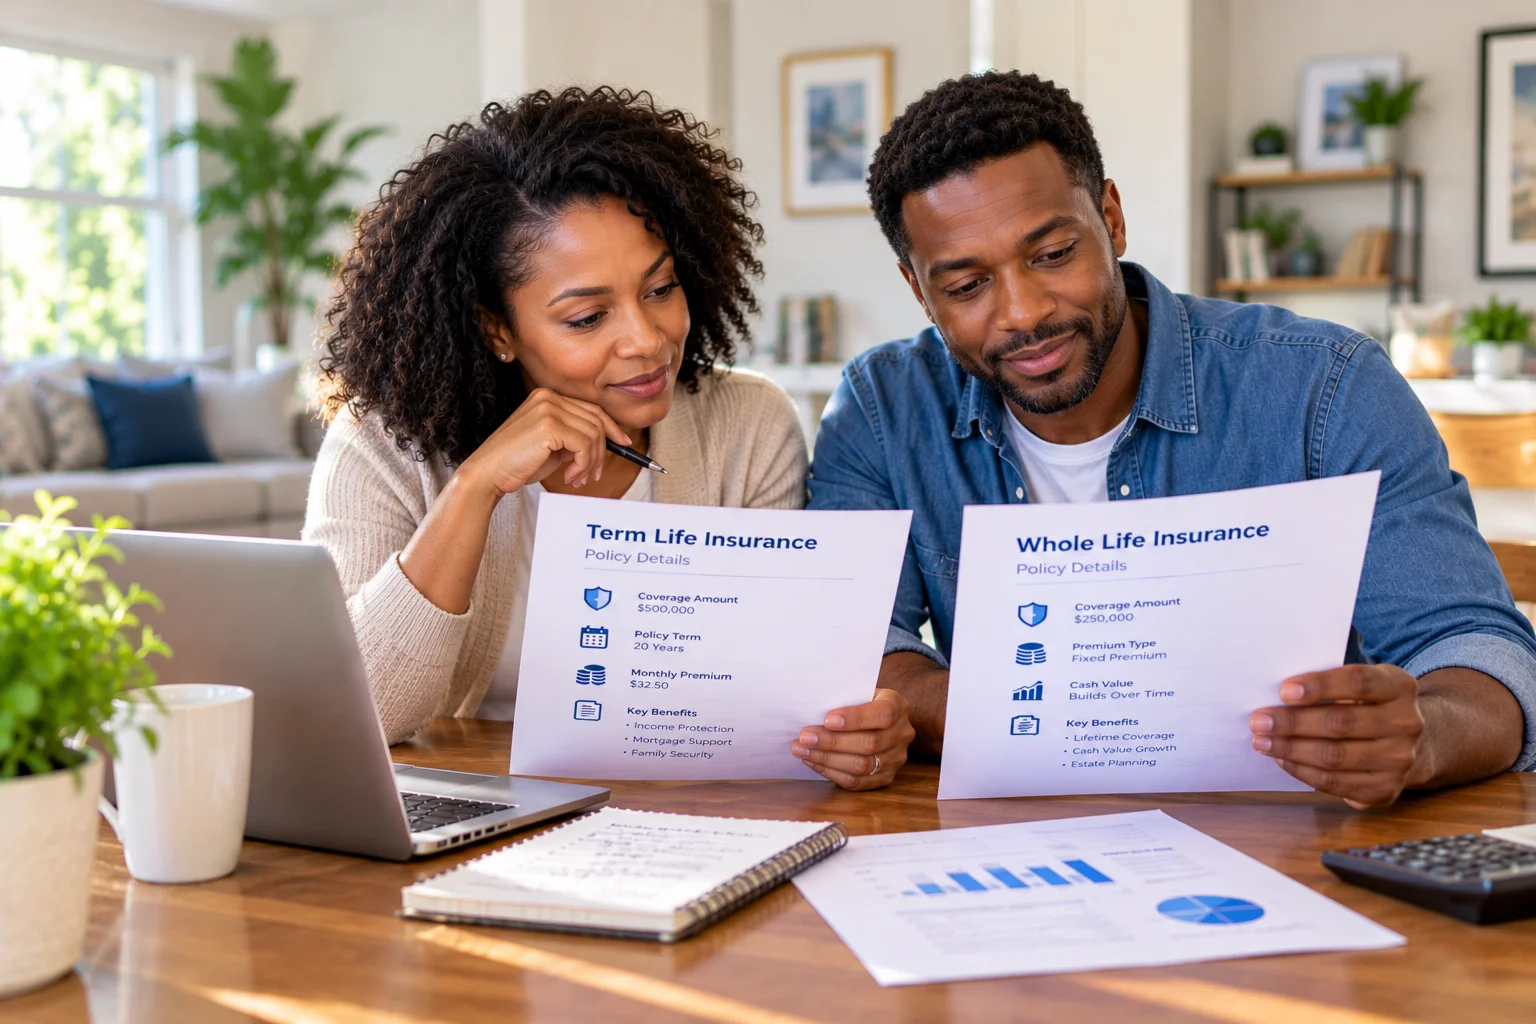
7. Can You Have Both Term Life and Whole Life Insurance?
Yes.
Term life and whole life insurance can serve different purposes.
Term life insurance generally provides coverage for a specified period.
Whole life insurance is designed to provide lifelong coverage, subject to required premiums and policy provisions, and includes a cash-value component.
Some people combine the two.
For example, an individual might maintain a permanent policy for a long-term need while using term insurance to provide additional coverage during working years.
However, permanent life insurance generally has higher initial premiums than comparable term coverage.
Cash-value features, loans, withdrawals, surrender charges, and other provisions can also affect the policy.
Owning both types of insurance is not automatically beneficial.
The combination should support a clearly understood financial purpose.
8. Is There a Maximum Amount of Life Insurance You Can Have?
There is no single universal dollar limit that applies to every person.
However, insurers evaluate whether the amount of life insurance requested is financially justified.
This is sometimes called financial underwriting.
For example, an insurer may consider:
- Annual income.
- Age.
- Existing life insurance.
- Total requested coverage.
- Financial obligations.
- Assets and liabilities.
- The purpose of the insurance.
- Other relevant financial circumstances.
A person earning $70,000 annually who applies for $10 million of additional personal coverage may face different financial underwriting questions than someone with substantially higher income and financial obligations.
That does not mean a specific income automatically qualifies someone for a specific coverage amount.
Insurers use their own financial underwriting guidelines.
Special circumstances, such as business-related insurance or estate planning, may require different documentation.
Why must you disclose existing policies?
Applications commonly ask about existing life insurance and pending applications.
Insurers use this information when assessing the total amount of coverage.
Applicants should provide complete and accurate information.
Failing to disclose relevant coverage or other requested information can create underwriting or claim-related problems.
9. Does Having Multiple Life Insurance Policies Increase Your Premiums?
Each policy generally has its own premium.
If you purchase an additional policy, you will usually have another premium obligation.
However, the existence of one policy does not automatically increase the scheduled premium on a separate, already-issued level-term policy.
The cost of the new policy depends on factors such as:
- Your age when applying.
- Current health and medical history.
- Tobacco or nicotine use.
- Height and weight.
- Coverage amount.
- Policy duration.
- Underwriting classification.
- Insurer pricing.
Example: Why timing matters
Suppose someone purchased a 20-year term policy at age 30.
At age 40, the person decides to purchase another policy.
The original policy may continue at its existing scheduled level premium.
The new policy would generally be priced using the applicant's age and underwriting information at the time of the new application.
The two policies may therefore have different premium rates.
10. Should You Add a New Policy or Increase an Existing One?
Before purchasing additional life insurance, check whether your current policy allows coverage increases.
Some policies may permit changes, subject to underwriting, contractual rules, or other conditions.
Other policies may not allow an increase in the existing death benefit.
In those situations, purchasing a separate policy may be an option.
Consider the following questions:
- Can the existing coverage be increased?
- Would additional underwriting be required?
- Is a separate policy more flexible?
- How do the total premiums compare?
- Do the policies have different expiration dates?
- Are conversion options available?
- Are there policy fees or other charges?
There is no universal answer.
The better approach depends on the existing policy and the family's current needs.
11. What Happens If You Forget About an Old Life Insurance Policy?
A common challenge with multiple policies is keeping track of them.
Someone may purchase a term policy, change jobs, obtain additional coverage, and later forget the details of an older policy.
Over time, the household may lose track of:
- Policy numbers.
- Insurance companies.
- Premium payment schedules.
- Beneficiary designations.
- Coverage amounts.
- Expiration dates.
- Contact information.
This can make it harder for beneficiaries to identify and claim benefits.
How to organize multiple policies
Consider maintaining a simple life insurance record.
| Information | What to record |
|---|---|
| Insurance company | Carrier name |
| Policy number | Policy identifier |
| Insured person | Person whose life is covered |
| Death benefit | Current stated amount |
| Beneficiary | Primary and contingent beneficiaries |
| Premium | Amount and payment frequency |
| Expiration date | Term end or relevant coverage date |
| Contact details | Insurer or servicing agent |
Store the information securely.
Make sure the appropriate person knows where to find it.
Avoid sharing sensitive policy information unnecessarily.
12. Do Multiple Policies Need the Same Beneficiary?
No.
Different life insurance policies may name different beneficiaries.
For example:
- One policy might name a spouse.
- Another might name a trust.
- A third might divide benefits among multiple beneficiaries.
Beneficiary arrangements should reflect the policyholder's intentions and applicable legal requirements.
Some states and circumstances have spousal consent or other rules.
Naming minor children directly can also create practical and legal complications.
Families with complex beneficiary needs may benefit from qualified legal or estate-planning advice.
Review beneficiaries after major life events
Marriage, divorce, childbirth, death of a beneficiary, or changes in family relationships may make an existing designation outdated.
Beneficiary designations should be reviewed periodically.
Do not assume a will automatically overrides the beneficiary designation on a life insurance policy.
13. What Are the Disadvantages of Having Multiple Policies?
Multiple life insurance policies can provide flexibility, but they also have potential disadvantages.
More premiums to manage
Each policy creates a payment obligation.
Missing premiums can lead to lapse, subject to applicable grace periods and policy provisions.
More administrative work
Different policies may have different insurers, beneficiaries, payment dates, and expiration dates.
Coverage may become outdated
As financial responsibilities change, the total coverage may no longer match the household's needs.
Policy terms may differ
One policy may have conversion rights, while another may not.
Some policies may include riders or other features that affect coverage.
Additional underwriting
A new application may require updated health and financial information.
The applicant's eligibility or offered rate may differ from earlier applications.
The goal should be appropriate, manageable protection rather than collecting policies without a clear purpose.
14. Can Multiple Life Insurance Policies Help Close a Protection Gap?
Potentially, yes.
A family may discover that its existing insurance does not fully address estimated financial needs.
Additional coverage may help reduce that gap.
Hypothetical example
A family estimates it needs $900,000 in financial protection.
It currently has:
| Resource | Amount |
|---|---|
| Employer life insurance | $100,000 |
| Individual term life insurance | $400,000 |
| Total existing life insurance | $500,000 |
If the family is considering only these death benefits, the simplified difference is:
$900,000 − $500,000 = $400,000
An additional policy might help address that estimated shortfall.
But this is not automatically a recommendation to purchase $400,000 of coverage.
The family should also consider savings, other resources, changing financial responsibilities, affordability, and the limitations of the estimate.
An assessment helps identify questions worth exploring.
15. How Turtelle Helps Families Review Multiple Policies
Life insurance coverage can become difficult to understand when it is spread across several policies and workplace benefits.
Turtelle Insurance's Family Protection Check helps families evaluate estimated financial protection needs and existing coverage.
The proprietary, rule-based Family Protection Score helps communicate the assessment results.
Turtelle's Policy X-Ray is designed to help users review existing life insurance policy information and consider how that coverage relates to their estimated needs.
These tools can provide an educational starting point for identifying possible protection gaps or areas requiring further review.
They do not independently guarantee policy validity, confirm claim eligibility, replace official insurer documents, or determine whether a particular policy should be purchased, replaced, or canceled.
Where available, eligible users may explore additional life insurance options through Turtelle.
Actual policy availability, underwriting, premiums, and coverage decisions depend on the insurer and applicable requirements.
16. Questions to Ask Before Purchasing Another Policy
Before adding another life insurance policy, consider:
- How much life insurance do I already have?
- Which policies depend on my employment?
- When will my existing policies expire?
- How much financial support might my family need?
- What financial responsibilities will end over time?
- Can I afford the combined premiums?
- Would one additional policy or several smaller policies better match my needs?
- Have I reviewed the beneficiary designations?
- Have I accurately disclosed existing coverage to the insurer?
- Do I understand the terms and limitations of each policy?
These questions can help make the decision more intentional.
Final Thoughts
You can generally have more than one life insurance policy.
For some families, combining employer-provided coverage with individually owned policies offers flexibility.
Others may use multiple term policies with different expiration dates to address changing financial responsibilities.
However, more policies do not automatically mean better protection.
The total coverage should reflect your family's needs, and the combined premiums should remain manageable.
The important question is not how many life insurance policies you own. It is whether your overall coverage supports the financial responsibilities you want to protect.
Reviewing your policies together can help you understand what you have, what may change, and whether additional protection deserves consideration.
Check My Family Protection Score
The free Family Protection Check™ shows how your workplace coverage, personal policies and family needs fit together, and whether there may be a gap.
Check My Family Protection ScoreFrequently asked questions
Can I have two life insurance policies from different companies?
Yes. You can generally own policies from different insurers. Each company evaluates applications under its own underwriting guidelines, including existing coverage and financial justification.
Will both life insurance policies pay if I die?
Generally, yes, if both policies cover the insured person, remain in force, and each claim satisfies its policy terms. Benefits are paid according to the beneficiary designations and applicable provisions.
Can I have employer life insurance and individual term life insurance?
Yes. Employer-provided coverage and individually owned term life insurance can coexist. The individual policy generally remains separate from your employment relationship.
Is there a maximum number of life insurance policies I can own?
There is no universal maximum number. However, insurers may limit the total amount of coverage they are willing to issue based on financial underwriting and other eligibility requirements.
Is it cheaper to buy one large policy or several smaller policies?
It depends on the insurer, policy amounts, term lengths, underwriting classifications, and fees. Multiple smaller policies may offer flexibility, but they are not necessarily less expensive.