LIFE INSURANCE · FAMILY PROTECTION
How Much Life Insurance Does Your Family Really Need?
A practical guide to estimating coverage based on your income, debts, family responsibilities, and future goals.
Why Does the Amount of Life Insurance Matter?
Imagine a family with two children, a mortgage, and two working parents.
Every month, their income helps pay for housing, groceries, utilities, transportation, school activities, and savings. They may also be planning for college, retirement, or helping aging parents.
Now imagine one of those incomes suddenly disappears.
The emotional loss would be immeasurable. But alongside it, the family could face difficult financial decisions: Can they keep their home? Can the surviving parent continue working? Will the children have the same educational opportunities? How long will their savings last?
Life insurance cannot replace a loved one. But an appropriate policy can help provide money for the people who depend on that person's income, caregiving, or financial contributions.
The challenge is determining how much coverage is appropriate.
The goal is not simply to purchase the largest policy available. It is to understand what your family may need and choose protection that fits your circumstances and budget.
1. Is 10–15 Times Your Annual Income Enough?
You may have heard a common rule of thumb: purchase life insurance equal to 10–15 times your annual income.
For someone earning $80,000 per year, that suggests coverage of approximately $800,000 to $1.2 million.
This can be a useful starting point because it encourages families to think beyond one or two years of expenses.
However, it is not a personalized calculation.
Consider two people who each earn $80,000.
Person A is 28 years old, has no children, rents an apartment, and has relatively little debt.
Person B is 38 years old, has two young children, a $350,000 mortgage, and a spouse who works part-time.
Although both earn the same salary, their financial responsibilities are very different.
Person B may need more protection because the household has dependents, long-term housing costs, and childcare or education obligations.
Person A may need less coverage, depending on whether anyone relies on their income or would be responsible for their debts and final expenses.
This is why an income multiplier should be treated as a starting estimate—not a universal recommendation.
2. What Financial Responsibilities Should You Include?
A more meaningful life insurance estimate begins with the expenses and goals your family would need to manage without you.
Income replacement
Ask yourself:
How many years would my family need financial support?
A household with young children may need support for many years. A household approaching retirement may have a shorter period of income dependence.
You should also consider whether the surviving spouse or partner would continue earning the same amount.
For example, a surviving parent might need to reduce working hours to care for children. That change could reduce household income even further.
Rather than automatically replacing your entire salary for a fixed number of years, estimate how much of your income the household would actually need.
Mortgage and housing costs
For many families, housing is their largest monthly expense.
Life insurance proceeds could help a surviving family member:
- Pay off some or all of a mortgage.
- Continue making monthly housing payments.
- Cover property taxes, insurance, and maintenance.
- Avoid selling the family home solely because of lost income.
Paying off the mortgage is one possible strategy, but it is not always necessary. Some families may prefer to keep a mortgage and use insurance proceeds to support ongoing living expenses.
The right approach depends on interest rates, other financial resources, and the surviving household's needs.
Other outstanding debts
Consider debts such as car loans, credit cards, private student loans, and personal loans.
Not every debt automatically becomes a surviving family member's personal responsibility. Liability depends on the type of debt, ownership, guarantees, estate rules, and applicable state law.
Still, outstanding obligations can affect the family's finances, especially when a surviving spouse is a joint borrower or co-signer.
Understanding those obligations helps you estimate how much additional protection may be useful.
Children's education and childcare
If you have children, think about the expenses that may arise before they become financially independent.
These might include daycare, after-school care, tutoring, extracurricular activities, vocational training, and college.
The younger your children are, the longer some of these costs may continue.
Education planning does not require predicting every future tuition bill precisely. Even a reasonable estimate can help reveal whether your existing coverage is likely to be sufficient.
Final expenses and immediate cash needs
A death can create immediate costs, including funeral or memorial arrangements, travel, unpaid household bills, and other short-term expenses.
Families may also need time to settle financial matters, access accounts, and adjust to a different income.
An emergency reserve can help, but life insurance may provide another source of funds for eligible beneficiaries when a covered claim is paid.
3. How Can You Calculate Your Life Insurance Needs?
One practical approach is to estimate your family's future financial needs and subtract resources already available to meet them.
Step 1: Estimate income support
Consider the amount of annual income your household would need to replace and how many years that support might be required.
For example, if your family would need an additional $50,000 per year for 15 years, a simple starting estimate would be:
$50,000 × 15 = $750,000
This is an illustrative calculation, not a present-value estimate. It does not account for investment returns, inflation, taxes, or changes in household spending.
A more detailed financial plan would consider those factors.
Step 2: Add major financial obligations
Next, consider obligations or goals not already included in the income-support estimate.
These might include a mortgage balance, education funding, immediate expenses, or specific family commitments.
Be careful not to count the same expense twice.
For example, if your income-support estimate already includes monthly mortgage payments, adding the entire mortgage balance separately could overstate the amount needed.
Step 3: Subtract available resources
Your family may already have resources that could help cover future expenses, such as:
- Existing individual life insurance.
- Employer-provided life insurance.
- Savings designated for family support.
- Certain accessible investments.
- Other dependable sources of household income.
Do not automatically subtract every retirement account or investment. Some assets may be earmarked for the surviving spouse's retirement, difficult to access, or subject to taxes or other limitations.
The important question is: Which resources could realistically support your family without undermining other essential goals?
Step 4: Review the remaining gap
The difference between estimated needs and available resources can provide a starting point for evaluating additional life insurance.
This is sometimes called a life insurance coverage gap.
A gap estimate is not a guarantee of how much coverage an insurer will offer or approve. Eligibility, underwriting, affordability, and policy terms also matter.
4. A Realistic Family Example
Consider a hypothetical household with the following circumstances:
- One parent's annual income: $100,000.
- Two children, ages 6 and 11.
- Remaining mortgage balance: $300,000.
- Existing individual life insurance: $150,000.
- Employer-provided life insurance: $100,000.
- Savings available for family support: $50,000.
After reviewing the household budget, the family estimates it would need $60,000 per year in additional support for the next 15 years.
They also want to set aside money for education and immediate expenses.
| Financial need or resource | Illustrative amount |
|---|---|
| Income support: $60,000 × 15 years | $900,000 |
| Children's future education | $120,000 |
| Immediate and final expenses | $30,000 |
| Estimated total needs | $1,050,000 |
| Existing individual coverage | −$150,000 |
| Employer-provided coverage | −$100,000 |
| Available savings | −$50,000 |
| Illustrative remaining gap | $750,000 |
In this example, the family's income-support estimate already includes ongoing mortgage payments and housing expenses. The $300,000 mortgage balance is therefore not added again.
The calculation suggests a potential additional coverage need of $750,000.
But that figure could change significantly if the family chooses to pay off the mortgage immediately, adjusts its education goals, changes the support period, or uses a more detailed present-value calculation.
It is also important to verify whether the employer-provided coverage would remain available under the relevant employment and benefit conditions.
The lesson is not that every family earning $100,000 needs a particular amount of life insurance. It is that household responsibilities matter more than income alone.
5. Does Employer-Provided Life Insurance Count?
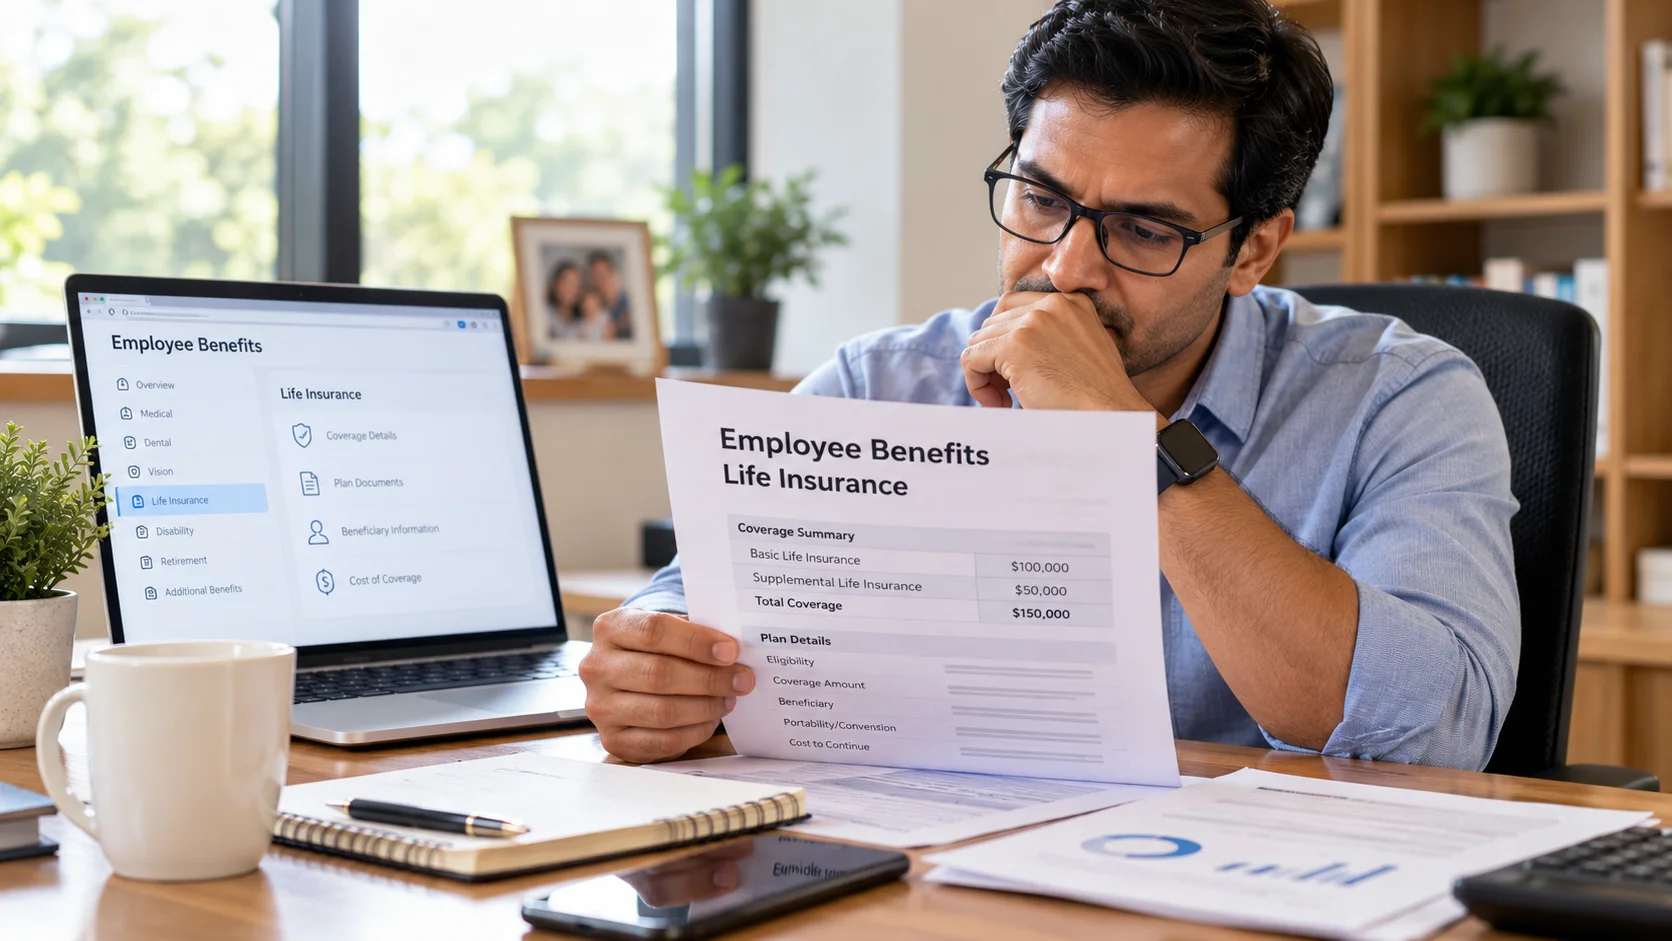
Yes. Employer-provided life insurance may be an important part of your family's existing protection.
Many employers offer basic group life insurance as an employee benefit. Some also allow employees to purchase additional voluntary coverage.
However, the amount and conditions can vary.
For example, an employer might provide coverage equal to one year's salary.
If you earn $100,000, that could mean a $100,000 death benefit while the applicable coverage remains in force.
For a household with a mortgage and young children, that amount may cover only part of its longer-term needs.
Employer coverage may also change when you leave a job, retire, become ineligible, or experience other changes specified in the plan.
Some plans offer portability or conversion options, but deadlines, costs, eligibility, and terms differ.
Before relying heavily on workplace coverage, review your benefits documents and ask:
- How much coverage do I currently have?
- Is the benefit based on salary or a fixed amount?
- What happens if I change employers?
- Can I continue or convert the coverage?
- Are there any exclusions, reductions, or eligibility conditions?
Employer-provided life insurance can be valuable, but it should be reviewed as one component of your broader protection plan.
6. What About a Stay-at-Home Parent?
A common mistake is evaluating life insurance needs only by looking at salary.
A stay-at-home parent may not receive a paycheck, but their contribution to the household can have substantial financial value.
Consider the responsibilities they may manage: childcare, school transportation, meal preparation, household administration, and care for family members.
If that parent were no longer there, the surviving household might need to pay for services previously provided without a direct financial transaction.
The working parent might also need to reduce working hours.
For this reason, life insurance for a non-earning spouse or partner can be worth considering.
Rather than multiplying a salary of zero, estimate the potential cost of replacing caregiving responsibilities and the additional support the household would need.
The appropriate coverage amount will depend on the family's circumstances and insurer eligibility rules.
7. Should You Choose Term Life or Permanent Life Insurance?
Once you have estimated how much coverage you may need, the next question is how long you need it.
Term life insurance
Term life insurance generally provides coverage for a specified period, such as 10, 20, or 30 years, provided the policy remains in force.
It is often considered when the primary goal is protecting against financial obligations that may decline over time, such as raising children or paying a mortgage.
Term policies typically do not build cash value.
If the insured person dies during the covered term and the policy conditions are met, the insurer pays the death benefit to the designated beneficiary.
Permanent life insurance
Permanent life insurance is designed to provide longer-duration coverage, potentially for the insured person's lifetime, subject to the policy's terms and required premiums.
Some permanent policies include cash-value features.
These policies can be more complex, and their premiums are often higher than those of comparable term policies.
The right choice depends on your goals, affordability, coverage duration, and the specific policy.
For families primarily seeking income protection during their working and child-raising years, term life insurance is often a useful option to evaluate. That does not mean it is appropriate for everyone.
8. Can You Have More Than One Life Insurance Policy?
Yes. It is possible to have multiple life insurance policies, subject to insurer underwriting and financial justification.
For example, someone might have:
- Basic group life insurance through an employer.
- An individual 20-year term policy.
- A smaller policy intended for a specific financial obligation.
Some families use policies with different terms or amounts to align coverage with changing needs.
However, having multiple policies does not automatically mean your protection is sufficient.
Review the combined death benefits, policy expiration dates, premium obligations, and beneficiary designations.
Also remember that applying for additional insurance does not guarantee approval.
9. When Should You Reevaluate Your Coverage?
Life insurance planning should not be a one-time decision.
Your financial responsibilities can change substantially over a decade.
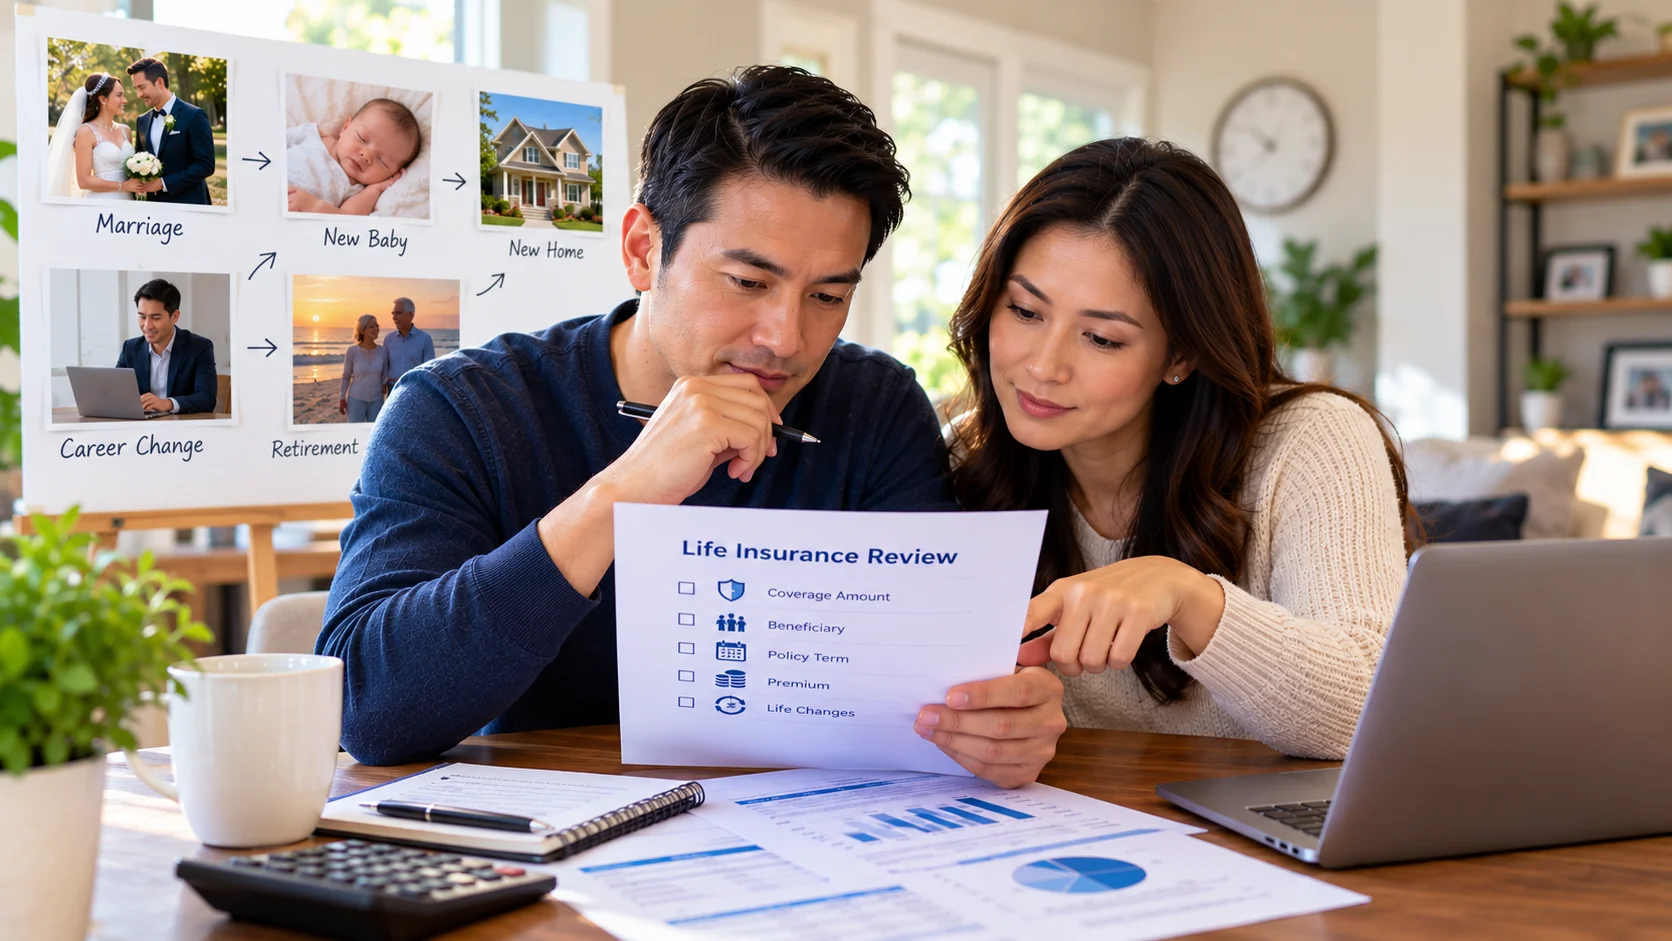
Consider reviewing your coverage when you:
- Get married or enter a long-term partnership.
- Have or adopt a child.
- Purchase a home.
- Change jobs or lose employer-provided benefits.
- Experience a major income change.
- Take on significant debt.
- Become responsible for aging parents.
- Approach retirement.
- Pay off major obligations.
Even without a major life event, reviewing your coverage periodically can help ensure that your original assumptions still make sense.
A policy purchased before children, for example, may no longer reflect the responsibilities of a household with teenagers and a mortgage.
Similarly, someone approaching retirement with substantial savings and fewer dependents may need a different level of protection than they did 20 years earlier.
10. What Are Common Life Insurance Planning Mistakes?
Several mistakes can make a coverage estimate less useful.
Relying only on an income multiplier. A simple rule may overlook dependents, existing resources, or major obligations.
Ignoring employer coverage limitations. Workplace coverage may be valuable but may not remain in force after certain employment changes.
Forgetting the financial value of caregiving. A non-earning parent may provide services that would be expensive to replace.
Counting expenses twice. Adding a mortgage balance on top of income replacement that already includes mortgage payments can inflate the estimate.
Assuming every asset is available. Retirement savings and investments may be intended for other essential needs.
Failing to review beneficiaries. Even a well-designed policy can create complications if beneficiary information is outdated or inconsistent with your intentions.
Never reviewing coverage again. A family's needs can change significantly after purchasing a policy.
Avoiding these mistakes can make your protection decisions more deliberate and better informed.
11. How Can Turtelle Help You Understand Your Protection?
Knowing how much coverage you have is only part of the picture.
The more important question is whether that coverage is appropriate for your family's circumstances.
Turtelle Insurance's Family Protection Score is a proprietary assessment designed to help families understand their current financial protection.
Through Turtelle's Protection Check, you can explore your circumstances, review potential coverage gaps, and gain a clearer starting point for evaluating your options.
The assessment is an educational planning tool. It is not an insurance underwriting decision, a guarantee of coverage, or a substitute for individualized professional advice.
The objective is to help you ask better questions before making an important financial decision.
Final Thoughts
There is no single life insurance amount that works for every family.
Two households with identical incomes may have very different needs because of their children, debts, savings, employment benefits, and future plans.
An income multiplier can offer a starting point, but a thoughtful estimate should consider the financial responsibilities that would remain if you were no longer there.
Start with the people who depend on you. Consider what they would need, how long they would need it, and which resources would already be available.
Then review your protection as your life changes.
The right life insurance decision begins with understanding your family's needs—not simply choosing a number.
Check My Family Protection Score
The free Family Protection Check™ shows how your workplace coverage, personal policies and family needs fit together, and whether there may be a gap.
Check My Family Protection ScoreFrequently asked questions
Is 10 times my salary enough life insurance?
Not necessarily. Ten times annual income is a rough starting point, not a personalized recommendation. Your actual needs depend on dependents, debts, future expenses, savings, and existing coverage.
Should I include my mortgage when calculating life insurance?
Yes, housing expenses should be considered. You may plan to pay off the mortgage or fund ongoing payments, but avoid counting the same housing costs twice.
Is employer-provided life insurance enough?
It depends on the benefit amount, your family's financial needs, and the plan's terms. Employer coverage can be helpful, but it may change or end when employment or eligibility changes.
Does a stay-at-home parent need life insurance?
It may be worth considering. Childcare, household management, and other unpaid responsibilities can create significant replacement costs if that parent dies.
How often should I review my life insurance coverage?
Review your coverage periodically and after major events such as marriage, having children, buying a home, changing jobs, or taking on substantial financial obligations.