SMALL BUSINESS · EMPLOYEE BENEFITS
How Small Businesses Can Offer Meaningful Life Insurance Benefits
A practical guide to helping small businesses evaluate affordable group life insurance, voluntary coverage, employee eligibility, enrollment, and long-term benefits planning.
Why Life Insurance Matters for Small Businesses
Small-business owners face a difficult balancing act.
They want to attract good employees, support their teams, and build a workplace where people feel valued. At the same time, they must manage payroll, operating expenses, business growth, and unpredictable financial demands.
Employee benefits are an important part of that equation.
Health insurance and retirement benefits often receive the most attention, but life insurance can also provide meaningful financial protection for employees' families.
For a small business, offering life insurance does not necessarily require a large or complicated benefits program.
A carefully structured plan can begin with a modest employer-paid benefit, optional employee-paid coverage, or a combination of both.
The goal is not simply to offer another workplace perk.
The goal is to provide a benefit employees understand, value, and can use as part of their broader financial protection planning.
1. What Is Small-Business Group Life Insurance?
Group life insurance is coverage offered to eligible employees through an employer-sponsored insurance arrangement.
Rather than each employee independently purchasing a policy, the employer establishes a group program under which eligible employees can receive coverage.
Depending on the insurer and plan, group coverage may include:
- Basic employer-paid life insurance.
- Voluntary employee-paid life insurance.
- Supplemental life insurance.
- Spouse or dependent life insurance options.
- Accidental death and dismemberment coverage, if offered.
Not every insurer provides all these options to every employer.
Plan availability may depend on workforce size, employee participation, eligibility rules, and other underwriting requirements.
Why group coverage may appeal to small businesses
A group arrangement can simplify access to coverage for eligible employees.
Some plans offer simplified enrollment or guaranteed-issue amounts during designated enrollment periods.
Employers may also benefit from coordinated billing, enrollment support, and standardized plan administration.
However, group insurance is not automatically available to every business, and it is not always the lowest-cost option for every employee.
2. Can a Small Business With Only a Few Employees Offer Life Insurance?
Potentially, yes.
Some insurers and benefit providers offer group life insurance arrangements designed for smaller employers.
However, there is no universal minimum employee count that applies to every group life insurance plan.
One insurer may require a minimum number of eligible employees, while another may have different rules.
Availability may also depend on:
- Number of eligible employees.
- Minimum participation.
- Employer premium contributions.
- Employee classifications.
- Business location.
- Insurer underwriting guidelines.
For example, a company with six employees may have different group insurance options from a company with 60 employees.
A very small employer that cannot qualify for a conventional group plan may explore other legally permissible benefit approaches with qualified insurance and benefits advisers.
Employers should confirm eligibility before promising specific coverage.
3. Start With the Purpose of the Benefit
Before requesting insurance proposals, small-business owners should define what they want the program to accomplish.
Common objectives include:
Providing basic family financial protection
An employer may want every eligible employee to have a foundational death benefit.
Offering employees additional choice
Some employees may want more coverage than the employer can afford to provide.
Voluntary coverage can allow eligible employees to consider additional protection.
Strengthening the overall benefits package
Life insurance may complement health coverage, retirement plans, disability insurance, and paid leave.
Supporting employee financial well-being
Employees have different household financial responsibilities.
A life insurance benefit can be one component of a broader financial well-being strategy.
The employer's objectives should guide plan design rather than choosing a policy solely because it has the lowest advertised premium.
4. Three Practical Life Insurance Approaches for Small Businesses
Small employers can consider several structures.
Option A: Employer-paid basic life insurance
The business pays premiums for a specified amount of life insurance for eligible employees.
For example, an employer might consider a $25,000 or $50,000 basic death benefit.
These are hypothetical amounts, not guaranteed offerings.
Potential advantages:
- Employees receive a foundational benefit.
- The employer directly supports employee financial protection.
- The program can be relatively easy to explain.
Potential considerations:
- The employer has an ongoing premium expense.
- Coverage amounts may be insufficient for some households.
- Insurer participation and eligibility rules still apply.
Option B: Employee-paid voluntary life insurance
The employer makes an eligible voluntary group life insurance plan available, and employees elect and generally pay for the coverage they choose.
Potential advantages:
- Employees have more choice.
- The employer may have limited direct premium expense.
- Employees may have access to certain group enrollment features.
Potential considerations:
- Employees must understand and actively evaluate the benefit.
- Participation requirements may apply.
- Some coverage requests may require evidence of insurability.
- The employer may still have administrative responsibilities.
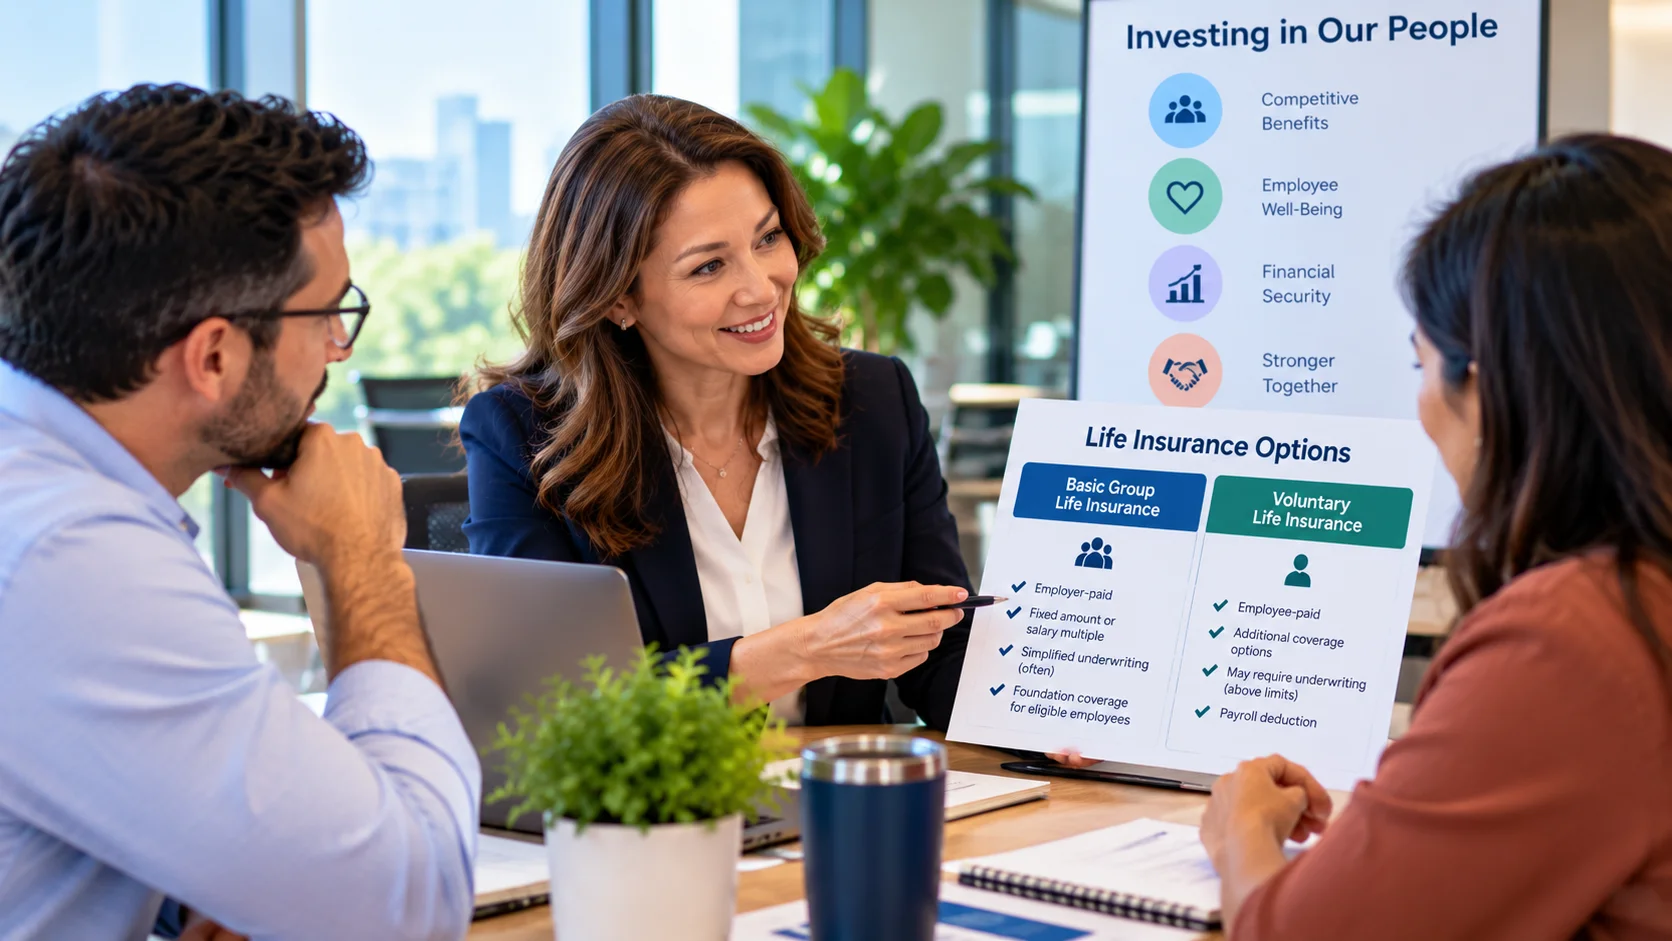
Option C: Basic life plus voluntary coverage
The employer provides a basic amount and allows eligible employees to purchase additional coverage.
This arrangement combines a foundational benefit with employee choice.
For some small businesses, it may offer a useful balance between employer cost and employee flexibility.
5. Comparing the Three Approaches
| Feature | Employer-paid basic | Employee-paid voluntary | Combined approach |
|---|---|---|---|
| Employer premium expense | Generally yes | Often limited or none | Yes, for basic coverage |
| Employee choice | Usually limited | Greater choice | Greater choice |
| Foundational coverage | Yes, for eligible covered employees | Only if elected and effective | Yes, for eligible covered employees |
| Additional coverage | Not necessarily | May be available | May be available |
| Underwriting | Depends on plan | May apply to higher amounts | Depends on each coverage component |
| Administration | Required | Required | Required |
| Budget flexibility | Depends on benefit design | Often greater direct premium flexibility | Depends on basic benefit amount |
No single structure is best for every employer.
The right choice depends on the company's financial capacity, workforce characteristics, and available insurance arrangements.
6. How Much Does Small-Business Life Insurance Cost?
This is often the first question business owners ask.
Unfortunately, there is no reliable universal monthly price for group life insurance.
Premiums may depend on:
- Number of insured employees.
- Employee ages or age distribution.
- Benefit amounts.
- Insurer pricing methodology.
- Industry or occupational characteristics.
- Participation and employer contribution levels.
- Other underwriting and policy terms.
An employer with 12 eligible employees may receive a very different proposal from an employer with 45 employees.
Illustrative budgeting example
Suppose a hypothetical group life insurance proposal results in an average employer cost of $8 per covered employee per month.
For 20 covered employees:
| Calculation | Amount |
|---|---|
| Covered employees | 20 |
| Illustrative monthly cost per employee | $8 |
| Illustrative monthly employer cost | $160 |
| Illustrative annual employer cost | $1,920 |
This example demonstrates budgeting arithmetic only.
The $8 amount is not a Turtelle quote, a market-average premium, or a promise that coverage is available at that price.
Actual premiums and eligibility must be confirmed through insurer proposals.
Small businesses should evaluate the total annual cost, renewal provisions, and administrative expenses—not only the initial monthly premium.
7. How to Build a Benefits Budget
A sustainable benefits program begins with realistic financial planning.
Employers should determine:
- How much they can contribute annually.
- Whether the budget can accommodate future growth.
- Whether coverage will be offered to all eligible employees or permissible employee classes.
- Whether employee-paid options should supplement the employer benefit.
- How renewal increases will be evaluated.
Consider workforce growth
A business with 15 employees today may have 25 employees next year.
An employer-paid benefit that appears affordable initially may become more expensive as the workforce grows.
For this reason, employers should consider both current and projected enrollment.
Avoid designing benefits around temporary savings
Life insurance is most useful when employees can understand and rely on the coverage terms.
Employers should avoid creating expectations that a benefit will remain unchanged indefinitely if the company cannot sustain the associated cost.
8. What Is Guaranteed-Issue Coverage?
Some group life insurance programs offer guaranteed-issue amounts to eligible employees during designated enrollment periods.
Within the applicable limit, employees may obtain coverage without individual medical evidence if all plan requirements are met.
However, guaranteed issue is subject to conditions.
These may include:
- Initial eligibility.
- Timely enrollment.
- Active-at-work requirements.
- Minimum participation.
- Maximum coverage amounts.
- Other insurer rules.
Example
A hypothetical plan might permit eligible employees to elect up to $100,000 of voluntary life insurance without individual medical underwriting during initial enrollment.
An employee requesting more may need to provide evidence of insurability.
The actual guaranteed-issue amount and requirements vary.
Small-business owners should confirm these terms before describing coverage as automatically available.
9. Employee Eligibility and Participation Requirements
A group insurance proposal may specify who qualifies for coverage.
Eligibility conditions can include:
- Employment classification.
- Minimum scheduled working hours.
- Waiting periods.
- Active-at-work requirements.
- Other lawful plan criteria.
Certain employee classifications or participation arrangements may also be subject to applicable legal requirements.
Why participation matters
Some insurers require a minimum percentage of eligible employees to enroll.
Employer-paid plans and employee-paid plans may have different participation rules.
For example, an insurer may require a higher participation level for one type of plan than another.
Employers should ask carriers to explain the requirements in writing.
Failure to meet a required participation threshold can affect plan availability or renewal.
10. Should Small Businesses Offer the Same Coverage to Everyone?
Employers may consider a uniform benefit amount or a salary-based benefit.
Fixed-dollar benefit
Eligible employees receive the same specified basic coverage amount.
This can be straightforward to communicate and budget.
Salary-based benefit
Coverage is based on a multiple of eligible earnings, subject to plan limits.
This can align the death benefit more closely with employee compensation.
Different employee classes
Some plans permit different benefit classes, but eligibility and benefit distinctions must comply with insurer rules and applicable laws.
Employers should not assume that arbitrary classifications are permissible.
Insurance advisers, benefits counsel, and tax professionals can help evaluate proposed plan structures.
11. How to Compare Group Life Insurance Proposals
Small businesses should compare more than premium rates.
A practical evaluation should address:
Coverage structure
What basic and voluntary benefits are available?
Insurer eligibility
Does the business qualify based on employee count and participation?
Premiums
How are costs calculated, and how can they change?
Guaranteed-issue provisions
What amounts are available without individual medical underwriting?
Evidence of insurability
When must employees submit additional information?
Portability and conversion
What options may exist when employment ends?
Exclusions and limitations
What policy conditions affect payment of benefits?
Administration
Who manages enrollment, billing, eligibility changes, and employee questions?
Service and support
What resources are available to employees and HR administrators?
A comparison matrix can make differences between proposals easier to understand.
12. Employee Education Is Essential
Offering a benefit does not automatically mean employees understand it.
Employees may not know:
- Whether they already have basic life insurance.
- How much coverage the employer provides.
- Whether additional coverage is available.
- What voluntary premiums cost.
- Whether underwriting is required.
- Who should be named as beneficiary.
- What happens when they change jobs.
Small businesses can improve employee understanding with simple communication.
Practical approaches
Provide a short benefits guide explaining:
- Basic coverage amounts.
- Voluntary options.
- Premium deductions.
- Enrollment deadlines.
- Guaranteed-issue limits.
- Beneficiary instructions.
- Coverage continuation provisions.
Avoid overwhelming employees with technical insurance terminology.
Clear explanations can be more useful than lengthy promotional materials.
13. Why Employees May Need More Than Workplace Coverage
A basic group life insurance benefit can provide valuable protection.
But the amount may be small compared with a family's long-term financial responsibilities.
Consider a hypothetical employee who earns $75,000 annually and receives $50,000 of employer-paid basic life insurance.
That employee may also have:
- A mortgage.
- Dependent children.
- Household living expenses.
- Outstanding debts.
- Future education costs.
- Limited savings.
The $50,000 workplace benefit may help with immediate expenses but may not replace years of income.
This does not mean every employee needs the same amount of additional coverage.
Personal needs depend on financial circumstances.
The employer's role
Employers can explain the coverage provided and offer educational resources.
They should not assume that a single benefit amount meets every family's needs.
Employees can independently evaluate their financial protection and decide whether to explore additional insurance.
14. What Happens When an Employee Leaves?
Employer-sponsored life insurance is frequently tied to employment eligibility.
When an employee resigns, retires, or otherwise loses eligibility, coverage may end or change.
Some policies offer portability or conversion options.
Portability
Portability may allow an eligible employee to continue certain group coverage after leaving employment, subject to conditions.
Conversion
Conversion may allow eligible employees to convert qualifying group coverage into an individual policy.
Deadlines, premium amounts, eligibility, and policy features vary.
Why employers should communicate this clearly
An employee may mistakenly believe that voluntary life insurance automatically continues after changing jobs.
Small businesses should provide accurate information about coverage termination and any continuation options.
Employees should be directed to the official insurer materials for applicable requirements.
15. Administrative Responsibilities for Small Employers
Life insurance programs involve ongoing administration, even when employees pay the premiums.
Typical responsibilities may include:
- Maintaining eligibility records.
- Processing new hires and terminations.
- Coordinating employee elections.
- Managing payroll deductions.
- Communicating enrollment opportunities.
- Maintaining required plan documentation.
- Coordinating with the insurer or benefits administrator.
Some functions may be handled by brokers, carriers, payroll providers, or third-party administrators.
However, employers should understand which responsibilities remain with the organization.
Compliance considerations
Depending on the arrangement, employer-sponsored life insurance may be subject to ERISA and other applicable requirements.
Employers should obtain qualified guidance on plan documentation, employee disclosures, tax reporting, and other compliance obligations.
16. Tax Considerations
Employer-provided group-term life insurance can have federal tax implications.
Under applicable IRS rules, the cost of certain employer-provided group-term life insurance coverage exceeding $50,000 generally creates taxable imputed income, subject to exceptions and specific calculation rules.
This does not mean every dollar of coverage above $50,000 is directly taxed.
The IRS provides rules for calculating the taxable cost of applicable coverage.
Small-business payroll considerations
Employers should coordinate with payroll professionals and tax advisers regarding:
- Employee contributions.
- Imputed income.
- Applicable withholding.
- Payroll reporting.
- Relevant exceptions.
Tax treatment may vary based on the arrangement and circumstances.
17. How Small Businesses Can Improve Employee Participation
For voluntary life insurance, employee participation can be an important consideration.
Participation may improve when employees understand the purpose and mechanics of the coverage.
Employers can support informed enrollment by:
Explaining the benefit in plain language
Employees should understand what life insurance does and does not provide.
Showing realistic examples
Simple examples can demonstrate how coverage amounts and premiums work without promising individual eligibility or rates.
Making enrollment accessible
Employees should know how to submit elections and whom to contact with questions.
Explaining underwriting requirements
Employees should understand when additional approval may be necessary.
Respecting employee choice
Education should support voluntary decision-making rather than pressure employees into purchasing insurance.
Participation goals should never override suitability, transparency, or applicable enrollment requirements.
18. How Turtelle Can Support Small-Business Benefits Planning
Turtelle Insurance is an insurance technology platform focused on making life insurance easier to understand.
For small-business owners, Turtelle provides a pathway to explore employer life insurance options and request information about potential group benefits programs.
For employees, Turtelle's Family Protection Check offers an educational way to estimate financial protection needs.
The proprietary, rule-based Family Protection Score helps communicate assessment results based on information entered by the user.
The score is not AI-generated.
These educational tools can help employees think about:
- Their current life insurance coverage.
- Household financial responsibilities.
- Potential protection gaps.
- Whether they should explore additional coverage.
The assessment does not determine underwriting eligibility, guarantee premiums, or replace individualized professional advice.
Employers should respect employee privacy and should not require access to personal household assessment results as part of ordinary benefits administration.
Any insurance quote, coverage availability, and policy issuance depend on the applicable insurer and its requirements.
Turtelle does not issue or underwrite insurance policies.
19. A Practical Implementation Roadmap
Small-business owners can approach the process in stages.
Step 1: Define the objective
Decide whether the primary goal is basic financial protection, additional employee choice, or a combination.
Step 2: Establish the budget
Identify an affordable annual employer contribution and consider workforce growth.
Step 3: Confirm eligibility
Determine which group insurance arrangements are available for the business.
Step 4: Compare proposals
Review coverage amounts, premiums, underwriting provisions, participation rules, and continuation options.
Step 5: Select a plan
Choose an arrangement that balances employer cost, employee needs, and administration.
Step 6: Prepare employee communication
Develop clear materials explaining eligibility, benefits, premiums, and enrollment.
Step 7: Launch enrollment
Coordinate with the insurer and administrator to confirm elections and effective coverage.
Step 8: Review annually
Evaluate plan costs, employee understanding, administrative issues, and changes in workforce needs.
20. Small-Business Life Insurance Checklist
Before launching a program, employers can review the following questions:
- [ ] Have we defined why we want to offer life insurance?
- [ ] Have we established a sustainable benefits budget?
- [ ] Do we meet insurer group eligibility requirements?
- [ ] Have we compared employer-paid and voluntary options?
- [ ] Do we understand participation requirements?
- [ ] Have we reviewed guaranteed-issue limits?
- [ ] Do we know when evidence of insurability applies?
- [ ] Have we compared premiums and renewal provisions?
- [ ] Are eligibility rules and employee classifications appropriate?
- [ ] Have we reviewed portability and conversion options?
- [ ] Are enrollment and payroll processes documented?
- [ ] Have we considered applicable legal and tax obligations?
- [ ] Do employees have clear educational materials?
- [ ] Have we established an annual review process?
A structured approach can help a small business avoid unnecessary complexity while offering a meaningful employee benefit.
Final Thoughts
Small businesses do not need to match the benefits budgets of large corporations to begin exploring life insurance protection for their employees.
A modest employer-paid benefit, an employee-paid voluntary option, or a combination of both may provide a practical starting point.
The key is to understand what the organization can sustainably support and what employees need to know before making coverage decisions.
Meaningful life insurance benefits are not defined only by the size of the death benefit.
They are also defined by clear communication, accessible enrollment, appropriate plan design, and reliable administration.
For small businesses, a thoughtfully designed life insurance program can be one way to support employees and the families who depend on them.
Explore Employer Solutions
See how Turtelle helps employers manage group life insurance and help employees understand their protection.
Explore Employer SolutionsFrequently asked questions
Can a small business offer life insurance with only a few employees?
Yes, potentially. Some insurers offer group life insurance arrangements for small employers. Minimum employee counts, participation requirements, and other eligibility conditions vary by insurer and plan.
How much does group life insurance cost a small business?
The cost depends on factors such as employee count, age distribution, coverage amounts, insurer pricing, and plan design. Employers should request actual proposals and compare total annual costs, renewal provisions, and administrative requirements.
Can a small business offer life insurance without paying all the premiums?
Yes. Some employers offer employee-paid voluntary group life insurance, allowing eligible employees to elect coverage and pay premiums. The employer may still have administrative responsibilities, and insurer participation requirements may apply.
Do employees need medical examinations for group life insurance?
Not always. Some group plans offer guaranteed-issue amounts during eligible enrollment periods. Higher amounts or certain applications may require evidence of insurability, depending on plan rules.
Is employer-provided life insurance enough for employees' families?
Not necessarily. Workplace coverage can provide valuable financial protection, but individual needs vary based on income, debts, dependents, savings, and future expenses. Employees may benefit from reviewing their total coverage against their financial responsibilities.