EMPLOYEE BENEFITS · LIFE INSURANCE
Why Life Insurance Belongs in Your Employee Benefits Strategy
Life insurance is more than an optional workplace benefit. Discover how employers can support employees' families, strengthen their benefits strategy, and offer meaningful financial protection.
Employee Benefits Should Protect More Than Today's Paycheck
When employers design employee benefits packages, health insurance, retirement plans, paid leave, and wellness programs often receive the most attention.
These benefits play important roles in supporting employees and their families.
But there is another benefit that deserves consideration: life insurance.
For employees who support a spouse, children, aging parents, or other dependents, the unexpected loss of income after death can create substantial financial challenges.
Life insurance can provide a financial benefit to designated beneficiaries when an insured employee dies and the claim satisfies the policy's terms.
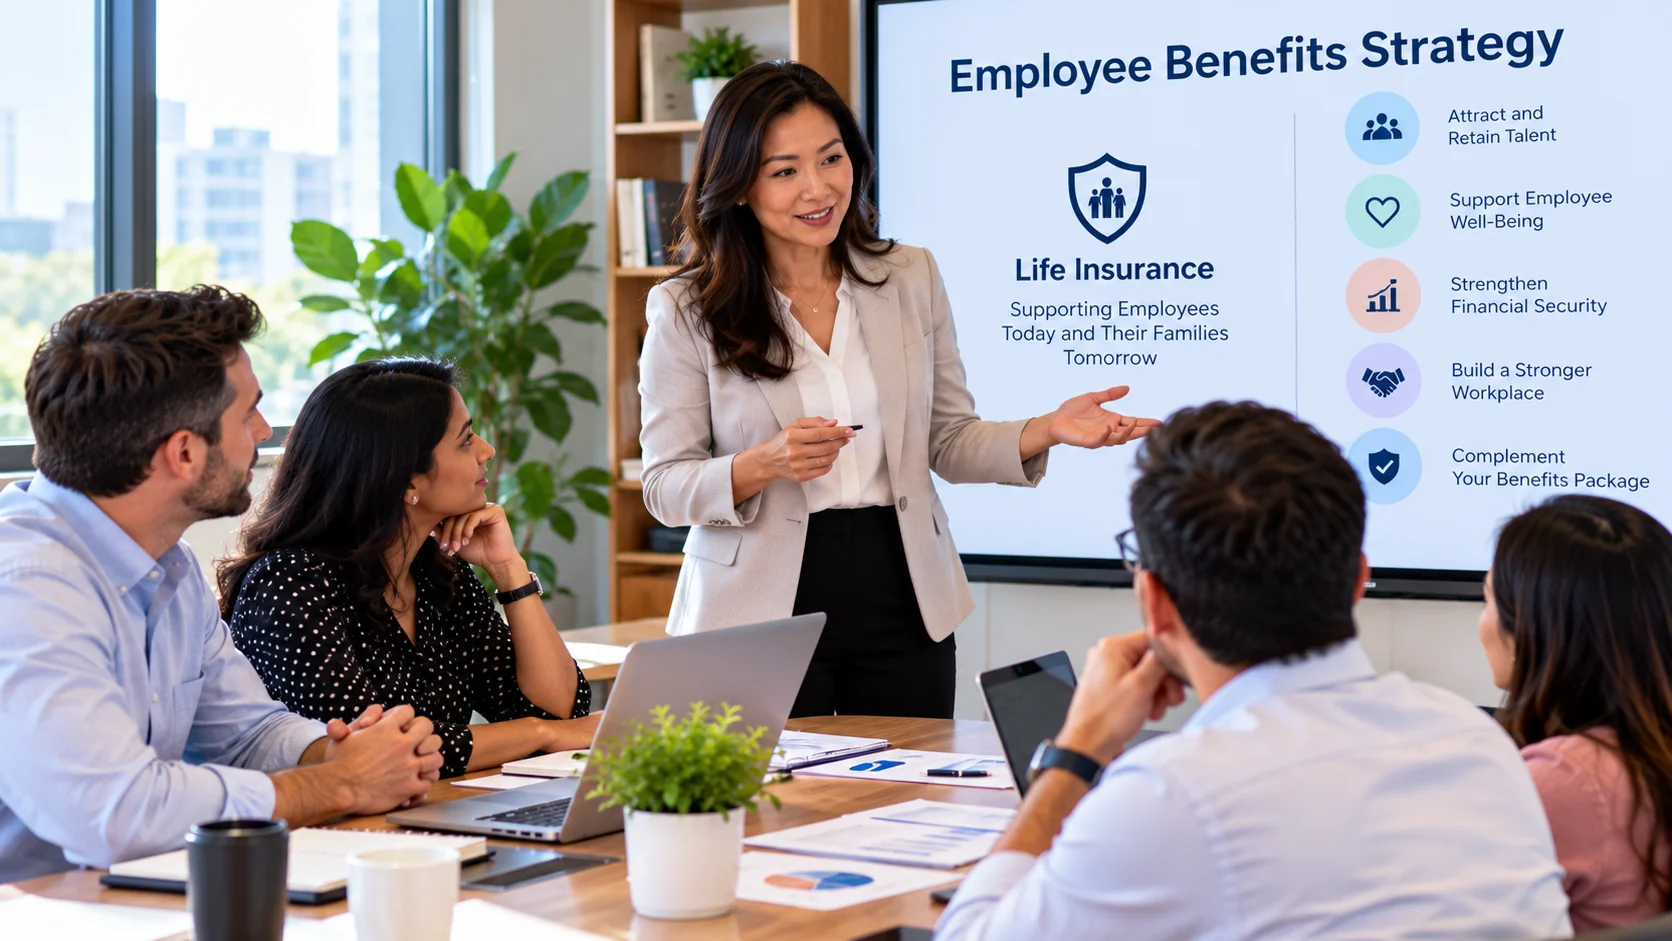
For employers, offering life insurance is one way to support employees' broader financial well-being.
It can also complement an organization's overall benefits strategy.
However, simply offering a policy is not enough.
Employers should understand what their coverage provides, how employees experience the benefit, and whether the plan aligns with workforce needs.
1. What Is Employer-Sponsored Life Insurance?
Employer-sponsored life insurance is coverage made available through an employer's benefits program.
It is commonly offered through a group insurance arrangement.
Depending on the plan, the employer may pay the premium, employees may pay for optional coverage, or costs may be shared.
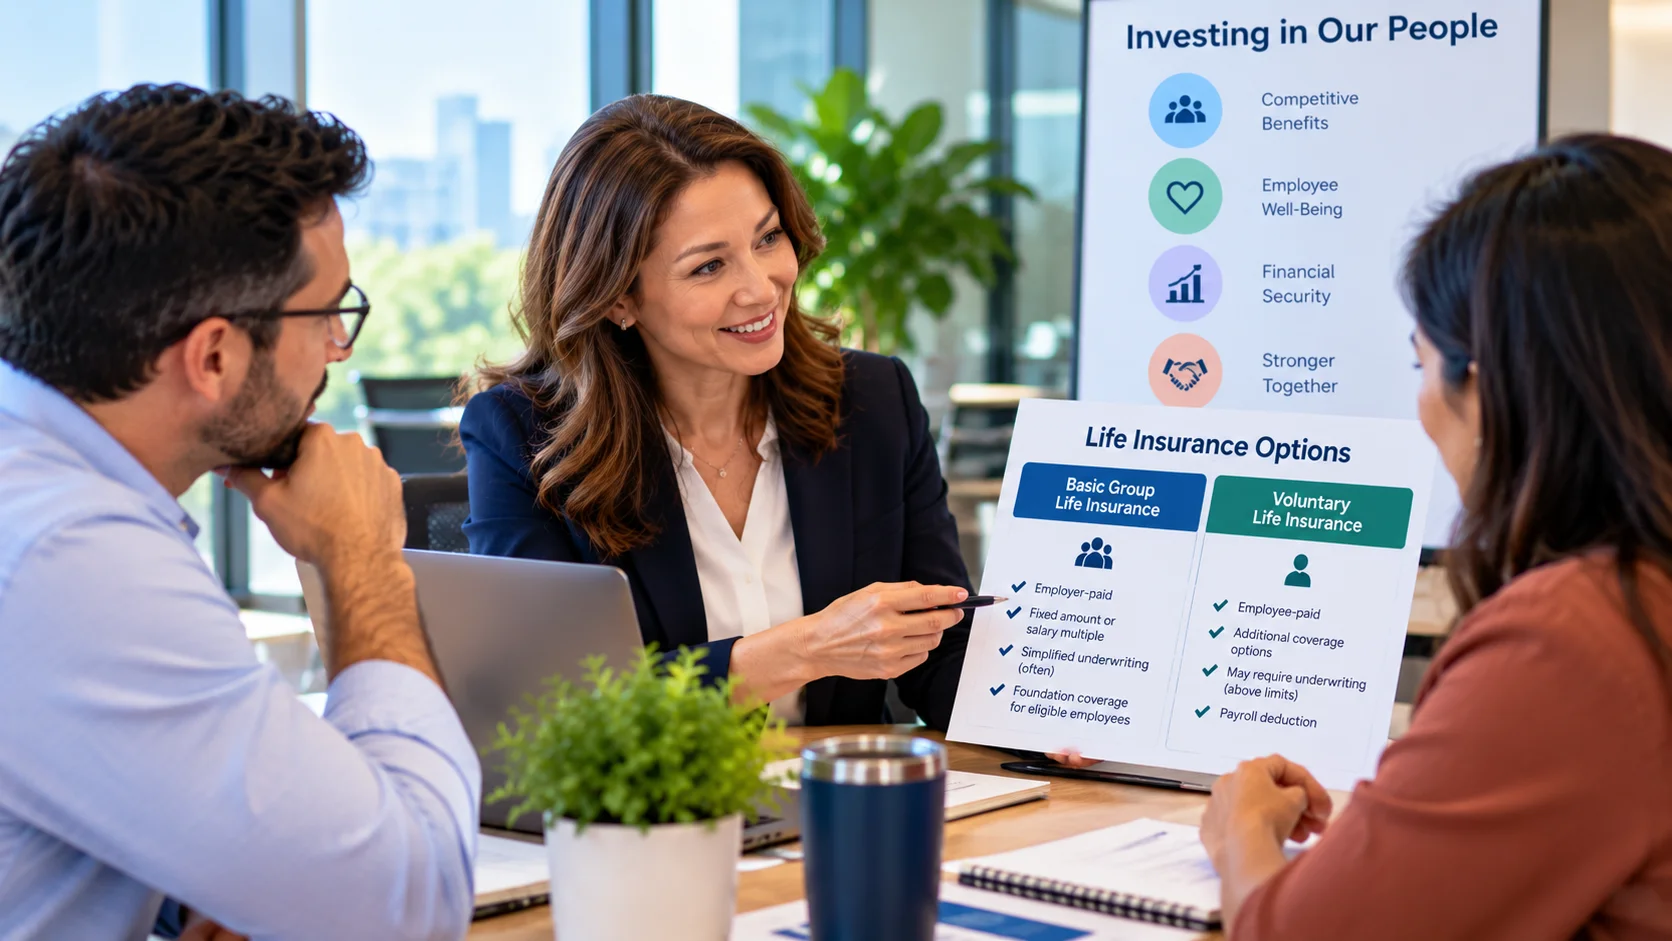
Common arrangements include basic group life insurance and supplemental or voluntary life insurance.
Basic group life insurance
Basic group life insurance is often provided as an employer-paid benefit.
Coverage may be a fixed amount, such as $25,000 or $50,000, or a multiple of an employee's salary.
For example, an employer might offer coverage equal to one year's base salary.
Actual benefit amounts, eligibility rules, maximums, and costs depend on the plan.
Supplemental or voluntary life insurance
Some employers also allow eligible employees to purchase additional coverage.
Employees may choose from available coverage amounts, subject to the insurer's rules.
Premiums are often paid through payroll deductions.
Higher amounts may require evidence of insurability, depending on the plan and enrollment circumstances.
Dependent life insurance
Some group plans offer optional coverage for spouses or eligible dependents.
Availability, coverage limits, underwriting requirements, and eligibility rules vary.
Employers should evaluate these features as part of the overall plan rather than assuming every group policy offers the same options.
2. Why Life Insurance Matters to Employees and Their Families
An employee's income often supports more than the employee alone.
It may help pay for:
- Housing and mortgage payments.
- Groceries and utilities.
- Childcare.
- Education.
- Transportation.
- Healthcare.
- Debt obligations.
- Support for dependent family members.
If the employee dies unexpectedly, the surviving household may face both emotional and financial disruption.
Life insurance cannot replace a loved one.
But a death benefit can provide financial resources that beneficiaries may use to address immediate and longer-term needs.
A simple example
Consider an employee earning $80,000 annually.
The employee has a spouse, two children, and a mortgage.
The employer provides $80,000 of basic life insurance.
That benefit could be meaningful to the family.
However, it represents only one year of the employee's salary.
Depending on the family's savings, surviving income, debts, and future expenses, the household may need financial support for substantially longer.
This example illustrates why employer-provided life insurance can be a valuable foundation without necessarily being a complete financial protection solution.
3. Life Insurance Complements Other Employee Benefits
Life insurance serves a different purpose from health insurance, disability coverage, and retirement benefits.
Each addresses a different financial risk.
| Benefit | Primary purpose |
|---|---|
| Health insurance | Helps cover eligible medical expenses |
| Disability insurance | May replace part of income during a qualifying disability |
| Retirement benefits | Help employees accumulate or receive retirement income |
| Life insurance | Provides a benefit to beneficiaries after a covered death |
| Paid leave | Provides eligible time away from work under the applicable policy or law |
These benefits can work together as part of a broader financial well-being strategy.
For example, an employer may already provide a competitive health plan and retirement program.
Adding life insurance may address a financial concern that those benefits do not directly cover.
However, employers should assess the cost and value of each benefit in the context of their overall compensation strategy.
4. Can Life Insurance Help Employers Attract and Retain Employees?
Employee benefits can influence how workers evaluate employment opportunities.
An employer that offers a thoughtful benefits package may communicate that it values employees' long-term well-being.
Life insurance can contribute to that overall offering.
For example, an employer-paid basic life benefit may be viewed as a meaningful addition to salary, health insurance, and retirement benefits.
Supplemental coverage can also provide employees with additional choices.
Avoid assuming a guaranteed recruitment benefit
Offering life insurance does not automatically improve retention, reduce turnover, or increase job applications.
Those outcomes depend on many factors, including compensation, workplace culture, career opportunities, and the broader benefits package.
Employers should evaluate whether life insurance meets the needs of their workforce rather than relying on unsupported promises about recruitment results.
Why communication matters
Employees cannot fully appreciate a benefit they do not understand.
A plan that is clearly explained may be more useful to employees than one that receives little attention during enrollment.
Benefits education should therefore be part of the strategy from the beginning.
5. Employer-Paid vs. Employee-Paid Life Insurance
Employers can structure life insurance programs in different ways.
Two common approaches are employer-paid basic coverage and employee-paid supplemental coverage.
Employer-paid basic coverage
Under this arrangement, the employer pays for a specified amount of group life insurance for eligible employees.
Potential advantages include:
- Providing a foundational benefit.
- Simplifying the initial employee decision.
- Demonstrating employer support for family financial protection.
- Potentially allowing coverage without individual medical underwriting up to applicable limits.
The employer must also consider premium costs, eligibility rules, administration, and future renewals.
Employee-paid supplemental coverage
Supplemental coverage gives eligible employees the opportunity to elect additional insurance.
Potential advantages include:
- Greater employee choice.
- The ability to select coverage amounts within plan limits.
- Payroll deduction convenience.
- Possible simplified underwriting for certain amounts or enrollment periods.
However, supplemental coverage is not necessarily suitable or affordable for every employee.
Pricing may depend on age bands, elected coverage, tobacco classifications, or other plan-specific factors.
Combining the approaches
Some employers offer basic coverage at employer expense and allow employees to purchase additional insurance.
This structure can provide a starting benefit while giving employees more flexibility.
The appropriate arrangement depends on the employer's budget, workforce characteristics, and available insurance options.
6. How Much Life Insurance Should an Employer Offer?
There is no universal coverage amount that is appropriate for every employer.
Some organizations provide a fixed death benefit.
Others use a multiple of annual salary.
For example, an employer might consider:
| Illustrative plan design | Example |
|---|---|
| Fixed benefit | $50,000 per eligible employee |
| Salary-based benefit | One times annual base salary |
| Higher salary multiple | Two times annual base salary |
| Basic plus supplemental | Employer-paid base amount with optional employee-paid coverage |
These are examples of possible designs, not recommendations or confirmed carrier offerings.
The actual available options depend on the insurer, employer eligibility, state requirements, and plan terms.
Factors employers should evaluate
Before selecting a benefit amount, consider:
- Workforce size.
- Employee age distribution.
- Compensation levels.
- Employer budget.
- Employee needs and preferences.
- Eligibility requirements.
- Coverage maximums.
- Participation requirements.
- Renewal provisions.
- Administrative responsibilities.
Employers should also consider whether a salary-based design could create coverage differences across employees with different compensation levels.
The goal is to establish a thoughtful and financially sustainable benefit structure.
7. Why Basic Employer Coverage May Not Be Enough for Every Employee
One of the biggest challenges with group life insurance is that employees have different financial responsibilities.
Two employees earning the same salary may have very different protection needs.
Example: Two employees, same benefit
Suppose an employer provides $100,000 of basic life insurance to two employees.
Employee A is single, has no dependents, and has limited debt.
Employee B is married, has three children, and carries a substantial mortgage.
Both receive the same employer benefit.
But the financial impact of losing either employee's income could be very different for their respective households.
The same death benefit does not necessarily provide the same level of financial protection.
This is why employers should avoid presenting a fixed group benefit as sufficient for every family.
What employers can do
Employers can help employees understand:
- Their basic coverage amount.
- Whether supplemental coverage is available.
- How to review beneficiaries.
- What happens to coverage after employment ends.
- Where to find educational resources.
- How to consider their broader family protection needs.
This approach supports informed employee decisions without requiring the employer to make individual insurance recommendations.
8. Understanding Guaranteed-Issue Coverage and Underwriting
Some group life insurance plans offer guaranteed-issue coverage up to specified limits for eligible employees.
This may allow employees to obtain certain amounts without answering individual medical questions during a qualifying enrollment opportunity.
However, guaranteed-issue provisions have conditions.
They may depend on:
- Employee eligibility.
- Enrollment timing.
- Participation requirements.
- Active-at-work provisions.
- Coverage limits.
- Other plan rules.
Amounts above the guaranteed-issue limit may require evidence of insurability.
That can involve health questions or additional underwriting.
Employers should explain these distinctions clearly.
Employees should not assume that every amount shown in an enrollment system is automatically approved.
9. What Happens to Employee Life Insurance When Someone Leaves the Company?
Employer-sponsored life insurance is often tied to employment or plan eligibility.
Coverage may end when an employee:
- Resigns.
- Is terminated.
- Retires.
- Becomes ineligible under the plan.
- Experiences another qualifying change in status.
Some plans offer continuation options.
These may include portability or conversion, subject to plan and insurer provisions.
Portability
Portability may allow eligible employees to continue certain coverage after leaving employment.
The available amount, cost, deadlines, and other conditions depend on the plan.
Conversion
Conversion may allow eligible employees to convert group coverage into an individual policy under specified conditions.
The resulting policy may differ from the original group coverage.
Why employers should explain these options
Employees may assume their life insurance follows them automatically to a new job.
That is not always the case.
Providing clear information about coverage termination and continuation deadlines can help employees make more informed decisions during job transitions.
10. The Importance of Employee Life Insurance Education
Offering a benefit and helping employees understand it are two different responsibilities.
Employees may know they have life insurance without understanding:
- How much coverage they have.
- Who will receive the benefit.
- Whether their spouse or children are covered.
- What supplemental insurance costs.
- Whether medical underwriting is required.
- When coverage ends.
- Whether their family's needs exceed workplace coverage.
These gaps in understanding can reduce the practical usefulness of the benefit.
Education should begin during onboarding
New employees should receive clear explanations of their available coverage.
Important information includes eligibility, enrollment deadlines, beneficiary designations, and available optional benefits.
Education should continue during annual enrollment
Annual enrollment is an opportunity to remind employees about their coverage and encourage them to review changes in family circumstances.
Education should be accessible
Employers should use clear language and make benefits information accessible to employees with different levels of financial knowledge.
Educational materials should complement, not replace, official plan documents and insurer disclosures.
11. Protecting Employee Privacy in Benefits Education
Life insurance discussions can involve sensitive personal and family information.
Employees may need to consider income, debts, dependents, existing insurance, and health-related matters.
Employers should distinguish between administering a group benefits program and accessing an employee's personal financial circumstances.
For example, an employer may need information about enrollment, eligibility, and payroll deductions.
That does not mean the employer needs to see each employee's household debts, personal insurance policies, or individual protection assessment.
A privacy-conscious approach
Employers should:
- Collect only information needed for legitimate benefits administration.
- Limit access to employee benefits information.
- Explain what information is shared with insurers or service providers.
- Follow applicable privacy and security requirements.
- Avoid unnecessary access to personal financial assessments.
Any reporting about employee engagement or benefits education should be designed to protect individual privacy.
12. How Small Businesses Can Approach Life Insurance Benefits
Life insurance is not only relevant to large corporations.
Small businesses may also consider group life insurance as part of their benefits packages.
However, availability and plan design can depend on the number of eligible employees and insurer requirements.
A small employer should begin by understanding:
- How many employees are eligible.
- What benefit budget is available.
- Whether employer-paid coverage is feasible.
- Whether voluntary coverage is offered.
- What participation requirements apply.
- What administrative support is available.
Start with clear objectives
A business owner might ask:
Do we want to provide a basic employer-funded benefit, offer employees optional coverage, or explore both?
Answering that question can help narrow the available options.
Employers should request actual proposals before assuming a particular benefit design or premium will be available.
13. What Should Employers Compare When Evaluating Group Life Insurance?
Not every group life insurance proposal is the same.
A lower premium does not automatically make one plan the better choice.
Employers should evaluate:
| Evaluation area | Questions to ask |
|---|---|
| Coverage design | What basic and optional amounts are available? |
| Eligibility | Which employees qualify? |
| Premiums | Who pays, and how are rates determined? |
| Guaranteed issue | What amounts may be available without individual medical underwriting? |
| Participation | Are minimum enrollment levels required? |
| Continuation | Are portability or conversion options available? |
| Benefit reductions | Does coverage reduce at certain ages or under other conditions? |
| Renewal | How can premiums or terms change? |
| Administration | How are enrollment, billing, and employee changes managed? |
| Employee support | What education and servicing resources are provided? |
Employers should also review the issuing insurer and relevant policy documents.
A thoughtful comparison considers cost, coverage, employee experience, and administrative requirements.
14. Measuring the Value of a Life Insurance Benefits Program
Employers may want to understand whether their benefits program is reaching employees effectively.
Useful measures can include:
- Eligible employee counts.
- Enrollment participation.
- Supplemental coverage elections.
- Employee awareness of available benefits.
- Completion of benefits education.
- Employee questions and feedback.
- Administrative issues during enrollment.
These measures can help identify areas where communication or plan design may need improvement.
However, participation alone does not establish that employees have sufficient life insurance.
An employee may elect the maximum available workplace coverage and still have financial responsibilities that exceed it.
Similarly, an employee who declines supplemental coverage may already have suitable individual insurance.
Program success should not be measured solely by how much insurance employees purchase.
Employee understanding and informed choice are also important.
15. How Turtelle Insurance Supports Employer Benefits Education
Turtelle Insurance is developing tools and resources intended to help employers and employees better understand life insurance protection.
For employers, Turtelle provides a pathway to explore group life insurance options and request information about potential programs.
For employees, the Family Protection Check provides an educational assessment of financial responsibilities and existing coverage.
The proprietary, rule-based Family Protection Score helps communicate the results of that assessment.
The score is not generated by AI.
It is an educational estimate, not an insurer's underwriting decision or a recommendation to purchase a particular amount of insurance.
These tools can help employees recognize that workplace life insurance is one component of their broader family protection.
Employers should not treat individual employee protection assessments as information required for ordinary benefits administration.
Any group insurance proposal, eligibility determination, coverage offer, or premium is subject to the applicable insurer's requirements and state licensing rules.
Turtelle is not an insurance carrier and does not issue or underwrite insurance policies.
16. A Practical Checklist for Employers
Before introducing or reviewing an employer-sponsored life insurance program, consider the following steps.
Define the purpose
Decide whether the primary objective is to provide foundational protection, offer optional coverage, or support broader employee financial well-being.
Understand workforce needs
Consider employee demographics, compensation structures, and feedback without unnecessarily collecting sensitive personal information.
Set a realistic budget
Determine what the organization can sustainably contribute.
Compare available plans
Review coverage, eligibility, premiums, continuation options, and administrative requirements.
Explain the benefit clearly
Provide accessible educational materials during onboarding and enrollment.
Support informed employee choices
Help employees understand that workplace coverage may not address every family's financial needs.
Review the program periodically
Reassess costs, employee understanding, enrollment processes, and plan suitability.
Coordinate with qualified professionals
Work with appropriately licensed insurance professionals and other advisers when evaluating plan arrangements, legal requirements, and employee communications.
Final Thoughts
Life insurance can be a meaningful addition to an employer's benefits strategy.
It helps address a financial risk that health insurance and retirement benefits do not directly cover: the loss of an employee's financial contribution after death.
For employers, the opportunity is not simply to add another benefit to a list.
It is to provide coverage that employees understand, can evaluate, and can use as part of their broader family financial planning.
A well-considered life insurance program balances affordability, eligibility, coverage design, administration, and employee education.
The most effective benefits strategy is not necessarily the one offering the greatest number of benefits. It is one that helps employees understand the protection available to them and make informed choices for their families.
Explore Employer Solutions
See how Turtelle helps employers manage group life insurance and help employees understand their protection.
Explore Employer SolutionsFrequently asked questions
Why should employers offer life insurance as an employee benefit?
Employer-sponsored life insurance can provide financial support to an employee's beneficiaries after a covered death. It complements health, disability, and retirement benefits and can contribute to a broader employee financial well-being strategy.
Is group life insurance expensive for small businesses?
Costs vary based on the insurer, workforce characteristics, coverage amounts, participation requirements, and plan design. Small businesses can explore employer-paid basic coverage, voluntary coverage, or a combination. Actual proposals are needed to determine cost and availability.
What is the difference between basic and voluntary life insurance?
Basic life insurance is commonly funded by the employer and provides a specified amount of coverage to eligible employees. Voluntary or supplemental life insurance generally allows employees to elect additional coverage, often paid through payroll deductions. Specific terms vary by plan.
Is employer-provided life insurance enough for employees?
Not necessarily. Employees have different family responsibilities, debts, savings, and income replacement needs. A fixed group benefit may provide meaningful protection without covering every employee's estimated financial needs.
What happens to employee life insurance when an employee leaves the company?
Employer-sponsored coverage may end when employment or plan eligibility ends. Some plans offer portability or conversion options, subject to deadlines and other requirements. Employees should review the official plan documents before leaving employment.