EMPLOYEE BENEFITS · GROUP LIFE INSURANCE
Group Life Insurance vs. Voluntary Life Insurance: Key Differences
Understand the differences between employer-paid basic group life insurance and employee-paid voluntary life insurance, including costs, coverage, underwriting, enrollment, and employee benefits.
Understanding Two Important Workplace Life Insurance Options
When employers evaluate employee benefits, life insurance is often considered alongside health coverage, disability insurance, retirement plans, and paid leave.
But life insurance itself can be structured in different ways.
Two common workplace arrangements are:
- Employer-paid basic group life insurance.
- Employee-paid voluntary or supplemental life insurance.
At first glance, these may seem like entirely different insurance products.
However, there is an important distinction.
Voluntary life insurance can itself be provided through a group insurance plan.
In many workplace benefits programs, the meaningful comparison is between employer-paid basic coverage and employee-paid voluntary coverage, rather than between group insurance and voluntary insurance as mutually exclusive categories.
Understanding this distinction helps employers compare proposals, communicate benefits accurately, and build programs that fit their workforce.
1. What Is Basic Group Life Insurance?
Basic group life insurance is life insurance offered through an employer-sponsored group plan.
The employer commonly pays the premium for a specified amount of coverage.
Eligible employees may receive coverage automatically or through an enrollment process, depending on the plan.
Coverage is often determined using one of two approaches.
Fixed-dollar coverage
An employer may provide the same basic death benefit to eligible employees.
For example, a plan might offer $50,000 in life insurance per eligible employee.
Salary-based coverage
Another employer may provide coverage based on a multiple of annual earnings.
For example, the benefit could equal one times an employee's annual base salary, subject to plan limits.
These are illustrative arrangements, not standard amounts that every carrier offers.
The actual coverage structure depends on the policy, employer agreement, and insurer.
Why employers offer basic coverage
Basic group life insurance can provide employees with a foundation of financial protection.
It may also help employers offer a more comprehensive benefits package.
However, the death benefit may not be sufficient to address every employee's family financial responsibilities.
2. What Is Voluntary Life Insurance?
Voluntary life insurance is coverage that employees can choose to purchase through an employer's benefits program.
It is frequently described as supplemental life insurance because it may provide coverage beyond the employer-paid basic benefit.
Employees typically pay some or all of the premium, often through payroll deductions.
Available coverage may be offered in:
- Fixed-dollar increments.
- Multiples of salary.
- Other amounts permitted under the plan.
For example, an employer might offer $50,000 of basic life insurance and allow eligible employees to elect additional voluntary coverage.
An employee could choose more coverage based on available options, affordability, and personal needs.
However, not every requested amount is automatically approved.
Some coverage amounts or enrollment circumstances may require evidence of insurability.
3. Group Life vs. Voluntary Life Insurance: Side-by-Side Comparison
The following table compares common employer-paid basic group life insurance arrangements with employee-paid voluntary group life insurance.
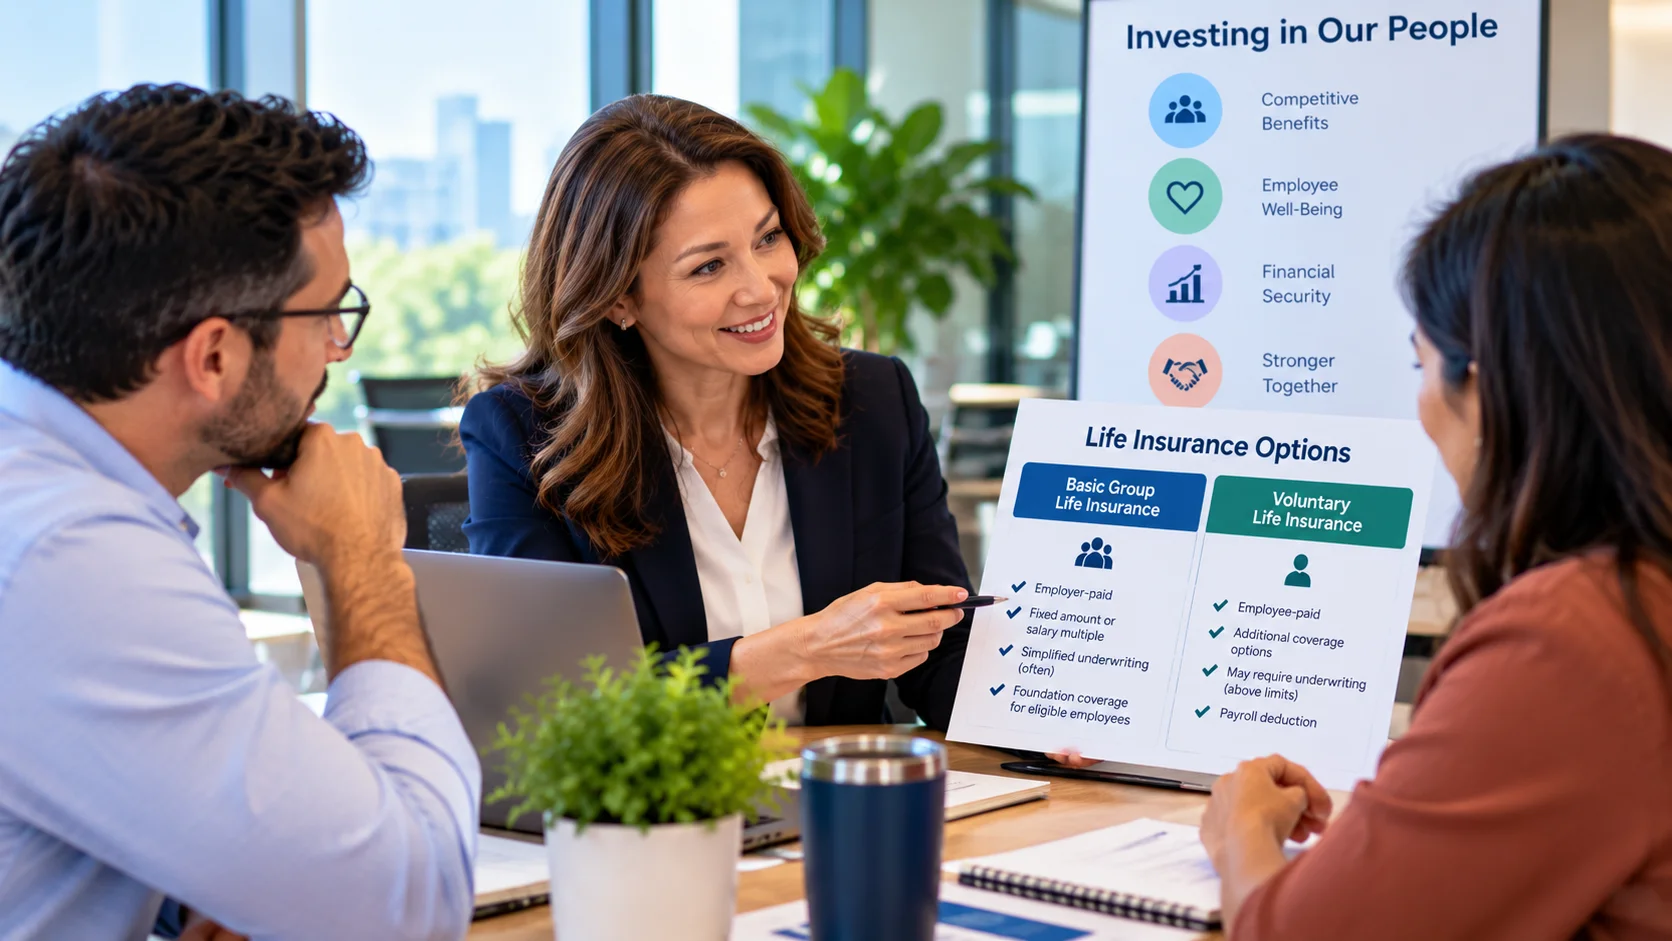
| Feature | Basic group life | Voluntary life |
|---|---|---|
| Who typically pays? | Employer | Employee |
| Employee choice | Often limited to the plan's basic benefit | Employee elects available coverage |
| Coverage amount | Fixed amount or salary multiple | Selected from plan options |
| Underwriting | May be simplified or waived for eligible basic coverage | May be required above guaranteed-issue limits |
| Enrollment | Often part of employee benefits eligibility | Usually requires an affirmative election |
| Payroll deductions | Usually none for employer-paid premiums | Commonly used |
| Employer budget impact | Direct premium expense | May involve limited or no direct premium contribution |
| Portability or conversion | Depends on plan | Depends on plan |
| Coverage duration | Often tied to employment eligibility | Often tied to employment eligibility |
These are general patterns. Actual terms vary by insurer, employer, policy, and state.
The most important distinction is that basic and voluntary coverage can work together.
They do not necessarily compete with one another.
4. Who Pays for the Insurance?
Cost responsibility is one of the clearest differences between basic and voluntary coverage.
Employer-paid basic life insurance
Under an employer-paid arrangement, the organization pays premiums for eligible employees.
For example, a company with 40 eligible employees may purchase a basic group life policy.
Its total cost depends on the carrier's pricing, covered population, benefit amounts, and other plan characteristics.
Employers should consider not only the initial premium but also how the cost may change at renewal.
Employee-paid voluntary life insurance
With voluntary coverage, employees generally pay for the additional amount they elect.
Payroll deduction can simplify payment administration.
However, the employer may still have responsibilities related to enrollment, eligibility, payroll, employee communications, and ongoing administration.
Voluntary insurance should not automatically be described as having no cost to the employer.
The organization may incur administrative expenses even when it does not contribute directly to premiums.
5. How Are Premiums Calculated?
Basic and voluntary group life insurance may use different pricing structures.
Basic group life premiums
Insurers may consider factors such as:
- Number of covered employees.
- Employee ages or age distribution.
- Coverage amounts.
- Industry or occupational characteristics.
- Plan participation.
- Other underwriting information.
The employer may receive an overall group rate or another pricing arrangement specified by the insurer.
Voluntary life premiums
Employee-paid coverage may use age-banded rates.
For example, a plan might have different premium rates for employees ages 30–34, 35–39, and 40–44.
The premium may also depend on the amount of insurance elected and other applicable factors.
Some voluntary plans use rates that increase as employees enter higher age bands.
Others may have different rate structures.
Employers should confirm whether rates are guaranteed for a period, how age changes affect premiums, and whether the insurer can change rates at renewal.
Why rate explanations matter
Employees may assume that a payroll deduction will remain unchanged indefinitely.
That may not be true.
Clear communication helps employees understand whether their premium can change because of age, elected coverage, or plan renewal.
6. What Is Guaranteed-Issue Life Insurance?
Guaranteed-issue provisions can be an important feature of workplace life insurance.
In certain group plans, eligible employees may obtain coverage up to a specified limit without providing individual medical evidence.
However, the term does not mean that every employee can obtain any amount of coverage at any time.
Guaranteed-issue availability may depend on:
- Employee eligibility.
- Enrollment during an approved period.
- Minimum participation requirements.
- Active-at-work conditions.
- Coverage maximums.
- Other plan provisions.
Example
Suppose a voluntary life plan provides a $100,000 guaranteed-issue limit for eligible employees during initial enrollment.
An employee electing $75,000 may qualify without individual medical underwriting if all applicable conditions are met.
An employee requesting $250,000 may need evidence of insurability for the amount above the guaranteed-issue limit, or for the entire amount under certain plan rules.
The insurer determines the actual requirements.
This example does not represent a specific Turtelle or carrier offering.
7. What Is Evidence of Insurability?
Evidence of insurability, often abbreviated EOI, is information an insurer may request to evaluate an applicant's eligibility for coverage.
It can include health questions and, depending on the circumstances, additional medical information.
EOI may be required when an employee:
- Requests coverage above a guaranteed-issue amount.
- Applies outside an initial enrollment opportunity.
- Increases coverage after a qualifying period.
- Requests coverage subject to other underwriting conditions.
The requirements vary by insurer and plan.
Why employers should explain EOI clearly
An employee may select an amount of voluntary coverage during enrollment and assume that the full amount is immediately effective.
But if EOI is required, the requested coverage may remain pending until the insurer approves it.
Employers should distinguish between:
- Coverage elected.
- Coverage pending underwriting.
- Coverage approved.
- Coverage currently in force.
This distinction helps reduce confusion about the benefits employees actually have.
8. How Much Coverage Should Employers Provide?
There is no single correct amount of basic group life insurance for every organization.
Employers may consider a fixed-dollar benefit, a salary multiple, or a combination of basic and voluntary coverage.
Example: Three hypothetical approaches
| Plan design | Basic coverage | Additional coverage |
|---|---|---|
| Approach A | $25,000 employer-paid | None |
| Approach B | One times salary employer-paid | Optional voluntary coverage |
| Approach C | $50,000 employer-paid | Optional voluntary coverage and eligible dependent coverage |
Each approach has different cost and administrative implications.
The best fit depends on the organization's objectives, employee population, available budget, and insurer eligibility rules.
A key limitation
A fixed basic benefit cannot be assumed to meet every employee's financial needs.
Employees have different incomes, debts, family structures, savings, and dependents.
Employers should avoid presenting a single group benefit amount as universally sufficient.
9. How Basic and Voluntary Life Insurance Can Work Together
A combined approach can provide a basic benefit while allowing employees to consider additional protection.
Hypothetical example
A company offers:
- $50,000 of employer-paid basic life insurance.
- Optional employee-paid voluntary life insurance.
An employee chooses $200,000 of supplemental coverage and receives the required approval.
The employee's total stated coverage would be:
| Coverage | Death benefit |
|---|---|
| Basic group life | $50,000 |
| Approved voluntary life | $200,000 |
| Combined stated coverage | $250,000 |
The total assumes both benefits cover the same insured employee, remain in force, and are payable under their terms.
This structure allows the employer to provide a foundation while offering employees more flexibility.
However, the employee should still consider whether $250,000 aligns with their family's financial needs.
10. Why Voluntary Life Insurance Is Not Always the Cheapest Option
Employees may assume that life insurance offered through work is automatically less expensive than individual insurance.
That is not always the case.
Group coverage can offer conveniences such as payroll deductions and simplified underwriting.
However, pricing depends on the plan and the applicant's circumstances.
An individually underwritten term life policy may offer a competitive rate for some applicants.
For others, voluntary group coverage may provide valuable access to insurance, particularly when individual underwriting would be more difficult.
Employees should compare:
- Premium amounts.
- Coverage duration.
- Renewal conditions.
- Portability and conversion rights.
- Underwriting requirements.
- Coverage limitations.
- Other policy features.
The least expensive initial premium does not necessarily represent the most suitable coverage.
11. What Happens When Employees Leave the Company?
Both basic and voluntary employer-sponsored life insurance may be tied to employment eligibility.
Coverage can end or change when an employee leaves the organization.
Some plans provide portability or conversion rights.
Portability
Portability may allow eligible employees to continue certain group coverage after leaving employment.
Conditions, costs, deadlines, and available amounts vary.
Conversion
Conversion may allow eligible employees to convert qualifying group coverage into an individual policy.
The resulting coverage and premium may differ from the original group plan.
Why this matters
An employee who has substantial voluntary life insurance through work may assume the coverage will remain available after changing jobs.
That assumption can create a potential protection gap.
Employers should clearly communicate coverage termination dates and continuation options.
Official plan documents and insurer materials should govern these explanations.
12. Employee Enrollment and Participation
Basic and voluntary life insurance may have different enrollment processes.
Employer-paid basic coverage may be automatic for eligible employees, depending on plan terms.
Voluntary coverage generally requires an employee election.
Enrollment opportunities may include:
- Initial eligibility.
- New-hire enrollment.
- Annual enrollment.
- Certain qualifying life events.
- Other periods permitted by the plan.
Participation requirements
Some group insurance arrangements require a minimum number or percentage of eligible employees to participate.
Requirements may differ for employer-paid and voluntary plans.
A small employer may therefore have different options from a larger organization.
Employers should confirm participation requirements before promising that a particular plan design will be available.
13. Tax Considerations for Employer-Provided Life Insurance
Tax treatment is another important consideration.
Under federal tax rules, certain employer-provided group-term life insurance coverage may qualify for favorable treatment.
However, the value of employer-provided group-term life insurance exceeding $50,000 can generally create taxable imputed income for an employee, subject to applicable rules and exceptions.
For example, if an employer provides $100,000 of qualifying group-term life insurance, the employee may have taxable imputed income associated with the coverage above the applicable exclusion.
The calculation is not simply based on the employer's actual premium.
Specific IRS rules determine the taxable cost.
What employers should do
Employers should coordinate with payroll and qualified tax advisers to address:
- Imputed income calculations.
- Payroll reporting.
- Employee contributions.
- Applicable exceptions.
- Other federal, state, and local requirements.
Tax treatment can differ depending on the insurance arrangement.
This article provides general education, not tax advice.
14. Administrative Responsibilities for Employers
Offering life insurance through a workplace plan can involve ongoing administration.
Typical responsibilities may include:
- Determining employee eligibility.
- Managing enrollment.
- Communicating benefit amounts.
- Collecting employee elections.
- Coordinating payroll deductions.
- Reporting employee changes.
- Maintaining beneficiary information where applicable.
- Communicating coverage termination.
- Supporting employees with insurer contact information.
The exact responsibilities depend on the plan and service arrangements.
Employers should also consider applicable employee-benefit laws, including ERISA where relevant.
Documentation matters
Official policy documents, certificates of insurance, and plan materials should be available to employees as required.
Marketing summaries should not contradict the governing documents.
Clear documentation can help reduce misunderstandings about coverage.
15. How to Choose Between Basic and Voluntary Life Insurance
The decision is not necessarily either-or.
Employers can evaluate whether one arrangement or a combination better fits their goals.
Consider employer-paid basic coverage when:
- The organization wants to provide a foundational benefit.
- The employer has a sustainable benefits budget.
- The goal is to make basic coverage broadly available to eligible employees.
- The plan can be administered effectively.
Consider voluntary coverage when:
- Employees have varying financial protection needs.
- The employer wants to offer additional choice.
- Employees can pay for elected coverage.
- Suitable insurer options and enrollment arrangements are available.
Consider both when:
- The employer wants to provide basic protection.
- Employees may benefit from additional coverage options.
- The organization can manage the associated administration.
- The overall program fits the budget and workforce.
Actual plan availability and terms must be confirmed with the insurer.
16. Why Employee Education Matters as Much as Plan Design
A well-designed insurance program may still be poorly understood.
Employees may not know:
- How much basic life insurance they receive.
- Whether they need to enroll.
- How much voluntary coverage costs.
- Whether EOI is required.
- Who their beneficiaries are.
- Whether coverage continues after employment.
- How workplace insurance relates to their broader family needs.
These questions deserve clear answers.
Practical education strategies
Employers can provide:
- Simple coverage comparison charts.
- Enrollment guides.
- Explanations of guaranteed-issue limits.
- Examples of premium calculations.
- Information about beneficiary updates.
- Guidance on portability and conversion.
- Access to educational protection assessment tools.
Education should help employees make informed decisions rather than pressure them to purchase additional insurance.
17. How Turtelle Helps Employers and Employees
Turtelle Insurance is an insurance technology platform focused on helping people better understand life insurance protection.
For employers, Turtelle provides a pathway to explore group life insurance options and request information about potential employee benefits programs.
For employees, the Family Protection Check helps estimate financial protection needs using information entered by the user.
Turtelle's proprietary, rule-based Family Protection Score helps communicate the assessment results.
The score is not AI-generated.
These tools are intended to support education and help employees recognize how existing coverage relates to their estimated financial responsibilities.
Turtelle's assessments do not determine insurance eligibility, establish final premiums, or guarantee that a particular policy is suitable.
Employers should not require access to employees' personal household financial assessments as part of ordinary benefits administration.
Any insurance program, coverage amount, underwriting decision, and premium depends on the issuing insurer and applicable requirements.
Turtelle is not an insurance carrier and does not issue or underwrite policies.
18. Employer Checklist: Comparing Basic and Voluntary Life Insurance
Before selecting or renewing a workplace life insurance program, review the following questions.
- [ ] What is the employer's objective for offering life insurance?
- [ ] How much basic coverage will the employer provide?
- [ ] Who will pay for the basic coverage?
- [ ] Will employees have voluntary coverage options?
- [ ] What coverage amounts are available?
- [ ] What are the guaranteed-issue limits?
- [ ] When is evidence of insurability required?
- [ ] How are premiums calculated?
- [ ] Can premiums change with age or renewal?
- [ ] What participation requirements apply?
- [ ] What happens when employees leave?
- [ ] Are portability and conversion available?
- [ ] What payroll and administrative responsibilities apply?
- [ ] Have tax and employee-benefit compliance issues been reviewed?
- [ ] Are employee education materials clear and accurate?
A structured comparison can help employers choose a program that aligns with organizational goals and employee needs.
Final Thoughts
Basic group life insurance and voluntary life insurance serve related but different purposes within an employee benefits strategy.
Employer-paid basic coverage can provide foundational protection.
Employee-paid voluntary coverage can offer eligible employees additional choices.
Because voluntary life insurance is often itself group insurance, the most useful comparison focuses on funding, enrollment, coverage options, underwriting, and continuation rights.
For employers, the strongest approach is not necessarily the one with the highest coverage limits or the lowest initial premium.
It is the approach that balances affordability, administration, employee choice, and clear communication.
A meaningful life insurance benefits program helps employees understand what protection they have, what choices are available, and how those benefits fit into their family's broader financial picture.
Explore Employer Solutions
See how Turtelle helps employers manage group life insurance and help employees understand their protection.
Explore Employer SolutionsFrequently asked questions
What is the difference between basic group life and voluntary life insurance?
Basic group life insurance is commonly employer-paid and provides a specified benefit to eligible employees. Voluntary life insurance generally allows employees to purchase additional coverage, often through payroll deductions. Both may be provided under group insurance arrangements.
Is voluntary life insurance paid by the employer or employee?
Voluntary life insurance is typically employee-paid, although cost-sharing arrangements can vary. The employer may still have enrollment, payroll, and administrative responsibilities.
Does voluntary life insurance require a medical examination?
Not always. Some plans provide guaranteed-issue amounts for eligible employees during specified enrollment periods. Additional amounts or later applications may require evidence of insurability, depending on the insurer and plan.
Can employees have both basic and voluntary life insurance?
Yes. Many workplace plans offer employer-paid basic coverage alongside optional employee-paid supplemental coverage. Both can contribute to the employee's total life insurance protection, subject to policy terms.
Does voluntary life insurance continue when an employee changes jobs?
Not automatically. Coverage may end when employment or eligibility ends. Some plans offer portability or conversion options, subject to eligibility, deadlines, premiums, and other conditions.