EMPLOYEE BENEFITS · ENROLLMENT
Understanding Employee Life Insurance Participation and Enrollment
A practical guide for employers to improve life insurance enrollment, explain participation requirements, simplify employee communication, and support informed coverage decisions.
Introduction: Offering Life Insurance Is Only the Beginning
Employers invest time and resources in designing employee benefits programs.
They compare insurance providers, review costs, select coverage amounts, and establish eligibility rules.
Yet an important question remains after a life insurance plan is introduced:
Do employees understand their benefits well enough to make informed enrollment decisions?
A company may offer valuable life insurance coverage, but employees may overlook enrollment deadlines, misunderstand coverage amounts, or assume they are automatically enrolled in benefits that actually require an election.
Others may decline voluntary coverage because they do not understand its purpose or how it differs from employer-paid basic life insurance.
For employers, successful enrollment is not simply about achieving a high participation percentage.
It is about ensuring eligible employees receive accurate information, understand their options, and have a reasonable opportunity to make decisions that fit their circumstances.
This guide explains how employee life insurance participation and enrollment work, why employees sometimes miss important opportunities, and how employers can build a clearer, more effective enrollment experience.
1. What Is Employee Life Insurance Enrollment?
Employee life insurance enrollment is the process through which eligible employees receive or elect coverage under an employer-sponsored life insurance arrangement.
Depending on the plan, enrollment may involve:
- Confirming employee eligibility.
- Providing required personal information.
- Accepting employer-paid basic coverage, if an election is required.
- Choosing voluntary or supplemental coverage.
- Reviewing premium deductions.
- Naming beneficiaries.
- Providing evidence of insurability when required.
- Receiving confirmation of coverage and its effective date.
Not every employee must complete every step.
For example, an employer-paid basic life insurance plan may automatically cover eligible employees, subject to plan conditions.
Voluntary life insurance generally requires an employee election.
Why enrollment matters
A benefit listed in an employee handbook is not necessarily active for every employee.
Coverage depends on the terms of the insurance plan, employee eligibility, enrollment requirements, and any applicable underwriting approval.
Employers should avoid telling employees they are insured until coverage has actually become effective under the plan.
2. Understanding Employee Participation
Employee participation refers to the proportion of eligible employees who are enrolled in a particular insurance benefit.
Participation can be especially important for group insurance arrangements.
Some insurers establish minimum participation requirements as a condition of offering coverage.
Others may apply different rules depending on whether premiums are paid by the employer or employees.
Participation example
Consider a hypothetical business with 50 employees eligible for voluntary life insurance.
If 30 employees elect coverage:
Participation rate = 30 ÷ 50 × 100 = 60%
This is an illustrative calculation.
It does not mean 60% is a required or recommended participation threshold.
Actual minimums vary by insurer, plan design, contribution structure, and other underwriting requirements.
Participation is not the same as employee engagement
An employee may attend an educational session, review plan materials, and decide not to purchase voluntary life insurance.
That employee has participated in the decision-making process even though they did not enroll.
Employers should distinguish between informed employee engagement and insurance enrollment rates.
3. Why Do Insurers Have Participation Requirements?
Group insurance relies on the characteristics and participation of an eligible employee population.
Insurers may use participation requirements to manage the risk associated with employees choosing coverage.
For example, if only employees who believe they are likely to need coverage enroll, the insured group may differ significantly from the broader eligible workforce.
This concern is commonly associated with adverse selection.
Minimum participation requirements are one way insurers may manage group underwriting risk.
However, there is no universal participation requirement that applies to every employer-sponsored life insurance policy.
Employer-paid and voluntary plans may differ
A plan where the employer pays the entire premium may have different participation rules from a plan where employees pay premiums through payroll deductions.
Some employer-paid arrangements require coverage for all eligible employees, subject to policy terms.
Some voluntary plans require a specified number or percentage of eligible employees to enroll.
Employers should obtain the applicable participation rules directly from the insurer or plan administrator.
4. Basic Life Insurance vs. Voluntary Life Insurance Enrollment
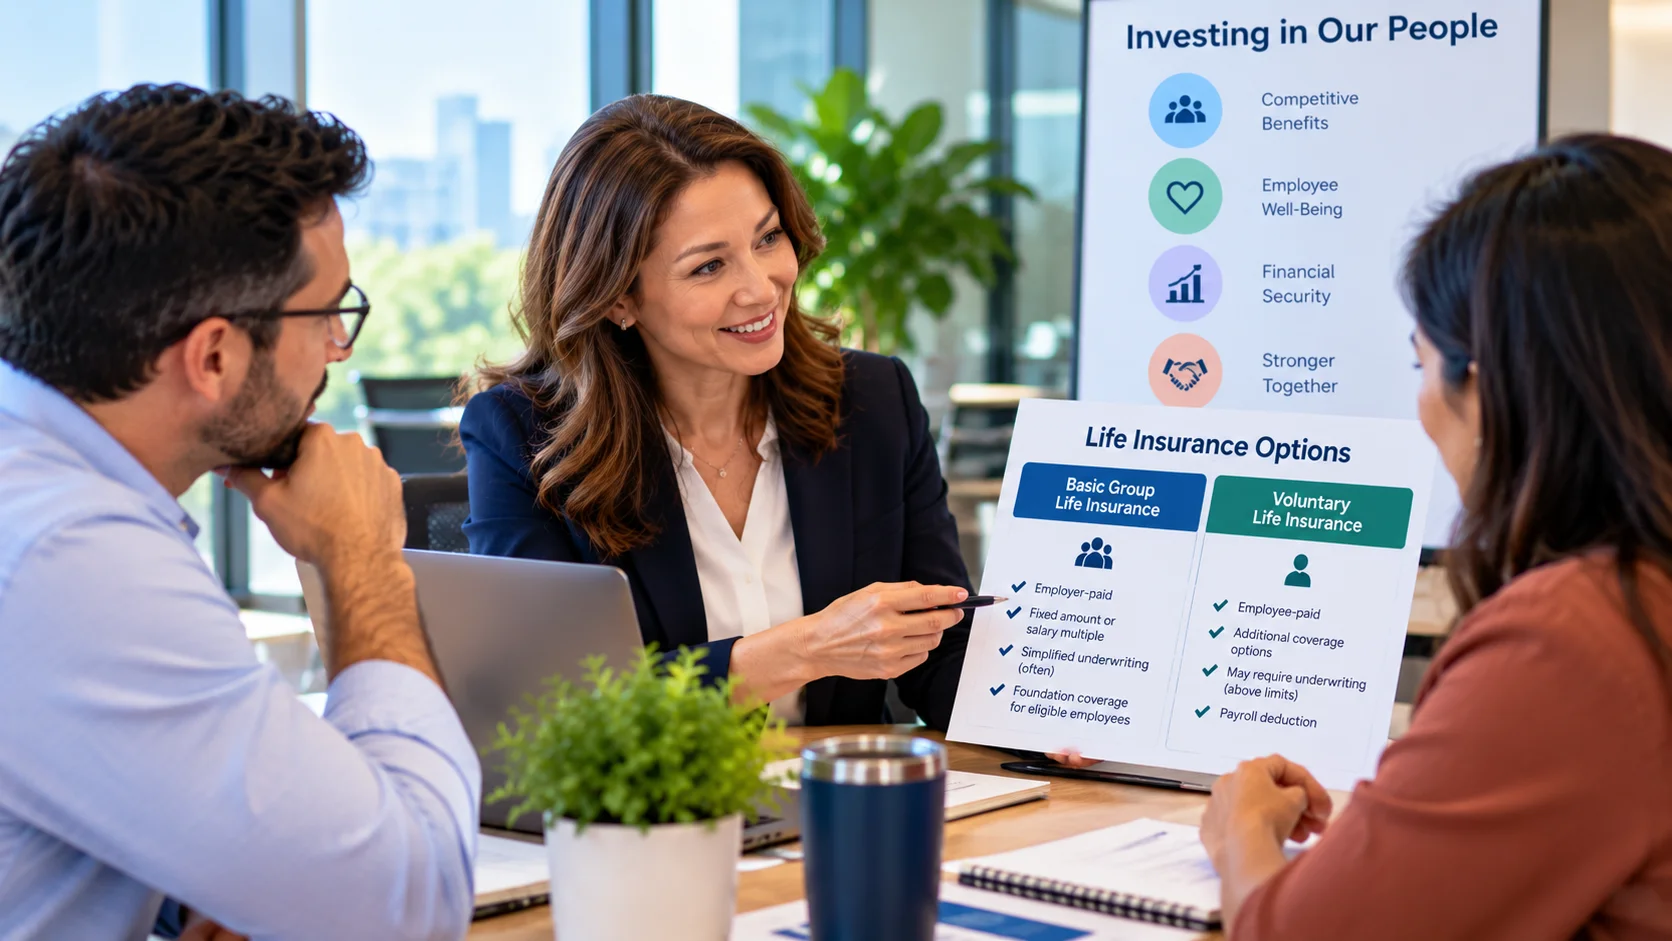
Understanding the difference between these two types of benefits is essential.
Basic employer-paid life insurance
Basic life insurance provides a specified death benefit for eligible employees, with premiums generally paid by the employer.
Depending on the plan, enrollment may be automatic once an employee satisfies eligibility conditions.
Employees may still need to provide beneficiary information or complete administrative forms.
Voluntary life insurance
Voluntary life insurance allows eligible employees to elect coverage, usually at their own expense.
The employee may choose from available coverage amounts, subject to plan limits and underwriting rules.
Voluntary enrollment may involve:
- Selecting an amount of coverage.
- Reviewing premiums.
- Authorizing payroll deductions.
- Naming beneficiaries.
- Completing evidence-of-insurability requirements, if applicable.
Comparison
| Feature | Basic life insurance | Voluntary life insurance |
|---|---|---|
| Premium payer | Usually employer | Usually employee |
| Enrollment | May be automatic | Usually requires election |
| Coverage amount | Defined by plan | Employee selects within plan limits |
| Underwriting | Depends on plan | May apply |
| Payroll deduction | Usually none for basic employer-paid premiums | Common |
| Beneficiary designation | Important | Important |
| Coverage effective date | Subject to plan conditions | Subject to election, approval, and plan conditions |
Clear explanations of these differences can help employees avoid incorrect assumptions about their coverage.
5. Why Employees Sometimes Do Not Enroll
Low participation does not always mean employees are uninterested in financial protection.
Employees may face practical barriers.
Lack of understanding
Insurance terminology can be confusing.
Terms such as guaranteed issue, evidence of insurability, portability, and conversion may be unfamiliar.
Competing financial priorities
Employees may be managing rent, mortgages, childcare, student loans, or other expenses.
Additional insurance premiums may not fit their current budgets.
Incorrect assumptions about existing coverage
Some employees believe their employer-paid benefit is sufficient without reviewing the actual death benefit.
Others assume workplace coverage automatically continues after they leave their employer.
Complicated enrollment processes
Multiple forms, unclear instructions, or difficult digital systems can discourage completion.
Missed deadlines
Employees may overlook enrollment communications or assume they can sign up at any time.
Uncertainty about medical underwriting
Some employees avoid applying because they believe a medical examination is always required.
In reality, underwriting requirements vary by plan, coverage amount, and enrollment circumstances.
Employers can address many of these barriers through clear, timely, and accessible communication.
6. When Can Employees Enroll in Life Insurance?
Enrollment opportunities depend on the employer's plan and insurer rules.
Common enrollment situations include the following.
New-hire enrollment
New employees may become eligible after satisfying applicable waiting periods and other plan conditions.
Employers should explain the deadline for submitting elections.
Annual open enrollment
Some employers provide an annual opportunity to review and update benefit elections.
However, employees should not assume voluntary life insurance can always be added or increased without underwriting during annual open enrollment.
Qualifying life events
Certain plans permit election changes following specified events, such as marriage or the birth of a child.
The events that permit changes and the associated deadlines depend on plan terms and applicable rules.
A qualifying event under a health insurance plan does not automatically create identical rights under a life insurance plan.
Special enrollment opportunities
An insurer may provide a designated enrollment campaign or other opportunity under particular conditions.
Employees should verify whether guaranteed-issue provisions apply.
7. What Is Guaranteed-Issue Life Insurance?
Guaranteed-issue coverage is an important concept in group life insurance enrollment.
Some plans allow eligible employees to obtain coverage up to a specified limit without providing individual medical evidence.
This is commonly available only when applicable conditions are satisfied.
Example
Suppose a hypothetical voluntary life insurance plan provides a $100,000 guaranteed-issue limit for eligible new employees who enroll on time.
An employee who elects $75,000 may qualify without additional individual medical underwriting if all applicable plan requirements are met.
An employee who requests $200,000 may need to provide evidence of insurability for coverage above the guaranteed-issue limit.
The insurer may approve, decline, or otherwise determine the amount requiring underwriting.
This example is hypothetical and does not represent a specific carrier offering.
Important limitations
Guaranteed issue may depend on:
- Employee eligibility.
- Timely enrollment.
- Active-at-work requirements.
- Age and coverage limits.
- Minimum participation.
- Other policy provisions.
Employers should never describe guaranteed issue as unconditional coverage.
8. What Is Evidence of Insurability?
Evidence of insurability, often abbreviated EOI, is information an insurer requests to evaluate an applicant's eligibility for certain insurance coverage.
EOI may involve health questions, medical history, or other underwriting information.
Depending on the insurer and coverage amount, additional requirements may apply.
When might EOI be required?
Common situations include:
- Requesting coverage above a guaranteed-issue limit.
- Applying after an initial enrollment deadline.
- Increasing existing coverage.
- Electing certain spouse or dependent coverage.
- Other situations specified by the insurer.
Why employers should explain EOI
Employees may believe their selected coverage amount is active immediately after submitting an election.
But if underwriting approval is required, the requested amount may not become effective until the insurer approves it and all applicable conditions are met.
Employers should clearly distinguish between:
Coverage requested, coverage approved, and coverage effective.
These are not always the same.
9. How Employers Can Communicate Enrollment Clearly
Good enrollment communication begins before the enrollment deadline.
Employees need enough time to review the benefit and ask questions.
Use simple language
Instead of saying:
"Employees may elect supplemental coverage subject to EOI."
Explain:
"You may be able to purchase additional life insurance. Depending on the amount you choose, the insurer may ask you to provide health information before approving the coverage."
Explain the purpose of the benefit
Life insurance can help beneficiaries manage financial responsibilities after an insured person's death.
Potential uses of death benefits include:
- Housing expenses.
- Everyday living costs.
- Outstanding debts.
- Childcare.
- Education-related expenses.
- Other family financial needs.
The exact benefit is determined by the insurance contract.
Provide written examples
Illustrative coverage examples can help employees understand the differences between basic and voluntary benefits.
However, examples should not be presented as actual quotes or guarantees.
Make deadlines prominent
Employees should know:
- When enrollment begins.
- When enrollment ends.
- What forms must be completed.
- Whether underwriting is required.
- Where to obtain assistance.
Important information should be available in writing.
10. Build an Employee-Friendly Enrollment Process
An effective process should make each step understandable.
Step 1: Confirm eligibility
Employees should know when they become eligible and whether any waiting period applies.
Step 2: Explain existing coverage
Show employees the amount of basic life insurance available through the employer.
Step 3: Present voluntary options
Explain available coverage amounts, employee premiums, and any spouse or dependent options.
Step 4: Clarify underwriting
Identify guaranteed-issue limits and circumstances requiring evidence of insurability.
Step 5: Explain payroll deductions
Show how employee-paid premiums are collected and when deductions are expected to begin.
Step 6: Collect beneficiary information
Explain the importance of naming and updating beneficiaries.
Step 7: Confirm elections
Provide a record of what the employee selected.
Step 8: Confirm effective coverage
Communicate coverage status and effective dates based on insurer confirmation and plan terms.
An employee should not have to guess whether an election was received or whether requested coverage has been approved.
11. The Importance of Beneficiary Designations
Beneficiary information is a critical part of life insurance administration.
A beneficiary is the person or entity designated to receive the death benefit, subject to applicable policy and legal requirements.
Employees should be encouraged to review their beneficiary designations.
Common reasons for updates
- Marriage.
- Divorce.
- Birth or adoption of a child.
- Death of a previously named beneficiary.
- Changes in family circumstances.
Employers should explain how employees can update their designations and where official records are maintained.
Special rules may apply in certain circumstances, including situations involving minors, trusts, or spousal rights.
Employees with complex circumstances may benefit from legal or financial guidance.
12. How Digital Enrollment Can Help
Digital tools may simplify the enrollment experience.
Depending on the system, employers may be able to:
- Display plan information.
- Collect elections.
- Provide premium illustrations.
- Capture beneficiary details.
- Track enrollment completion.
- Coordinate underwriting requests.
- Maintain administrative records.
Benefits of digital enrollment
A well-designed system can reduce repetitive paperwork and make it easier for employees to access information.
It may also help HR administrators identify incomplete elections or missing required information.
Digital enrollment still requires careful oversight
Employers should verify that systems accurately reflect insurer requirements and effective dates.
Sensitive employee information must be handled appropriately.
Access to medical underwriting information should be restricted according to applicable privacy and legal requirements.
A digital process should not create the impression that coverage is approved before the insurer confirms it.
13. Measuring Enrollment Effectiveness
Employers can review enrollment performance to identify communication and administrative improvements.
Useful measures may include:
Eligible employee count
How many employees qualify for the benefit?
Enrollment completion rate
How many eligible employees completed the required enrollment process?
Voluntary participation rate
What percentage of eligible employees elected voluntary coverage?
Missed enrollment deadlines
How many employees failed to submit elections on time?
Incomplete applications
How many applications required follow-up?
Employee questions
Which topics generated the most confusion?
Administrative corrections
How frequently were payroll or eligibility records corrected?
Employers should evaluate these measures in context.
A high enrollment rate does not automatically indicate that every employee selected appropriate coverage.
Likewise, a lower rate may reflect informed decisions based on individual needs and budgets.
14. How to Calculate Participation Rates
Participation calculations should use the correct eligible population.
Example: Voluntary life insurance
A company has:
- 120 total employees.
- 100 employees eligible for voluntary life insurance.
- 65 eligible employees enrolled.
Participation rate:
65 ÷ 100 × 100 = 65%
The denominator is 100 eligible employees, not the entire workforce of 120.
Example: Enrollment completion
Suppose 90 eligible employees were required to submit enrollment information.
If 81 completed the process:
81 ÷ 90 × 100 = 90%
This is an enrollment completion rate, which may differ from the percentage who purchased voluntary coverage.
Employers should define each metric consistently.
15. Avoiding Common Enrollment Mistakes
Even established employers can experience enrollment problems.
Mistake 1: Assuming everyone understands basic coverage
Employees may not know whether they are automatically covered or how much the plan provides.
Better approach: Explain basic coverage separately from voluntary coverage.
Mistake 2: Treating every enrollment period the same
Guaranteed-issue rules may differ between initial enrollment, annual enrollment, and later requests.
Better approach: Confirm the specific rules for each enrollment opportunity.
Mistake 3: Failing to explain effective dates
Employees may assume requested coverage starts immediately.
Better approach: Explain insurer approval and effective-date conditions.
Mistake 4: Overlooking beneficiary updates
Employees may retain outdated designations.
Better approach: Provide regular reminders about beneficiary reviews.
Mistake 5: Communicating only through email
Some employees may miss important messages.
Better approach: Use appropriate combinations of email, meetings, employee portals, and written guides.
Mistake 6: Measuring success only by enrollment percentage
Participation numbers alone do not measure employee understanding.
Better approach: Review employee questions, completion issues, and communication effectiveness.
16. Life Insurance Enrollment for Remote and Hybrid Employees
Remote and hybrid work arrangements can create additional communication challenges.
Employees may work across locations, time zones, and schedules.
Employers should make benefit information accessible without requiring attendance at a single in-person meeting.
Practical strategies
- Provide recorded enrollment presentations.
- Offer written guides and frequently asked questions.
- Schedule virtual information sessions.
- Provide clear contact information.
- Make deadlines visible across communication channels.
- Offer accessible enrollment alternatives where appropriate.
Employers should also confirm whether employees working in different states affect plan eligibility, administration, or applicable requirements.
17. Supporting Employees Through Life Changes
Employees' insurance needs can change significantly over time.
A person who enrolled when single may later marry, purchase a home, or have children.
Another employee may experience divorce, changes in income, or new caregiving responsibilities.
These events may affect the employee's financial protection needs.
Employer communication opportunities
Employers can encourage employees to review coverage during:
- Annual benefits enrollment.
- New-hire orientation.
- Major life changes.
- Benefits education campaigns.
- Periodic financial well-being initiatives.
Employers should not assume that every life event permits an immediate insurance election change.
Employees must follow applicable plan enrollment and underwriting rules.
18. Why Workplace Life Insurance May Not Be Enough
Employer-sponsored life insurance can be an important financial benefit.
However, the amount provided through work may not fully address an employee's household financial responsibilities.
Consider a hypothetical employee who earns $90,000 annually and receives $50,000 of employer-paid basic life insurance.
That employee may have:
- A mortgage.
- Two dependent children.
- Household expenses.
- Outstanding debts.
- Future education costs.
A $50,000 death benefit could provide meaningful assistance but may not replace years of income.
The appropriate amount of insurance depends on the employee's circumstances.
The employer's educational role
Employers can help employees understand the coverage they have.
They can also explain that personal life insurance may be available outside the workplace.
However, employers should avoid presenting a single coverage amount as appropriate for every employee.
19. How Turtelle Supports Life Insurance Education
Turtelle Insurance focuses on helping individuals and families better understand financial protection.
For employees reviewing workplace benefits, Turtelle's educational approach can help them consider how existing life insurance relates to broader household responsibilities.
The Family Protection Check provides a structured way to review financial protection needs.
Turtelle's proprietary, rule-based Family Protection Score helps communicate the results of an assessment based on user-provided information.
The score is not AI-generated.
Employees may use educational tools to explore questions such as:
- How much life insurance coverage do I currently have?
- What financial responsibilities depend on my income?
- Could my household face a protection gap?
- Should I explore additional life insurance?
These tools are educational and do not determine underwriting eligibility, guarantee rates, or replace individualized insurance advice.
Employers should respect employee privacy and should not require access to employees' personal financial assessment results as part of ordinary benefits administration.
Actual insurance availability, pricing, and issuance depend on applicable insurer requirements.
Turtelle does not issue or underwrite insurance policies.
20. Employer Enrollment Checklist
Before opening a life insurance enrollment period, employers can review the following:
- [ ] Confirm eligible employee groups.
- [ ] Verify participation requirements with the insurer.
- [ ] Identify employer-paid and voluntary coverage options.
- [ ] Confirm enrollment dates and deadlines.
- [ ] Review guaranteed-issue limits.
- [ ] Explain evidence-of-insurability requirements.
- [ ] Prepare clear premium information.
- [ ] Communicate coverage effective-date rules.
- [ ] Provide beneficiary designation instructions.
- [ ] Confirm payroll deduction procedures.
- [ ] Offer employee education resources.
- [ ] Provide accessible enrollment methods.
- [ ] Establish a process for incomplete applications.
- [ ] Coordinate approval and coverage confirmation.
- [ ] Maintain appropriate employee data safeguards.
- [ ] Review enrollment results after the period closes.
This checklist can help HR teams organize enrollment and reduce preventable confusion.
Final Thoughts
Employee life insurance enrollment should be more than a form employees complete during benefits season.
It is an opportunity to help people understand financial protection, evaluate available coverage, and make decisions for themselves and their families.
Employers can improve the experience by clearly explaining eligibility, coverage amounts, premiums, guaranteed-issue provisions, underwriting requirements, and enrollment deadlines.
They should also make it easy for employees to confirm whether their elections were received and when coverage becomes effective.
The strongest enrollment programs focus not simply on how many employees sign up, but on how confidently and accurately employees understand the benefits available to them.
Explore Employer Solutions
See how Turtelle helps employers manage group life insurance and help employees understand their protection.
Explore Employer SolutionsFrequently asked questions
What is employee life insurance participation?
Employee life insurance participation is the percentage of eligible employees enrolled in a particular life insurance benefit. Some insurers establish minimum participation requirements for group plans, but these vary by insurer and coverage arrangement.
Are employees automatically enrolled in employer-provided life insurance?
Some employer-paid basic life insurance plans automatically cover eligible employees, subject to plan requirements. Voluntary or supplemental life insurance generally requires an employee election. Employers should confirm the rules for each plan.
Can employees enroll in life insurance after open enrollment?
Possibly. Some plans permit late applications or changes following specified life events, but underwriting may be required. Enrollment opportunities and deadlines depend on the insurer and plan.
What happens when employees request more than the guaranteed-issue amount?
The insurer may require evidence of insurability before approving the additional coverage. Submitting an election does not automatically mean the requested amount is effective.
How can employers improve life insurance enrollment?
Employers can provide simple benefits guides, explain coverage amounts and premiums, communicate deadlines, offer accessible enrollment methods, and help employees confirm their elections and coverage status.