EMPLOYEE BENEFITS · COVERAGE CONTINUATION
What Happens to Employee Life Insurance When Someone Leaves the Company?
A practical employer's guide to group life insurance termination, portability, conversion, employee offboarding, and helping departing employees avoid unexpected coverage gaps.
Introduction: Leaving a Job Can Mean Losing Life Insurance
When an employee leaves a company, there are many details to manage.
The employer may need to process final payroll, coordinate benefits termination, recover company equipment, and provide employment documents.
The employee may be focused on starting a new job, managing a career transition, or adjusting to retirement.
During this process, one important financial protection issue is sometimes overlooked:
What happens to the employee's life insurance coverage?
Many employees receive life insurance through their workplace. Some have employer-paid basic coverage, while others purchase voluntary or supplemental coverage through payroll deductions.
But employer-sponsored life insurance is often tied to employment eligibility.
When employment ends, coverage may terminate, and the employee may need to take action to maintain insurance protection.
Depending on the group policy, some employees may qualify for portability or conversion options.
Others may need to explore a new individual life insurance policy.
For employers, understanding these differences is essential to communicating benefits accurately and helping departing employees avoid unexpected coverage gaps.
1. Does Employee Life Insurance End When Someone Leaves a Company?
In many cases, yes.
Employer-sponsored group life insurance generally depends on the employee meeting the plan's eligibility requirements.
When an employee resigns, retires, is terminated, or otherwise becomes ineligible, coverage may end under the group policy.
However, the exact termination date is not universal.
Depending on the plan, coverage may end:
- On the employee's last day of employment.
- At the end of the month in which employment ends.
- After another period specified by the group policy.
- At a different time because of applicable continuation provisions.
Some plans also contain special provisions for approved leave, disability, retirement, or other circumstances.
Why employers should verify the actual termination date
An employer should not assume every employee's life insurance ends on the same date as medical coverage.
Different benefits may have different termination rules.
The group life insurance policy and related plan documents determine the applicable coverage conditions.
Employers should confirm the relevant date with the insurer or benefits administrator before communicating it to the employee.
2. What Types of Workplace Life Insurance May Be Affected?
Employees may have more than one type of workplace life insurance.
Each coverage component may have different termination and continuation provisions.
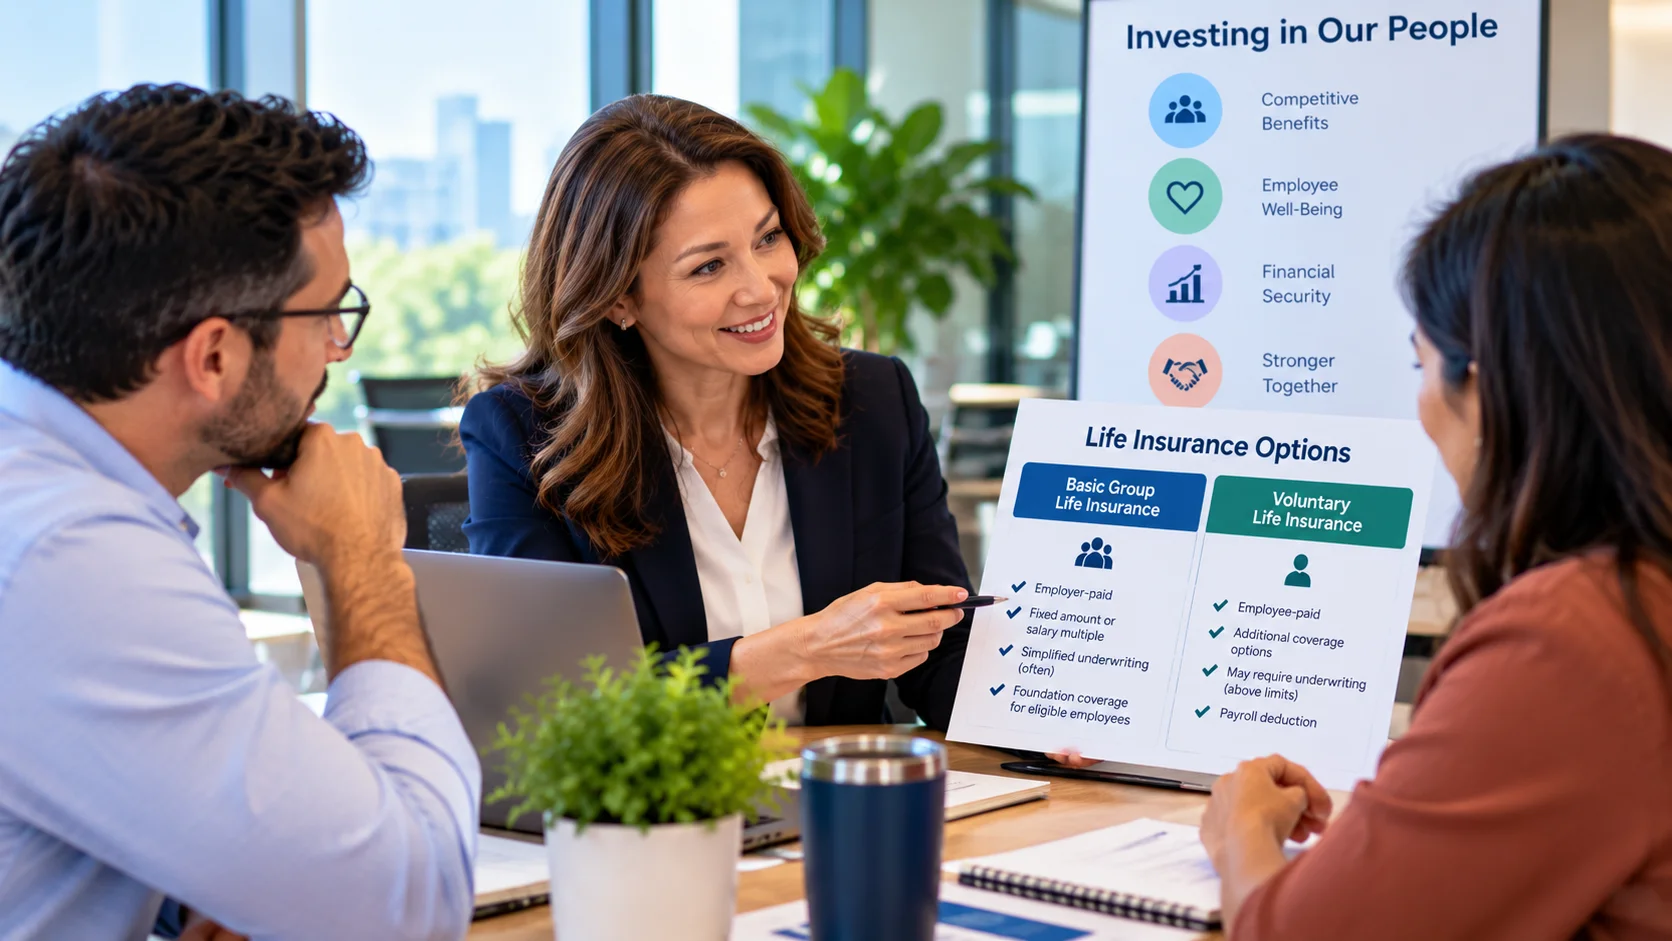
Employer-paid basic life insurance
This is coverage provided to eligible employees, with premiums generally paid by the employer.
The benefit may be a fixed amount or based on employee earnings.
When employment eligibility ends, basic coverage commonly terminates unless another policy provision applies.
Voluntary life insurance
Voluntary life insurance allows eligible employees to elect additional coverage, typically paid through payroll deductions.
Although employees pay the premiums, the insurance may still be part of an employer-sponsored group arrangement.
Employee-paid does not necessarily mean individually owned or automatically portable.
Supplemental life insurance
Supplemental coverage may increase the amount of insurance available beyond an employer's basic benefit.
It may have separate continuation rules or coverage limits.
Spouse and dependent life insurance
Some group plans allow employees to insure eligible spouses or dependents.
These benefits may also end when the employee loses eligibility.
Employers should explain whether continuation options are available for each covered person.
3. Why Workplace Life Insurance Is Different From Individual Life Insurance
Understanding ownership and eligibility is important.
Employer-sponsored group life insurance
Group coverage is provided through an arrangement associated with an employer or other eligible group.
The employee's eligibility may depend on employment status and other plan requirements.
Coverage amounts, premiums, and continuation provisions are governed by the applicable policy.
Individually owned life insurance
An individual life insurance policy is generally purchased and owned independently of employment.
As long as required premiums are paid and the policy remains in force according to its terms, changing jobs does not ordinarily cause the policy to terminate.
Practical comparison
| Feature | Employer-sponsored group life | Individual life insurance |
|---|---|---|
| Connection to employment | Often tied to eligibility | Generally independent |
| Premium payment | Employer, employee, or both | Usually policyowner |
| Coverage after leaving a job | Depends on policy | Generally continues if maintained |
| Underwriting | Varies by plan | Usually based on individual underwriting, except certain products |
| Coverage options | Set by group plan | Based on available individual products |
| Portability or conversion | May be offered | Generally not needed solely because of a job change |
Neither type of insurance is automatically better for everyone.
Employees should understand how the different policies fit their financial circumstances.
4. What Is Life Insurance Portability?
Portability is a feature available under some group life insurance policies that allows eligible employees to continue certain coverage after losing group eligibility.
The employee may be able to maintain coverage through a continuation arrangement, subject to policy conditions.
How portability may work
A departing employee may need to:
- Confirm eligibility for portability.
- Request the applicable continuation forms.
- Submit an election within the required deadline.
- Pay premiums directly or through another approved method.
- Satisfy any additional policy conditions.
Important portability considerations
Portability is not available under every group life insurance plan.
Even when offered, it may be subject to:
- Maximum coverage amounts.
- Age limits.
- Employment termination circumstances.
- Active-at-work or disability provisions.
- Coverage eligibility restrictions.
- Premium changes.
- Other contractual requirements.
Employees should not assume portability preserves every feature of the original employer-sponsored arrangement.
The insurer's continuation materials should explain what coverage is available and on what terms.
5. What Is Life Insurance Conversion?
Conversion is another potential option when group life insurance coverage ends.
Under certain group policies, eligible employees may be permitted to convert qualifying group coverage into an individual life insurance policy.
Conversion rights and procedures vary by policy and applicable law.
How conversion differs from portability
Portability generally involves continuing eligible coverage through a group-related continuation arrangement.
Conversion generally involves obtaining an individual policy under the applicable conversion provisions.
A simplified example
Suppose an employee has $100,000 of eligible group life insurance and leaves the company.
If the policy provides a conversion right, the employee may be able to apply for an individual policy within the applicable limit and deadline.
The individual policy may have different premiums, features, and available coverage types.
Conversion does not necessarily provide the same coverage at the same price.
Is a medical examination required?
Some contractual conversion rights permit eligible employees to obtain specified individual coverage without new evidence of insurability, provided all requirements are satisfied.
However, this should not be assumed for every continuation option.
The employer should refer employees to the insurer's official conversion materials.
6. Portability vs. Conversion: Key Differences
| Feature | Portability | Conversion |
|---|---|---|
| Primary purpose | Continue eligible coverage after losing group eligibility | Obtain an individual policy under conversion rights |
| Coverage structure | Often group-related continuation | Individual policy |
| Availability | Depends on policy | Depends on policy and applicable law |
| Medical underwriting | Depends on applicable terms | Certain conversion rights may not require new medical evidence |
| Premiums | May differ from active employee rates | Based on the converted policy's terms |
| Coverage amount | Subject to limits | Subject to conversion limits |
| Deadline | Specified by plan | Specified by plan and applicable law |
| Eligibility | Subject to policy conditions | Subject to policy and legal conditions |
Employees should review the actual insurer documents before choosing either option.
7. Why Continuation Deadlines Matter
Portability and conversion rights generally require action within a limited period.
The deadlines may be shorter than employees expect.
Some policies use deadlines measured in weeks rather than months.
Why employers should avoid generic deadline statements
An employer should not tell every departing employee that they have 30, 31, or 60 days to act.
The correct period depends on the policy and applicable law.
For example, certain group life insurance conversion arrangements may involve a 31-day period, but that is not a universal rule for every policy or continuation option.
What employees need to know
An offboarding notice should identify:
- The coverage termination date.
- Whether portability is available.
- Whether conversion is available.
- The exact applicable election deadlines.
- How to obtain and submit forms.
- Where premiums must be paid.
- How to contact the insurer.
Employees should be encouraged to act promptly rather than waiting until the deadline approaches.
8. What Happens to Voluntary Life Insurance After Resignation?
This is a common source of confusion.
An employee may have purchased voluntary life insurance for several years through payroll deductions.
Because the employee paid the premiums, they may believe the policy automatically belongs to them and continues after resignation.
That assumption may be incorrect.
Voluntary life insurance can still be governed by an employer-sponsored group policy.
When employment eligibility ends, the voluntary coverage may also end unless a continuation provision applies.
Example
An employee has:
- $50,000 in employer-paid basic life insurance.
- $200,000 in employee-paid voluntary life insurance.
The employee leaves the company.
Depending on the group policy, both coverage components may terminate.
However, the employee may have different portability or conversion options for the two amounts.
The employer should confirm the continuation rules for each coverage component rather than treating all life insurance as a single benefit.
9. What Happens When an Employee Retires?
Retirement may involve different insurance provisions from an ordinary resignation.
Some employers offer retiree life insurance benefits.
Others do not.
Some plans may reduce coverage amounts at specified ages or upon retirement.
Employers should verify:
- Whether retiree coverage exists.
- Whether the employee meets retirement eligibility conditions.
- Whether the death benefit changes.
- Whether premiums become employee-paid.
- Whether portability or conversion is available.
- When any coverage changes take effect.
Employees approaching retirement should receive information early enough to review their options.
Retirement planning should include understanding how workplace life insurance may change.
10. What Happens After a Layoff?
Employees affected by layoffs may face immediate financial uncertainty.
Losing workplace life insurance can add to that concern.
Depending on the policy, a laid-off employee may have continuation options similar to those available after resignation.
However, employers should verify the actual terms.
Why communication matters
Employees managing a layoff may be dealing with:
- Loss of income.
- Changes in health coverage.
- Household budget adjustments.
- Job searching.
- Family financial responsibilities.
Clear life insurance information can help employees make decisions before coverage deadlines expire.
Employers should provide factual information without implying that continuation is guaranteed.
11. Does COBRA Continue Employee Life Insurance?
Generally, no.
Federal COBRA continuation requirements apply to qualifying group health plans, not ordinary group-term life insurance simply because it is an employee benefit.
Employees sometimes confuse COBRA with the continuation of all employer-sponsored benefits.
Important distinction
COBRA may allow eligible individuals to continue certain group health coverage after a qualifying event.
It does not automatically continue group life insurance.
Life insurance continuation must be evaluated separately under the applicable insurance policy and any relevant legal requirements.
What HR teams should communicate
When discussing COBRA or health benefit continuation, employers should separately address life insurance.
A clear statement might be:
"Your medical coverage continuation options and your life insurance continuation options are different. Please review the separate life insurance information provided."
12. Can an Employee Buy New Individual Life Insurance Instead?
Yes, employees may explore individual life insurance outside their employer-sponsored plan.
For example, a departing employee might consider a personally owned term life insurance policy.
Potential advantages
An individually owned policy is generally not tied to the employee's current employer.
It may allow the applicant to select a coverage amount and term based on personal needs, subject to product availability and underwriting.
Important considerations
Individual life insurance may require underwriting.
Premiums can depend on factors such as:
- Age.
- Health.
- Tobacco use.
- Coverage amount.
- Policy duration.
- Insurer pricing.
Approval is not guaranteed.
Avoiding a coverage gap
Employees considering a replacement policy should understand that applying for insurance does not mean coverage is active.
They should verify approval, effective dates, and premium requirements before relying on a new policy.
They should also avoid canceling existing coverage prematurely.
13. A Practical Coverage Transition Example
Consider a hypothetical employee named Michael.
Michael is 42 years old, earns $85,000 annually, and has two children.
His workplace benefits include:
- $85,000 in employer-paid basic life insurance.
- $150,000 in voluntary life insurance.
His total workplace coverage is $235,000.
Michael accepts a job at another company.
His new employer offers basic life insurance, but the coverage does not begin immediately.
What should Michael review?
First: When does the existing employer's coverage end?
Second: Are portability or conversion options available?
Third: When does the new employer's coverage become effective?
Fourth: Does the new employer offer voluntary or supplemental life insurance?
Fifth: Would an individually owned policy help address any potential gap?
Michael should also review whether the combined coverage amount meets his household's financial responsibilities.
The lesson for employers
A job transition can involve both a temporary coverage gap and a longer-term change in the amount of insurance available.
Clear communication helps employees understand these risks before making decisions.
14. The Employer's Role During Offboarding
Employers should establish a consistent process for communicating life insurance termination and continuation information.
Confirm the employee's coverage
Determine which basic, voluntary, supplemental, spouse, or dependent coverage components are active.
Verify the termination date
Use the insurer's policy and eligibility rules.
Identify continuation options
Confirm whether portability, conversion, retiree coverage, or other provisions apply.
Provide required documents
Supply the appropriate insurer materials and any legally required notices.
Explain deadlines
Use the actual deadline associated with each applicable option.
Explain premium responsibilities
Employees should know whether they must begin paying premiums directly.
Provide insurer contact information
Employees should have a reliable way to obtain further assistance.
Maintain records
Document the communications and administrative actions taken, consistent with applicable requirements.
A consistent offboarding process can reduce confusion and administrative errors.
15. Who Is Responsible for Explaining Conversion Rights?
Responsibilities depend on the policy, administrative arrangement, and applicable law.
In some situations, the insurer provides continuation forms and notices.
In others, the employer or plan administrator may have specific communication obligations.
Employers should not assume that an insurance carrier will automatically handle every required notice.
Recommended approach
HR teams should work with their insurer, broker, benefits administrator, and legal advisers to establish:
- Who determines eligibility.
- Who prepares the notice.
- Who delivers it.
- When it must be delivered.
- How delivery is documented.
- Who answers employee questions.
This process should be reviewed whenever the insurance carrier or plan design changes.
16. What Happens to Spouse and Dependent Life Insurance?
Some employer-sponsored plans include optional spouse or dependent life insurance.
When the employee leaves the company, these benefits may also terminate.
Continuation options may differ from those available for the employee's own coverage.
For example, a group policy might provide a conversion option for certain dependent coverage but not portability.
Another policy may have different rules.
Important questions
Employers should determine:
- Which dependents are currently covered.
- Whether dependent coverage terminates with employee coverage.
- Whether continuation options are available.
- Whether separate forms or elections are required.
- Whether the same deadlines apply.
Employers should not assume that continuing the employee's coverage automatically continues dependent coverage.
17. Common Employee Misunderstandings
Several misunderstandings can create unexpected insurance gaps.
"I paid for my voluntary life insurance, so I can keep it automatically."
Not necessarily.
Employee-paid group coverage may still end when employment eligibility ends.
"My new employer will provide the same amount."
Not necessarily.
Coverage amounts and eligibility rules differ between employers.
"COBRA will continue all my benefits."
No.
COBRA does not automatically continue ordinary group life insurance.
"I can convert my group coverage whenever I want."
Conversion rights generally have eligibility requirements and deadlines.
"My coverage continues until I find another job."
Not unless the policy provides for that continuation.
"I applied for a new policy, so I am already covered."
Not necessarily.
A new policy may require underwriting approval, payment, and satisfaction of effective-date conditions.
Employers can address these misconceptions through a simple written benefits transition guide.
18. How Employers Can Build a Life Insurance Offboarding Checklist
A standardized checklist helps ensure important details are not missed.
Employee life insurance offboarding checklist
- [ ] Confirm the employee's last day of employment.
- [ ] Identify all active life insurance coverage.
- [ ] Verify the actual termination date for each benefit.
- [ ] Check eligibility for portability.
- [ ] Check eligibility for conversion.
- [ ] Review spouse and dependent coverage.
- [ ] Confirm applicable deadlines.
- [ ] Provide official insurer continuation documents.
- [ ] Explain direct premium payment requirements.
- [ ] Provide insurer contact information.
- [ ] Communicate the information in an accessible format.
- [ ] Document required notices and delivery.
- [ ] Coordinate payroll deduction termination.
- [ ] Retain appropriate administrative records.
Employers should adapt this checklist to their policy terms and applicable legal requirements.
19. How Turtelle Can Help Employees Understand Coverage Gaps
Job changes are one of the life events that can prompt employees to review their financial protection.
Turtelle Insurance is an insurance technology platform focused on helping individuals and families better understand life insurance.
Employees who are leaving a company may benefit from reviewing their current coverage and household financial responsibilities.
Turtelle's Family Protection Check provides an educational assessment of financial protection needs.
Its proprietary, rule-based Family Protection Score helps communicate assessment results based on information provided by the user.
The score is not AI-generated.
The assessment can help users consider:
- How much life insurance they currently have.
- Whether workplace coverage may be ending.
- How much household income depends on them.
- Outstanding debts and financial obligations.
- Future family expenses.
- Potential gaps in protection.
These tools are educational and do not guarantee coverage, rates, eligibility, or policy approval.
Turtelle does not issue or underwrite insurance policies.
Employees should confirm continuation rights with their employer and insurer before making coverage decisions.
20. Best Practices for Employers
Employers can make life insurance transitions easier by following a few principles.
Communicate early
Where possible, provide coverage information before the employee's final day.
Use accurate plan-specific information
Avoid generic statements about termination dates, continuation rights, or deadlines.
Explain all affected coverage
Address basic, voluntary, supplemental, and dependent coverage separately when applicable.
Distinguish portability from conversion
Employees should understand that these are different arrangements.
Provide written instructions
Employees should receive information they can refer to after leaving the company.
Coordinate with insurers and administrators
Confirm eligibility, forms, notices, and deadlines.
Respect employee privacy
Do not request unnecessary personal medical or financial information.
Review the process regularly
Update offboarding materials when carriers, policies, or administrative procedures change.
Final Thoughts
Leaving a company can be a major financial transition.
For employees who rely on workplace life insurance, that transition may also affect their family's financial protection.
Employer-sponsored coverage often ends when employment eligibility ends, but some policies provide portability, conversion, or other continuation options.
The availability, cost, and deadlines for those options vary.
Employers can help by confirming coverage termination dates, explaining available rights, providing accurate documents, and communicating important deadlines.
Employees, in turn, should review their coverage before leaving, understand any continuation options, and consider whether their overall financial protection remains appropriate.
A clear life insurance offboarding process is an important part of responsible employee benefits administration—and can help families avoid unexpected gaps in coverage.
Explore Employer Solutions
See how Turtelle helps employers manage group life insurance and help employees understand their protection.
Explore Employer SolutionsFrequently asked questions
Does life insurance automatically end when an employee resigns?
Employer-sponsored group life insurance often ends when employment eligibility ends. However, the exact termination date depends on the policy, and some employees may have continuation rights.
Can employees keep voluntary life insurance after leaving a company?
Possibly. Even employee-paid voluntary coverage may be part of a group policy. Eligible employees may have portability or conversion options, depending on the insurer and plan.
What is the difference between portability and conversion?
Portability generally allows eligible employees to continue certain group-related coverage after leaving employment. Conversion generally allows eligible employees to obtain an individual life insurance policy under specified conditions.
Does COBRA cover employee life insurance?
No. Federal COBRA applies to qualifying group health coverage and does not cover plans providing only life insurance or disability benefits.
What should employers provide when an employee leaves?
Employers should confirm the coverage end date, explain applicable continuation options, provide required notices and insurer forms, identify deadlines, and supply insurer contact information.
Sources
- Employer's COBRA Guide, U.S. Department of Labor
- Worker's COBRA Guide, U.S. Department of Labor